Hello, this is Daily Stock, delivering an in-depth analysis of daily market trends and key corporate movers.
[Image: /stdaily/uploads/202610/gen_6ac0a82419e167.67917081.png]
Executive Summary
Kia posted its highest-ever quarterly sales in North America with 236,659 units in the third quarter, boosting the likelihood of securing the No. 3 spot in the local market.
The primary growth engine was its hybrid electric vehicle (HEV) lineup, which surged more than 77% year-over-year, completely offsetting concerns over the electric vehicle adoption slowdown.
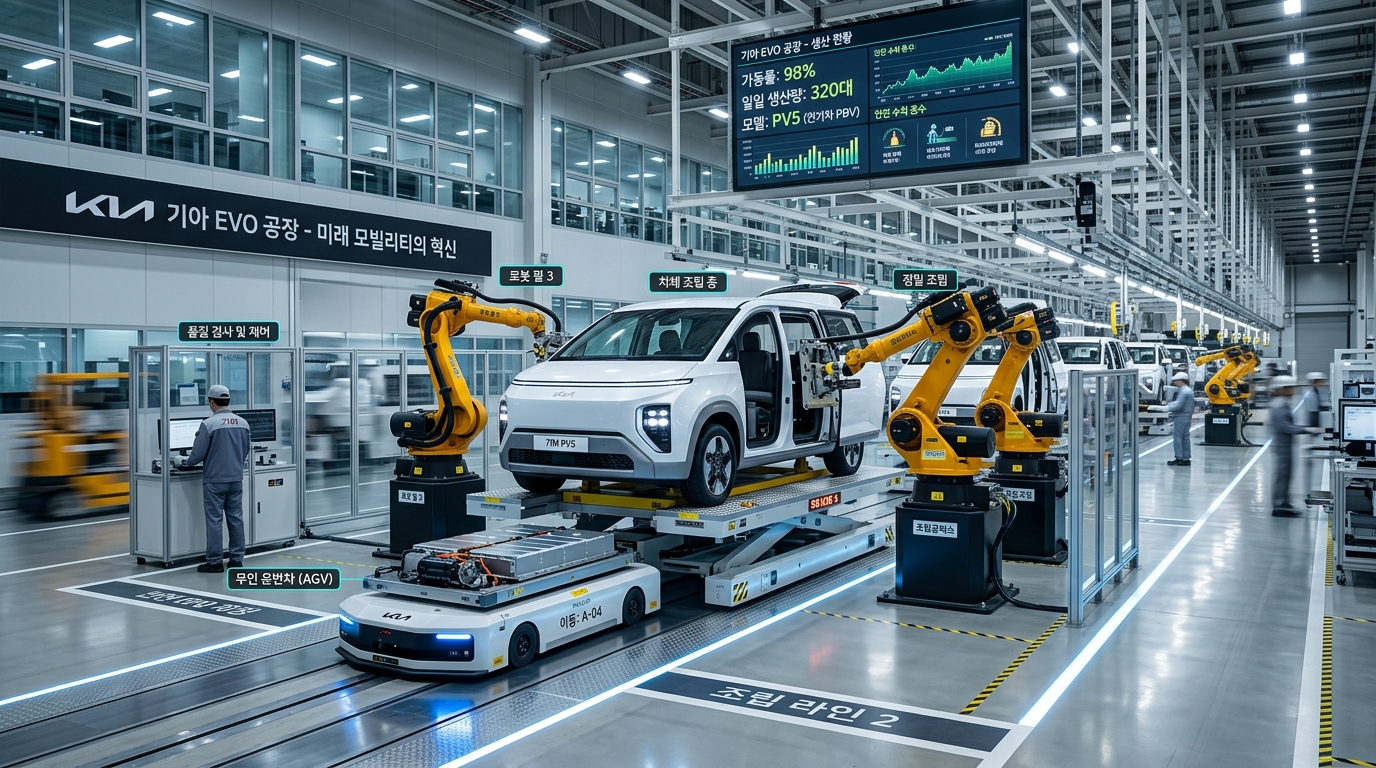
With the full-scale operation of 'Hwaseong EVO Plant East'—the dedicated Purpose-Built Vehicle (PBV) manufacturing hub at AutoLand Hwaseong—mass production of the midsize PBV, PV5, has officially taken root.
Expanding toward an annual capacity of 250,000 units, this PBV infrastructure serves as a core catalyst advancing Kia beyond traditional vehicle manufacturing into a customized mobility solutions provider.
Current Market Context
As of the close on October 3, 2026, domestic and global financial markets are navigating a new turning point amid macro variables and supply-demand tensions.
The KOSPI closed at 7,003.74, the KOSDAQ at 893.29, the U.S. Nasdaq at 27,190.86, and the USD/KRW exchange rate finished at 1,347.00 KRW.
According to Daily Stock's proprietary Fear & Greed Index, the KOSPI is currently in Neutral (41.9), showing a clear sentiment recovery compared to Neutral (40.5) one week ago, Fear (28.7) one month ago, and Extreme Fear (15.1) three months ago.
In contrast, the Nasdaq stands in Fear (31.2), reflecting a slight dominance of risk-averse sentiment compared to Fear (36.9) a week ago, Neutral (46.1) a month ago, and Neutral (54.5) three months ago.
Over the holiday weekend, market trading for Kia (000270) was closed, with the latest available closing price recorded at 112,100 KRW on October 2.
Combined Q3 U.S. sales for Hyundai Motor and Kia surpassed 506,200 units, making it highly probable that the group will overtake Ford to enter the U.S. "Big 3" on a quarterly basis for the first time in history.
Underpinning this solid performance is the strong momentum of high-margin recreational vehicles (RVs)—including the Sportage, Telluride, and Sorento—alongside eco-friendly models led by the Carnival Hybrid.
Kia's Q3 hybrid sales in the U.S. alone reached 68,336 units, heavily driving the optimization of its product sales mix.
[Image: /stdaily/uploads/202610/gen_6ac0a8303cf641.04648533.png]
Financial Analysis
Kia’s recent performance demonstrates profitability metrics ranking at the top tier of the global automotive industry.
The company continues to maintain robust double-digit operating profit margins (OPM) and stable quarterly operating profits around the 3 trillion KRW mark.
Quickly expanding the supply of highly profitable hybrid models via flexible mixed-model production lines amid the EV chasm was the primary contributor to defending earnings.
A rising proportion of high-value trims coupled with disciplined incentive policies has kept average selling prices (ASP) in North America on an upward trajectory.
| Metric | 2024 Actual | 2025 Actual | Q3 2026 (Cumulative Est.) | Key Highlights & Remarks |
|---|---|---|---|---|
| **North America Sales** | ~782,000 units | ~825,000 units | Q3: 236,000 units (Quarterly Record) | Highly likely to rank 3rd in U.S. for the quarter |
| **North America HEV Sales** | ~135,000 units | ~182,000 units | Q3: 68,000 units (+77% YoY jump) | Driven by Carnival and Sportage HEV |
| **Operating Margin (OPM)** | 11.6% | 11.2% | Mid-to-high 10% range | Top-tier profitability among global OEMs |
| **Dedicated PBV Capacity** | Initial construction | East Plant completed (100k units) | On track for 250k-unit capacity | Integrated Phase 1 & 2 at Hwaseong EVO Plant |
The Hwaseong EVO Plant, representing a total investment of 4 trillion KRW, maximizes fixed-cost savings through 100% automated body welding and smart logistics AGVs.
Even with significant initial capital expenditure deployments, Kia retains a solid financial foundation and a net cash balance sheet, underpinned by strong cash generation.
Valuation
Currently, Kia trades at a Price-to-Earnings Ratio (PER) of 4–5x and a Price-to-Book Ratio (PBR) of 0.7–0.8x.
Compared to global peers such as Toyota (PER 8–10x), GM, or Ford, Kia remains structurally undervalued.
Despite boasting high profitability with a Return on Equity (ROE) well above 15%, the market has excessively discounted peak-out concerns for an extended period.
However, with consecutive record-breaking quarterly sales and tangible progress in the new PBV segment, justification for a valuation re-rating is strengthening.
Downside support is further reinforced by share repurchases and cancellations aligned with the South Korean government's Corporate Value-up Program, alongside a total shareholder return ratio in the mid-30% range.
With an expected annual dividend yield hovering around 5%, Kia’s appeal as a value stock remains prominent among KOSPI large-cap names.
Expert & Institutional Insights
Domestic brokerages and global investment banks are giving high marks to Kia's agile powertrain strategy.
By promptly bolstering its hybrid engine lineup during the EV transition plateau, Kia successfully addressed regulatory mandates and consumer demand across North America and Europe simultaneously.
Consensus suggests that the automotive sector firmly acts as an earnings stabilizer among large caps in the KOSPI 200.
While room remains for the Bank of Korea to pivot toward monetary easing, automobiles continue to drive record trade surpluses on a single-item basis in export-import trends.
With the USD/KRW exchange rate maintaining elevated levels near 1,347 KRW, KRW-converted export margins remain favorable.
While foreign investor flows reflect near-term volatility from futures rollover and currency swings, an overweight stance on automotive blue chips with clear earnings visibility continues.
Industry analysts highlight that the flexible multi-model production system at the Hwaseong EVO Plant (mixed production of up to 180 configurations) marks a paradigm shift in manufacturing.
Once the West Plant is completed by 2027, the addition of large PBV lineups like the PV7 is expected to position Kia favorably in the customized B2B mobility market with an annual capacity of 250,000 units.
[Image: /stdaily/uploads/202610/gen_6ac0a83bb6f195.00715401.png]
Risk Factors
The primary external variable requiring close scrutiny is potential shifts in North American trade policy and clean vehicle tax credit guidelines.
Depending on U.S. election outcomes and trade postures, higher tariff barriers could trigger stronger demands for expanded local production.
Weakened consumer sentiment from a prolonged global economic slowdown and elevated auto loan interest rates also present potential headwinds.
A sudden drop in the USD/KRW exchange rate could diminish foreign exchange gains, making currency volatility management essential.
Furthermore, in the PBV sector, the adoption pace by B2B corporate clients across logistics, shuttles, and specialized conversions could face unexpected delays.
Ensuring software stability and adhering to data security regulations during the buildout of the Software-Defined Vehicle (SDV) platform will require continuous monitoring.
Investment Perspective Summary
Kia is dispelling peak-out concerns by navigating the EV chasm on the back of hybrid-driven growth.
The record Q3 North American sales figure is not accidental; it is the culmination of strong product competitiveness combined with flexible production capabilities.
In the short term, investors should track foreign supply-demand dynamics across spot and futures markets around the Q3 earnings release against a 1,347 KRW exchange rate backdrop.
With the KOSPI at the 7,000 level, a strategy focused on screening large caps that offer attractive valuations relative to earnings remains compelling.
From a medium- to long-term perspective, rising utilization rates at the Hwaseong EVO Plant and the global reception of the PV5 will serve as the definitive inflection point for corporate re-rating.
A phased accumulation strategy—hedging market volatility via dividend stability and low-PBR fundamentals while monitoring order momentum in the PBV business—remains a prudent approach.
Daily Stock Q&A
Q1. What was the core driver behind Kia's record sales in North America?
It was Kia’s agile response to explosive hybrid (HEV) demand. In Q3, Kia’s North American hybrid sales rose roughly 77% year-over-year to 68,336 units, driving total volume.
Q2. How is the Hwaseong 'EVO Plant' different from conventional internal combustion engine plants?
It is Hyundai Motor Group’s first dedicated smart PBV factory, featuring 100% automated body welding and sequential assembly methods. It is an advanced facility capable of flexibly manufacturing over 180 different PV5 configurations on a single line.
Q3. Is mass PBV production an overinvestment during the current EV slowdown?
PBVs target actual demand from corporate B2B clients in logistics, cargo, and accessible mobility rather than standard retail consumers. Strong replacement demand from corporate fleets exists due to maintenance savings and loading efficiency, with mixed production helping mitigate risk.
Q4. What are the current valuation and shareholder return levels?
Trading at a PER of 4–5x and PBR of 0.7–0.8x, Kia is undervalued relative to global peers while sustaining an ROE above 15%. Consistent share buybacks/cancellations and an anticipated annual dividend yield of around 5% offer firm downside support.
Q5. How do a 1,347 USD/KRW exchange rate and Bank of Korea interest rate paths impact Kia?
A high exchange rate environment is favorable, increasing KRW-converted revenues and operating margins for Kia given its high proportion of overseas sales. A stabilized benchmark interest rate moving forward could ease auto financing costs for consumers, supporting a broader demand recovery in global auto markets.