Hello, this is Daily Stock.
[이미지: /stdaily/uploads/202610/gen_6abe0571881f76.41630505.png]
Key Summary
Doosan Enerbility is expanding its footprint in Small Modular Reactor (SMR) orders while coordinating detailed process schedules for the Czech Dukovany nuclear power plant project.
The synergy between its manufacturing capabilities in primary equipment for large-scale nuclear plants and strategic partnerships with leading global SMR players such as NuScale Power and TerraPower is translating into tangible order outcomes.
On October 1, 2026, the domestic market closed with the KOSPI index at 6,971.35 and the KOSDAQ index at 894.29.
The KRW/USD exchange rate closed at 1,359.50 KRW, while the U.S. NASDAQ index recorded 26,861.06.
According to Daily Stock's proprietary Fear & Greed Index, the KOSPI Fear & Greed Index stands at Neutral (40.1), showing prevailing wait-and-see sentiment compared to Neutral (52) a week ago, Neutral (47.9) a month ago, and Fear (23.4) three months ago.
The NASDAQ Fear & Greed Index is currently in Fear (30.7), reflecting ongoing caution regarding global tech stock volatility compared to Fear (35.7) a week ago, Neutral (44.9) a month ago, and Neutral (52.5) three months ago.
Current Status Overview
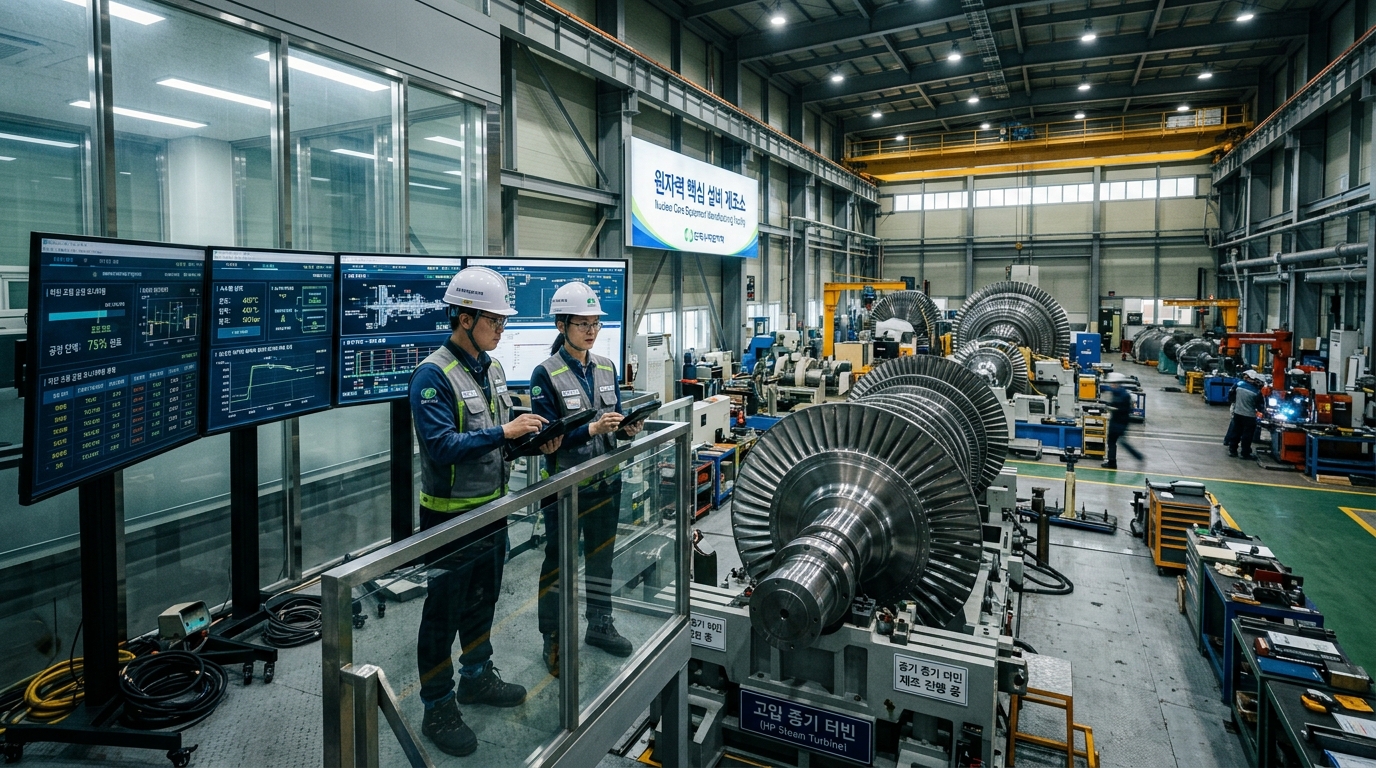
Following the selection of the Korea Hydro & Nuclear Power (KHNP)-led 'Team Korea' as the preferred bidder for the new nuclear project in the Czech Republic, Doosan Enerbility is smoothly preparing the manufacturing of core primary equipment, including steam turbines and the Nuclear Steam Supply System (NSSS).
In particular, by meeting localization requirements through turbine supply contracts via its Czech subsidiary Doosan Škoda Power, the company is solidifying its bridgehead into the European market.
At the same time, next-generation SMR pipeline orders are materializing, including the fabrication of reactor internals for TerraPower's Natrium sodium-cooled reactor in the U.S. and forging materials for NuScale Power.
Furthermore, additions of combined-cycle power equipment orders, such as the O Mon 3 combined-cycle gas turbine project in Vietnam, highlight balanced growth across its dual pillars of nuclear and gas turbines.
On the day, Doosan Enerbility's share price closed unconfirmed (around 80,000 KRW based on recent records), testing solid downside support.
[이미지: /stdaily/uploads/202610/gen_6abe057ee7f3f4.33028129.png]
Financial Analysis
Doosan Enerbility's standalone and consolidated financial fundamentals are demonstrating an improving trajectory, supported by increased fabrication volumes of power generation primary equipment and expanding gas turbine orders.
First-half consolidated operating profit reached 547.8 billion KRW, marking double-digit year-over-year growth.
The order backlog for Enerbility's core business surpassed 26 trillion KRW, securing a stable pipeline of work for the next 3 to 4 years.
| Financial Item | FY 2024 | FY 2025 | 1H 2026 Cumulative |
|---|---|---|---|
| Consolidated Revenue | 16.2330 trillion KRW | Around 17.0500 trillion KRW | Around 8.9000 trillion KRW |
| Consolidated Operating Profit | 1.0180 trillion KRW | Around 1.2500 trillion KRW | 547.8 billion KRW |
| Enerbility Order Backlog | Approx. 16.2000 trillion KRW | Approx. 23.0472 trillion KRW | Surpassed 26 trillion KRW |
| Annual New Orders | Around 8.8000 trillion KRW | 14.7280 trillion KRW | 7.1000 trillion KRW achieved |
Given the nature of nuclear projects, design and material procurement costs are front-loaded during initial construction phases, but profit margins are expected to improve starting in 2026–2027 as full-scale primary equipment manufacturing begins.
Excluding subsidiary earnings volatility, the operating profit generation capacity of Enerbility's standalone business operations is staging a structural rebound.
Valuation
Doosan Enerbility is undergoing a valuation rerating from a conventional plant EPC contractor to a core manufacturer of primary equipment for nuclear power and gas turbines.
While the average 12-month forward price-to-earnings ratio (PER) for large plant and heavy industry sectors in the KOSPI 200 sits around 15–18x, the company is trading near 20x, reflecting an SMR premium.
A qualitative step-up in price-to-book ratio (PBR) is anticipated once revenue recognition from the definitive Czech nuclear contract and initial U.S. SMR batches begins in earnest.
Compared to global peer groups like NuScale Power in the U.S. and Framatome in France, Doosan Enerbility presents relative valuation appeal backed by superior delivery compliance and foundry-scale manufacturing capacity.
However, any delays in next-generation reactor commercialization schedules could temporarily compress this multiple premium.
Expert & Institutional Analysis
Securities analysts view the nuclear order rally positively, alongside expanding demand for gas turbines and SMRs driven by power needs from AI data centers.
Major institutions, including iM Securities, analyze that Doosan's quasi-monopolistic positioning within the supply chain will become more pronounced as progress on TerraPower and NuScale projects is confirmed.
Foreign investors have shown a selective net-buying stance toward export-oriented heavy manufacturers like defense and nuclear power amid the KRW/USD exchange rate fluctuating in the upper 1,350s.
While domestic large-cap markets face liquidity concentration in semiconductors, autos, and financials, the power infrastructure theme has emerged as a solid alternative pillar.
Amid the Bank of Korea's policy rate freeze and the ongoing global energy infrastructure investment cycle, institutional consensus favors overweighting the stock over the mid- to long term.
Risk Factors
The primary risk to monitor is potential geopolitical litigation and licensing delays tied to overseas nuclear export orders.
Should intellectual property disputes with U.S.-based Westinghouse or design approval processes by regulatory bodies take longer than expected, project progress could face delays.
In addition, sharp volatility in the KRW/USD exchange rate poses foreign exchange profit/loss fluctuation risks during payment collections and raw material settlements for overseas plant projects.
If execution of power grid investments by major economies slows due to a global economic downturn, constraints could emerge in meeting new order targets.
Until the commercial viability of SMR models is fully proven, investors should remain mindful of share price volatility, as market expectations rather than near-term earnings continue to drive the stock.
Investment Perspective Summary
Doosan Enerbility possesses structural growth drivers through steady progress on the Czech nuclear project and its entrenched position across the SMR supply chain.
In the short term, key catalysts include meeting the 2H 2026 new order target of 13.3 trillion KRW and securing follow-up contracts for major overseas projects.
With the KOSPI Fear & Greed Index lingering at Neutral (40.1) and broad market momentum subdued, a phased-entry approach focused on order-based industries with high earnings visibility remains practical.
From a macroeconomic angle, an extended investment horizon is warranted while closely monitoring currency trends and foreign investor flows.
Given its technological competitiveness and robust order backlog, the company's core upside potential from the mid- to long-term energy transition cycle remains intact.
Investor Checkpoint Q&A
Q1. What is Doosan Enerbility's primary role in the Czech nuclear power project?
A. It fabricates and supplies primary equipment, including the Nuclear Steam Supply System (NSSS)—such as steam generators and reactor vessels—and steam turbines. Its local Czech subsidiary, Doosan Škoda Power, will handle the local turbine supply.
Q2. Who are the company's major clients in the global SMR market?
A. Key partners include TerraPower, a U.S. leader in fourth-generation small modular reactors, and NuScale Power, a pioneer in light-water SMR designs, for which Doosan handles primary equipment fabrication.
Q3. What is the full-year 2026 order target and the 1H achievement status?
A. The full-year guidance is approximately 13.3 trillion KRW. In the first half, the company secured 7.1 trillion KRW, led by gas turbines and combined-cycle plant equipment, achieving over 50% of the target.
Q4. How does the current KRW/USD exchange rate environment affect financial performance?
A. The elevated FX environment at 1,359.50 KRW positively impacts KRW-converted revenues and profitability on overseas order projects, although intensified exchange rate volatility brings higher procurement cost burdens for imported raw materials.
Q5. What is the key short-term variable that investors must watch closely?
A. The coordination of detailed contract timelines with the Czech government, progress on global cooperation agreements with Westinghouse, and construction approval status for initial SMR units.