Hello, this is Daily Stock, delivering everyday market context.
[Image: /stdaily/uploads/202610/gen_6ac5ee5c6de6c1.93229892.png]
Key Summary
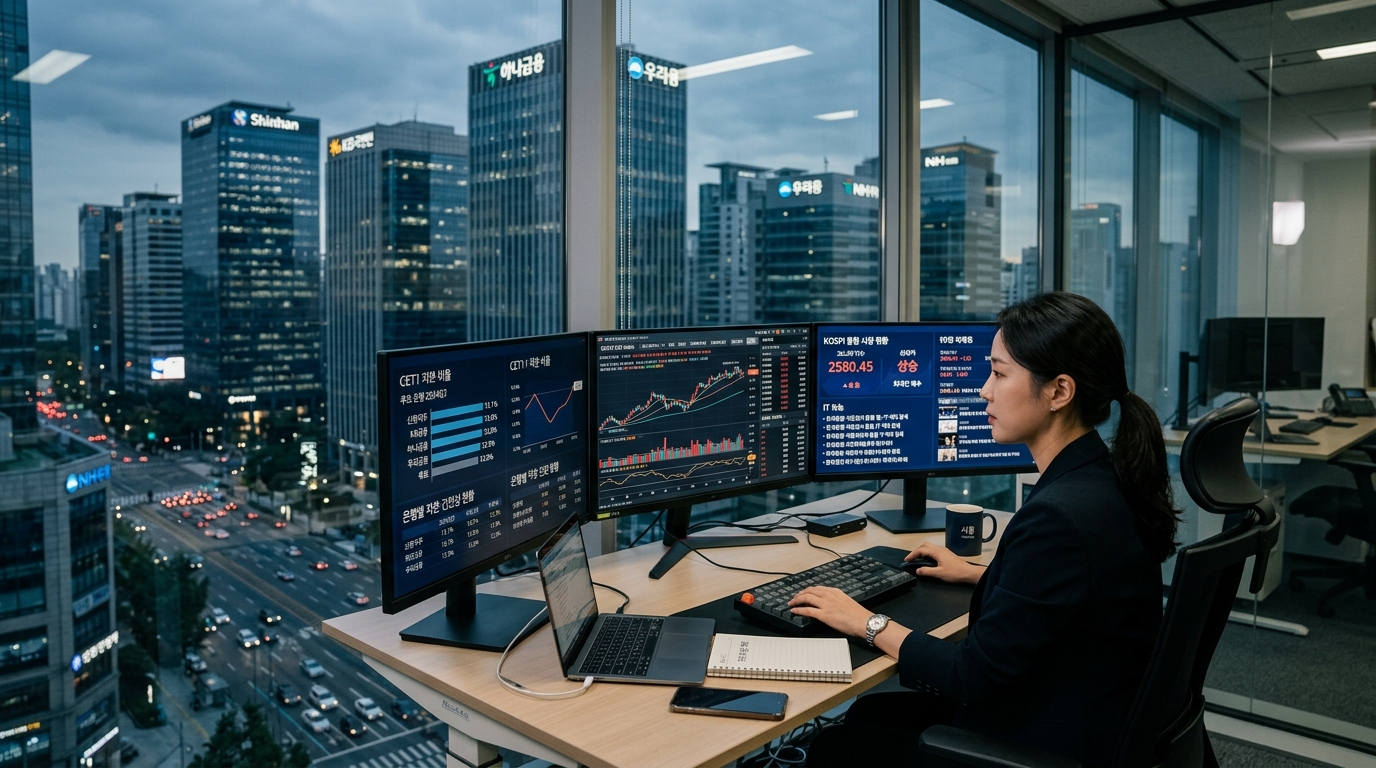
KB Financial Group (105560) is drawing significant market attention ahead of its third-quarter earnings release by reactivating its Common Equity Tier 1 (CET1) ratio-based shareholder return framework.
Under its policy of linking surplus capital exceeding a 13.5% CET1 ratio to dividends, share buybacks, and cancellations throughout the year, confirming the size of additional share buybacks in this quarterly settlement has emerged as a key focal point.
As the KOSPI index takes a breather led by large-cap stocks around the 6,803.90 level, capital efficiency and shareholder value enhancement policies are serving as downside anchors for the financial sector.
Current Market Context
On October 7, the domestic equity market closed with remaining foreign exchange volatility as the USD/KRW exchange rate recorded 1,340.00 won.
The KOSPI closed at 6,803.90 and the KOSDAQ at 898.43, while the Nasdaq traded around 27,599.89, absorbing both the global monetary easing path and economic slowdown concerns simultaneously.
According to Daily Stock's proprietary Fear & Greed Index, the KOSPI is currently in the Fear zone (32.5), following Fear (35.5) a week ago, Fear (32.5) a month ago, and Extreme Fear (12.5) three months ago, showing that cautious sentiment remains dominant.
In contrast, the Nasdaq Fear & Greed Index currently sits at Neutral (47.2), improved from Fear (30.3) a week ago, yet maintaining a wait-and-see stance similar to Neutral (45.2) a month ago and Neutral (51.9) three months ago.
KB Financial Group's intraday price action remains unconfirmed for the session (settling around the 160,000 won range based on the latest verified data), but bolstered by net foreign institutional cash buying and the Corporate Value-up paradigm, it retains its status as a flagship defensive stock.
[Image: /stdaily/uploads/202610/gen_6ac5ee68190892.72742672.png]
Financial Analysis
KB Financial Group's earnings resilience is anchored in the diversification effect of its non-banking affiliate portfolio and rigorous risk-weighted asset (RWA) management.
While downward pressure on Net Interest Margin (NIM) exists as the base rate enters a gradual cut cycle, loan balance growth in the banking arm and non-interest income from credit cards, securities, and insurance are cushioning the scale of profit reduction.
| Category | Key Management Indicators & Targets | Capital Allocation & Return Linked Criteria |
|---|---|---|
| **Common Equity Tier 1 (CET1) Ratio** | Target to maintain above 13.5% | 100% of capital exceeding 13.5% utilized as shareholder return funding |
| **Risk-Weighted Assets (RWA) Growth Rate** | Managed around 5% annually | Minimize capital consumption and drive RoRWA improvement |
| **Total Shareholder Return (TSR)** | Aiming for upper 40% to over 50% | Quarterly equal dividends and residual funds allocated to share buybacks & cancellations |
| **Credit Cost Ratio (CCR)** | Stable management in early-to-mid 40bp range | Preemptive risk defense for real estate PF and vulnerable borrowers |
If cumulative net profit through the third quarter stays on a solid track, surplus capital remaining after quarterly equal dividend payouts directly translates into funding for treasury stock acquisition trust contracts and cancellations.
This represents a global leading bank-style capital allocation strategy that returns capital exceeding target capital ratios to shareholders rather than focusing on quantitative expansion of earnings.
Valuation
Domestic financial holding companies have historically traded at relatively low PBR valuation multiples compared to KOSPI large-cap exporters (semiconductors and automotive).
However, as the Value-up program gains concrete form, KB Financial Group's price-to-book ratio (PBR) is breaking out of historical lows around 0.4x and gradually testing entries into the 0.6–0.7x range.
Considering that major U.S. banks trade at average PBRs of 1.1–1.3x, the reduction in floating shares via medium- to long-term treasury stock cancellations acts as leverage to raise Book Value Per Share (BPS) and Earnings Per Share (EPS) simultaneously.
Even as volatility across KOSPI 200 large caps widens, total shareholder return yields combining dividend yields and buyback-cancellation effects strongly support the valuation floor.
Expert and Institutional Analysis
The financial investment industry views the 'scale of second-half share buyback approvals'—rather than simple net profit figures—as the core metric for this third-quarter earnings report.
This is because a slowdown in the banking sector's net interest income growth is virtually taken for granted amid the Bank of Korea's base rate decisions and macro regulations on total loan volume.
Institutional investors are closely scrutinizing whether KB Financial Group's management restrained RWA growth below 5% as planned, defending the CET1 ratio around 13.7%.
Foreign institutional supply-demand dynamics are aligned with futures trading trends around the 1,340.00 won exchange rate level, yet maintain steady allocation weightings toward holding companies with high dividend predictability.
[Image: /stdaily/uploads/202610/gen_6ac5ee735996c0.61761231.png]
Risk Factors
The most critical internal and external variables to monitor are domestic and global economic slowdowns alongside foreign exchange volatility.
If the USD/KRW exchange rate surges again, foreign currency-denominated RWAs could increase, mechanically eroding the CET1 ratio.
Furthermore, rising delinquency rates and tightened household debt volume controls could constrain the bank's expansion of prime loans, potentially shrinking its interest income base.
A scenario where regulatory demands for additional provisioning during the restructuring of project financing (PF) temporarily constrain short-term distributable profit limits cannot be ruled out either.
Investment Perspective Summary
Moving beyond a conventional high-dividend stock, KB Financial Group is establishing an advanced Value-up model that flexibly expands total shareholder returns based on capital management capability.
If the excess capital return size announced alongside Q3 earnings matches market expectations, the upward trajectory of per-share value could become further reinforced.
However, a conservative approach is necessary, comprehensively accounting for margin pressure from the rate-cut cycle and macroprudential regulatory shifts.
At the portfolio level, rather than reacting to short-term price fluctuations, a prudent strategy involves continuously monitoring sustained growth in Dividend Per Share (DPS) and the execution rate of share cancellations.
Investment Checklist
- [ ] Did the CET1 ratio remain sufficiently above 13.5% at the end of Q3?
- [ ] Does the additional share buyback and cancellation size resolved in this board meeting align with market expectations (hundreds of billions of won)?
- [ ] Are the Group's NIM defense line and non-interest income contribution holding firm amid the base rate cut environment?
- [ ] Was the impact of foreign currency asset RWA growth properly managed despite the USD/KRW staying in the 1,340s?
- [ ] Is the impact on net profit limited regarding financial authorities' household debt management and real estate PF provisioning requirements?