Hello. This is Daily Stock, analyzing key value chains across global tech and the Nasdaq market.
[이미지: /stdaily/uploads/202610/gen_6ac43a56b90318.97178850.png]
Executive Summary
Micron Technology (Micron, MU) reported fiscal fourth-quarter results that far exceeded market expectations, confirming a structural boom centered on AI memory.
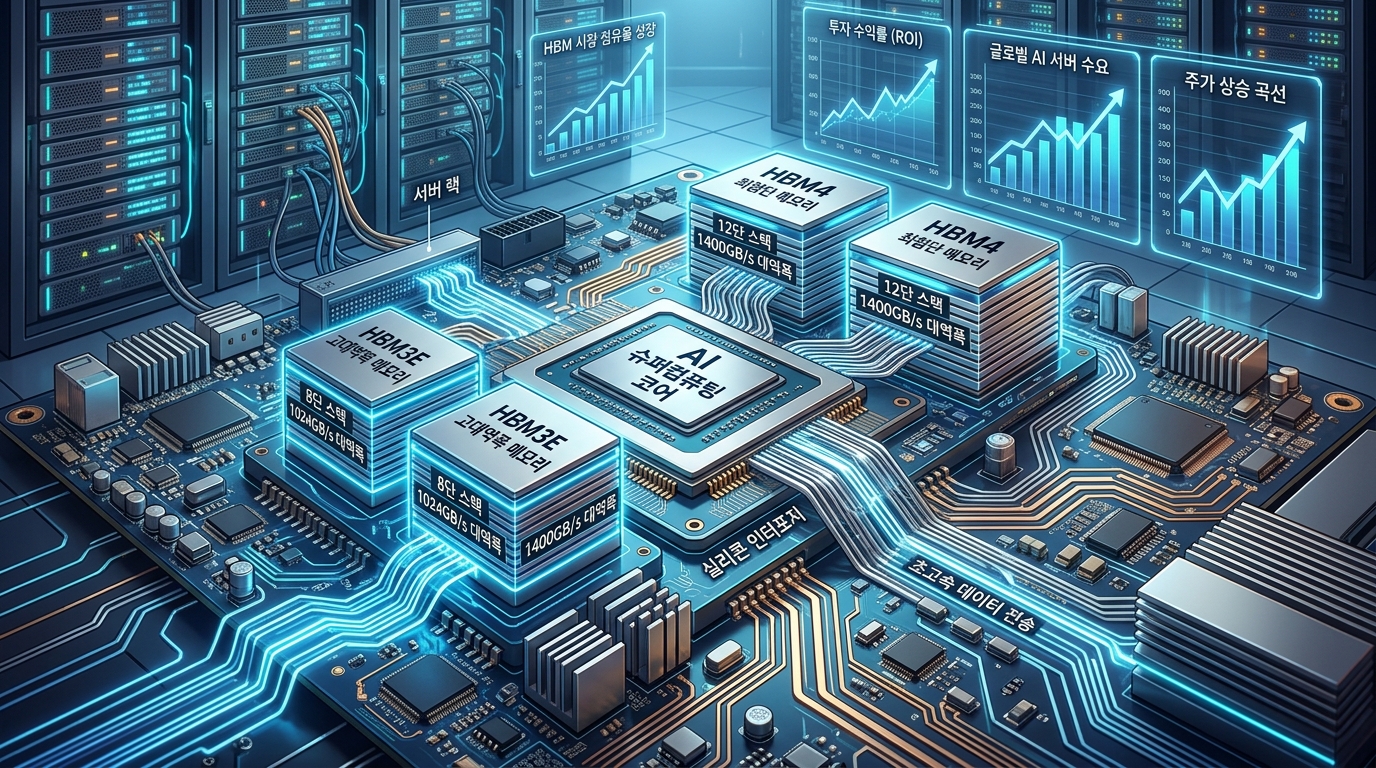
With the full-scale volume ramp-up of HBM3E and an increasingly visible supply roadmap for next-generation HBM4, forecasts projecting memory semiconductor shortages through 2027–2028 are gaining strong traction.
Most of the HBM bit shipments scheduled for production in 2027 have already been secured under long-term Strategic Commercial Agreements (SCAs) with customers at higher unit prices.
Consequently, the market's attention is focused on the potential for a multiple re-rating of Micron within the Nasdaq semiconductor sector.
As of October 6, 2026, at 9:00 AM KST (preliminary intraday data), the macro environment reflects the KOSPI at 7,053.83, the KOSDAQ at 904.26, the Nasdaq at 27,477.31, and the USD/KRW exchange rate at 1,344.00 KRW.
On Daily Stock's proprietary Fear & Greed Index, the Nasdaq currently sits in Neutral territory (43.1)—rebounding from Fear (34.4) one week ago, but still indicating prevailing caution compared to Neutral (45.2) one month ago and Neutral (52.6) three months ago.
The KOSPI is likewise at Neutral (41.9), showing a gradual recovery from Neutral (40.5) one week ago, Fear (28.7) one month ago, and Extreme Fear (15.1) three months ago.
Current Market Context
Through its recent earnings release, Micron formalized a structural transformation centered on high-bandwidth memory (HBM) for data centers, transcending a conventional memory cyclical rebound.
Driven by the sustained expansion of capital expenditure (CapEx) from Big Tech hyperscalers, HBM shipments destined for Nvidia's next-generation GPU platforms are accelerating.
In particular, with mass production and supply of 12-high (12H) HBM3E products firmly on track, timelines for sample shipments and early delivery of HBM4 targeted at next-generation architectures such as Vera Rubin are taking shape.
Because HBM manufacturing consumes roughly three times the wafer capacity of conventional DRAM, cleanroom capacity constraints in advanced process nodes are acting as a major bottleneck that keeps overall DRAM supply tightly restricted.
Meanwhile, while Micron's share price for the day remains 'intraday quote unconfirmed (based on the latest confirmed data)', the stock has maintained a solid trend, breaking above key psychological resistance levels following the recent strong earnings release.
The Philadelphia Semiconductor Sector Index (SOX) continues to demonstrate relative strength against the Nasdaq 100 Index, leading differentiated market performance centered around AI accelerators and the memory supply chain.
[이미지: /stdaily/uploads/202610/gen_6ac43a61587634.13906204.png]
Financial Analysis
Micron's fiscal fourth-quarter results substantially beat market consensus across both revenue and profitability.
Quarterly revenue reached $54.23 billion, up 379.3% year-over-year, while operating income surged 1,097.3% year-over-year to $43.751 billion.
Operating margin hit 80.7%, with GAAP net income of $37.7 billion (diluted EPS of $32.87) and Non-GAAP EPS of $33.42, far outperforming the consensus estimate of $31.61.
Gross margin surged to around 87% at the end of the quarter, clearly illustrating the transformative leverage of an expanding high-value AI memory product mix.
| Key Financial Metric | FY26 Q4 Actual | Consensus | YoY Change | Notes |
|---|---|---|---|---|
| **Revenue** | $54.23B | $51.07B | +379.3% | All-time quarterly record |
| **Operating Income** | $43.751B | ~$41.0B | +1,097.3% | Operating margin ~80.7% |
| **Non-GAAP EPS** | $33.42 | $31.61 | >10x increase | Strong earnings surprise beat |
| **Gross Margin** | 87.0% | ~86.0% | Substantial improvement | Driven by HBM & premium eSSD |
| **Quarterly CapEx** | $10.77B | - | Ongoing expansion | Focused on advanced packaging & nodes |
By business segment, enterprise SSD (eSSD) revenue for data centers reached approximately $10 billion in the quarter, expanding more than tenfold year-over-year.
Gross margin guidance for the next quarter (FY27 Q1) was set at 86.25% due to one-off costs including performance compensation; however, management views this as the cyclical floor for profitability.
Valuation
Historically, Micron traded at a persistent discount typical of traditional cyclical memory manufacturers.
However, with the share of strategic commercial agreements (SCAs) extending through 2030 projected to exceed 35% of revenue, earnings predictability has improved dramatically.
Micron's 12-month forward price-to-earnings (Forward P/E) ratio currently sits in the mid-to-high single digits (around 5–7x), aided by rapid upward revisions to EPS estimates over the next two years.
This can be interpreted as a markedly undervalued level compared to the Nasdaq 100 average or S&P 500 growth stock benchmarks.
From a macroeconomic perspective, fluctuations in the US 10-year Treasury yield (US10Y) remain a key variable driving multiple sensitivity for tech growth stocks.
Even if bond yield volatility expands, Micron's structural fundamentals—anchored by visible earnings predictability and rapidly expanding free cash flow (FCF)—possess the potential to provide a resilient downside buffer.
Expert & Institutional Analysis
Following the Q4 earnings announcement, major Wall Street investment banks uniformly raised their price targets on Micron while maintaining 'Overweight' ratings.
Leading analysts view this cycle not as a typical 3-to-4-year cyclical fluctuation, but as an entry into a 'structural supercycle' powered by the expansion of AI infrastructure.
Institutional reports emphasize that 2027 HBM supply volume is effectively sold out, with contracts locked in at double-digit percentage average selling price (ASP) increases year-over-year.
Furthermore, formal collaboration on custom HBM4E specifications ('NVHBM') indicates that Micron's standing in next-generation architecture markets is becoming increasingly entrenched.
Nevertheless, conservative institutions caution that customer inventory accumulation rates and the actual return on investment (ROI) metrics of hyperscalers' AI services must be monitored closely.
Some caution is also voiced that because DRAM margins have reached the high 80% range, any slowdown in further margin expansion could trigger short-term profit-taking.
Risk Factors
The most fundamental risk involves skepticism surrounding the long-term sustainability of Big Tech AI capital expenditure (CapEx).
Should commercial monetization of generative AI models lag market expectations, the possibility of hyperscalers moderating their data center expansion cadence cannot be ruled out.
On the macro front, strength in the US Dollar Index (DXY) and spikes in the VIX (Volatility Index) tied to geopolitical tensions could dampen capital flows into growth assets.
Additionally, if uncertainty surrounding the Federal Reserve's pivot path applies renewed upward pressure on the US 10-year Treasury yield, it could compress valuation multiples across the semiconductor sector.
From an industry perspective, investors must monitor whether rapid improvements in HBM manufacturing yields or aggressive capacity additions by competitors alleviate the supply deficit earlier than anticipated post-2027.
The tens of billions of dollars in CapEx deployed toward advanced nodes also warrant long-term observation regarding future depreciation burdens.
Investment Perspective Summary
Micron has firmly cemented its position in the three-player oligopoly governing the HBM market—the critical bottleneck of AI accelerators—and transitioned into a phase of substantial cash generation.
Stable deliveries of 12-high HBM3E and fully contracted pre-orders for 2027 allocations provide a crucial foundation underpinning earnings resilience.
From an investor standpoint, while remaining mindful of short-term volatility following sharp share price advances, the medium-term structural step-up in earnings power deserves primary focus.
With the Nasdaq Fear & Greed Index in Neutral territory (43.1) and the market free of excessive greed, the current phase offers a measured window to evaluate valuation appeal relative to fundamentals.
Rather than chasing rallies, dollar-cost averaging during consolidation periods around Treasury yield movements and Big Tech earnings releases represents a sensible approach.
Going forward, next-generation product mass-production timelines from key AI chip vendors such as Nvidia, along with the pace of HBM4 yield stabilization, will serve as decisive catalysts for share price direction.
Investor Checkpoint Q&A
Q1. What is the current progress regarding Micron's HBM3E and HBM4 supply timelines?
A. 12-high (12H) HBM3E has entered full-scale volume production and shipment, while 12-high HBM4 targeted at next-generation platforms has progressed to volume shipping. In addition, the development roadmap for customized NVHBM (HBM4E) in collaboration with Nvidia is becoming increasingly concrete.
Q2. What were the most standout metrics in the fiscal fourth-quarter results?
A. The company delivered record results with quarterly revenue of $54.23 billion (+379.3% YoY) and operating income of $43.751 billion (+1,097.3% YoY). Gross margin also reached approximately 87%, demonstrating profitability comparable to top non-memory Big Tech peers.
Q3. What is the status of HBM supply agreements for 2027?
A. Management stated that the vast majority of HBM bit shipments slated for 2027 production are already contracted with customers at fixed prices that reflect significant year-over-year price increases. This secures high medium-term earnings visibility.
Q4. Does the large-scale CapEx pose a risk of future oversupply?
A. Because HBM requires more than three times the wafer area of standard commodity DRAM, actual bit output growth remains constrained even with higher CapEx. Due to cleanroom space limitations and related factors, management anticipates that supply tightness is likely to persist through 2027–2028.
Q5. Which macroeconomic indicators require the closest attention right now?
A. Key indicators include upward volatility in the US 10-year Treasury yield (US10Y), the US Dollar Index (DXY), and the VIX (Volatility Index). Protracted higher interest rates or an escalation in risk-averse sentiment could lead to short-term multiple compression across tech equities.