Hello, this is Daily Stock.
[Image: /stdaily/uploads/202610/gen_6ac2e8af1dd082.88182939.png]
Executive Summary
Synopsys (SNPS), the global leader in Electronic Design Automation (EDA), is wrapping up regulatory approvals across major jurisdictions to finalize its acquisition of simulation software leader Ansys, triggering a structural paradigm shift across the semiconductor design ecosystem.
By securing clearance from the U.S. Federal Trade Commission (FTC), the Korea Fair Trade Commission (KFTC), and conditional approval from China’s State Administration for Market Regulation (SAMR)—subject to divestitures of optical and power analysis assets—the company has substantially cleared the overhang surrounding this mega-deal.
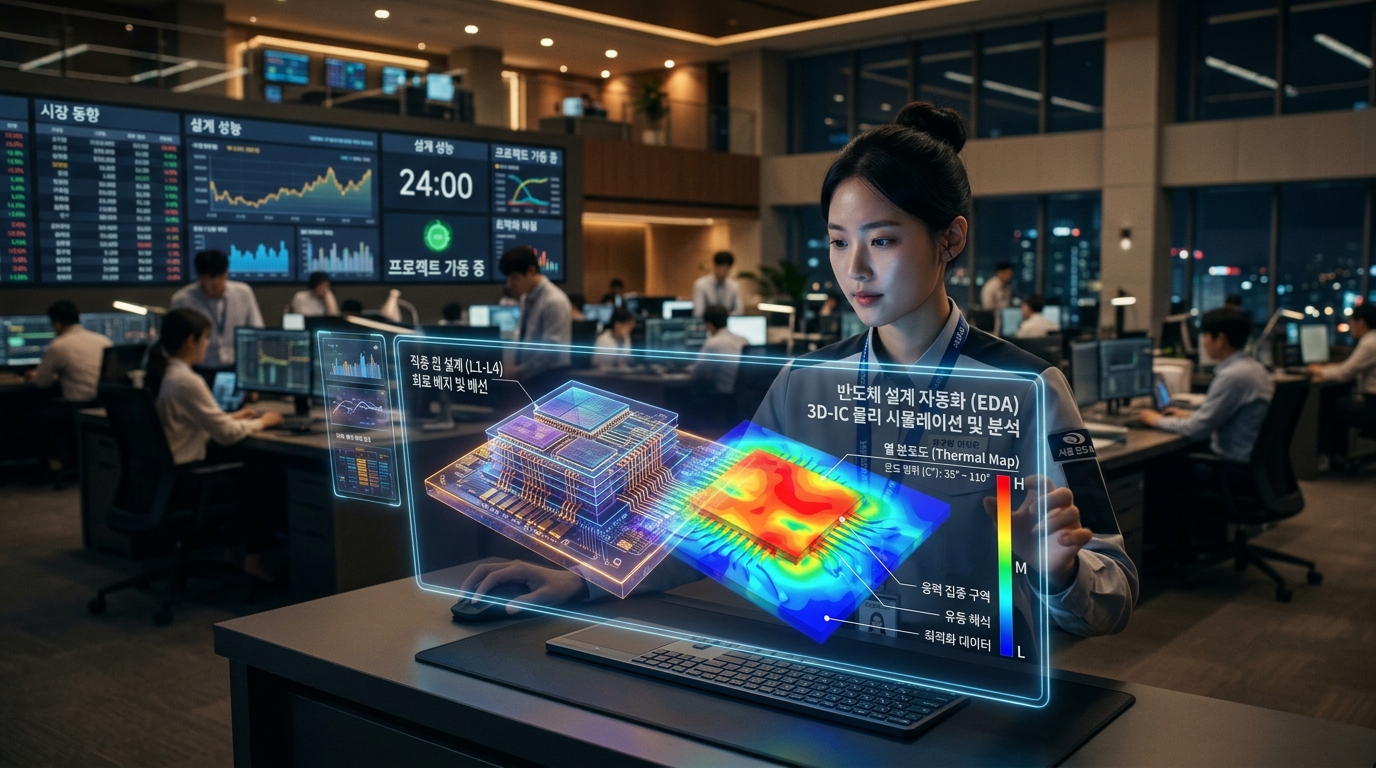
This merger extends far beyond simple scale expansion; it creates an unrivaled "Silicon to Systems" end-to-end platform essential for the 2nm and 3D-IC chiplet era.
Amid surging demand for engineering simulation to overcome physical scaling limits, Synopsys is expanding its business model from long-term software licensing toward an AI-driven, outcome-based pricing structure.
As of October 5, 2026, the Nasdaq index stands at 27,190.86, while Daily Stock's proprietary Fear & Greed Index for the Nasdaq sits in the "Fear" zone (31.2), reflecting valuation pressures across growth equities.
Amid fluctuations in the 10-year U.S. Treasury yield and ongoing debates regarding return on investment for tech AI capital expenditures (CapEx), market participants are closely watching whether the EDA sector—bolstered by pure software moats—can demonstrate differentiated resilience within the Philadelphia Semiconductor Index (SOX).
Current Market Situation
Synopsys cleared its final regulatory hurdles for the $35 billion Ansys acquisition by accepting structural remedies required by antitrust agencies, including the divestment of optical software (OSG) and RTL power analysis tools (such as PowerArtist).
The KFTC approved the transaction on the condition that the companies divest their register-transfer level (RTL) power analysis and optical software assets within six months, citing potential competition constraints.
At a recent Investor Day in New York, Synopsys announced partnerships with Amazon and OpenAI, unveiling a strategic transition from seat-based licensing toward consumption-based computing and chip performance-linked revenue models.
With demand for AI accelerators and custom ASICs surging, chip design complexity has escalated rapidly. Consequently, structural demand has entered a boom cycle for multiphysics simulation directly integrated into EDA to analyze thermal, power, and signal integrity in real time.
As of 09:00 on October 5, 2026, domestic Korean markets stand provisionally at 7,003.74 for the KOSPI and 893.29 for the KOSDAQ, with the USD/KRW exchange rate trading at 1,347.00.
The Nasdaq Fear & Greed Index reads "Fear" at 31.2, showing a notable contraction from "Fear" (36.9) one week ago, "Neutral" (46.1) one month ago, and "Neutral" (54.5) three months ago, indicating heightened sensitivity to macroeconomic factors.
[Image: /stdaily/uploads/202610/gen_6ac2e8b9b84bb0.01417359.png]
Financial Analysis
Supported by the consolidation of Ansys and accelerating adoption of its AI EDA platform (Synopsys.ai), Synopsys has expanded its order backlog beyond $11.4 billion, securing stable mid- to long-term cash flows.
Reflecting consolidated contributions from Ansys, full-year revenue guidance for fiscal year 2026 has been raised to approximately $9.61 billion–$9.74 billion.
In particular, the traditional Design Automation segment continues to drive double-digit growth, while the IP Licensing business has rebounded into the low-10% range amid foundry process miniaturization.
Non-GAAP operating margin remains robust in the mid-41% range despite short-term post-merger integration expenses, demonstrating resilient operating leverage.
| Key Financial Metrics | FY2024 Actual | FY2025 Actual | FY2026 Guidance (Prov.) |
|---|---|---|---|
| Total Revenue | Approx. $6.127B | Approx. $7.054B | Approx. $9.61B–$9.74B |
| Ansys Revenue Contribution | Under Review (0) | Approx. $756.6M | Approx. $2.9B–$2.98B |
| Non-GAAP Operating Margin | Approx. 38.5% | Approx. 39.8% | Approx. 41.5% |
| Backlog | Approx. $8.6B | Approx. $11.4B | Expected to exceed $12.0B |
| Non-GAAP EPS | Approx. $13.20 | Approx. $14.92 | $15.80–$16.20 projected |
Synopsys' business model maintains strong downside earnings stability compared to typical hardware semiconductor manufacturers, with multi-year contracts (Total Contract Value / TCV) accounting for over 80% of revenue.
However, the short-term increase in net leverage—driven by over $19 billion in cash outlays and corporate bond issuances to fund the Ansys acquisition—remains a key balance-sheet variable to monitor.
Valuation
As of October 5, 2026, Synopsys (SNPS) intraday trading is categorized as "Market Price Pending (based on latest verified data)," with its 12-month forward price-to-earnings (Forward P/E) multiple trading around 34x to 37x.
It trades at a slight discount to Cadence (CDNS), which sits at roughly 38x to 40x forward P/E, reflecting the debt burden and post-merger integration (PMI) risks associated with the transaction.
From a macroeconomic perspective, software equities trading above 30x multiples remain sensitive to fluctuations in the 10-year U.S. Treasury yield (US10Y).
During periods of U.S. Dollar Index (DXY) strength and rising volatility (VIX), short-term multiple compression has recurred within the Nasdaq 100.
Nonetheless, if consolidated revenue reaches $11.1 billion–$11.2 billion by FY2027 and free cash flow (FCF) margins normalize to the mid-30% range, current multiples may be viewed not merely as a premium, but as fair value for its expanded market positioning.
Compared to general software peers in the S&P 500, Synopsys benefits from lower cyclicality and direct exposure to fabless R&D spending, providing structural support to its valuation floor.
[Image: /stdaily/uploads/202610/gen_6ac2e8c386a3e0.66642348.png]
Expert and Institutional Analysis
Major Wall Street investment banks view Synopsys' acquisition of Ansys as the most strategic transaction in the systems technology sector since Broadcom’s acquisition of VMware in 2023.
In early October 2026, Bank of America (BofA) raised its price target, noting that the company's pro-forma EPS growth trajectory for FY2027–FY2028 materially exceeds consensus expectations.
Morgan Stanley noted that as long as hyperscalers pursue proprietary custom ASIC developments, EDA software retains its essential "picks and shovels" positioning.
Particularly in 3D packaging where HBM and logic chips are vertically stacked, thermal dissipation and electromagnetic interference control determine production viability, positioning the combined Synopsys-Ansys software stack with a competitive advantage.
Conversely, some technical research firms caution that required divestitures in optical and RTL low-power tools could temporarily delay near-term product integration synergies.
Simultaneously, Cadence's expanding partnerships with Dassault Systèmes and Siemens represent an evolving competitive landscape that warrants ongoing observation.
Risk Factors
The primary underlying risk is a potential scale-back in chip development projects if Big Tech faces delayed returns on AI CapEx investments.
Should hyperscalers trim custom silicon budgets due to slower monetization of Large Language Models (LLMs), long-term EDA renewals and seat expansions could moderate.
A second risk involves the pace of deleveraging in a prolonged higher-rate environment.
Because the transaction was completed using substantial leverage, a significant portion of free cash flow over the next two to three years must be directed toward debt reduction, temporarily limiting capital return initiatives such as share repurchases.
A third factor is persistent uncertainty surrounding semiconductor export controls on China.
While conditional approval was secured from China's SAMR, potential additions to U.S. Department of Commerce restrictions covering advanced nodes and Gate-All-Around (GAA) design software could generate volatility in China-derived revenues, which historically account for the low-to-mid teens percentage of total sales.
Investment Perspective Summary
Synopsys operates as an upstream infrastructure asset, insulated from direct fabrication competition while supplying foundational design tools required for technology hardware advances.
In the near term, quarterly margin volatility may emerge due to Ansys integration expenses and balance sheet deleveraging.
Consequently, rather than chasing short-term momentum, viewing valuation pullbacks triggered by Treasury yield spikes or Nasdaq Fear & Greed contractions as dollar-cost averaging opportunities offers a rational approach.
For investors wary of the high beta inherent in the SOX index, Synopsys—supported by an Annual Recurring Revenue (ARR) profile exceeding 80%—can serve as a structural portfolio hedge.
Ultimately, the key variable rests on how substantially this unified physics simulation and chip design platform enhances development productivity for primary customers like Nvidia, Apple, and Broadcom.
Investors should closely monitor the trajectory of second-half 2026 earnings, when operational synergies are expected to translate into reported margin improvements.
Investor Checkpoint Q&A
Q1. Why is the combination of Synopsys and Ansys critical for semiconductor design?
Historically, internal circuit design (EDA) and external physical simulations (thermal, fluid dynamics, stress testing) operated as distinct workflows.
However, in sub-2nm processes and 3D chiplet architectures, internal heat and electromagnetic interference directly cause computational errors and shorten lifespan. Physics simulations must run concurrently from the earliest stages of schematic design to safeguard target yields.
Q2. Will the asset divestitures mandated by antitrust regulators hurt performance?
The divested optical solutions and RTL power analysis software represent approximately $110 million in annual revenue, which accounts for around 1% of total consolidated revenue.
Because critical core assets—including the 3D-IC multiphysics analysis engine and primary digital logic tools—remain fully intact, the strategic impact remains minimal.
Q3. Are tech software stocks resilient with the Nasdaq Fear & Greed Index at 31.2?
When market sentiment enters "Fear," growth equities trading at elevated multiples (P/E above 30x) typically face broad multiple compression.
However, supported by a backlog exceeding $11.4 billion and multi-year licensing commitments, Synopsys maintains low downside earnings volatility, providing stronger mid- to long-term recovery resilience than cyclical equipment manufacturers.
Q4. What does the "outcome-based pricing" announced at Investor Day entail?
Traditional software models charge fixed licensing fees per engineer seat.
Moving forward, the business is expanding into cloud-based structures where fees correlate directly with customer efficiency gains, such as design cycle acceleration via AI tools or successful physical chip tape-outs, sharing in client value creation.
Q5. What are the most immediate catalysts for investors to track?
First is the pace of quarterly debt reduction following the closing of the Ansys transaction; second is the preservation of its AI EDA market lead against Cadence.
Additionally, investors should monitor potential updates to U.S. EDA export controls on China and implementation schedules alongside next-generation 2nm mass production roadmaps across major foundries like TSMC.