Hello, this is Daily Stock.
[이미지: /stdaily/uploads/202610/gen_6ac045a4b11673.81096562.png]
Key Summary
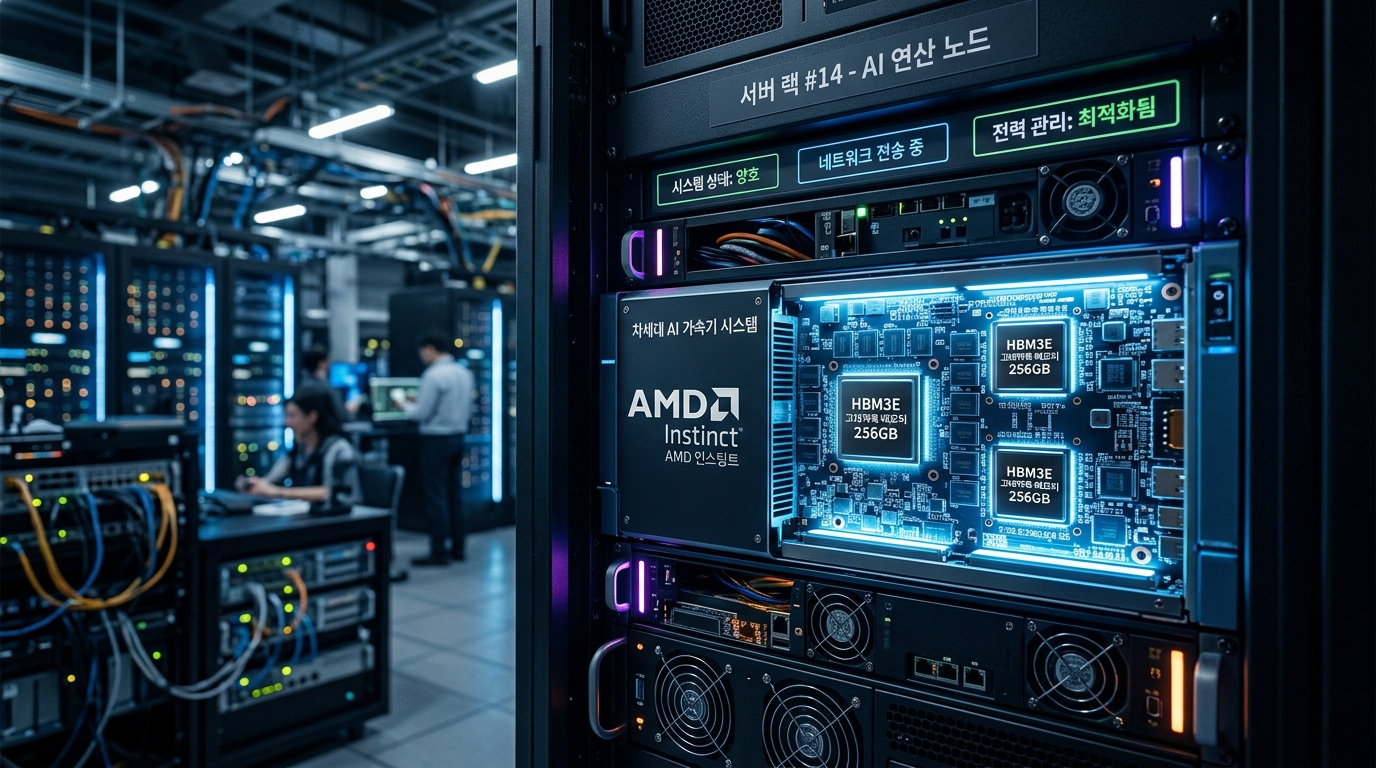
AMD is accelerating its push into the artificial intelligence (AI) data center market with the full deployment of the Instinct MI325X accelerator, equipped with 256GB of HBM3E memory.
Amid an AI accelerator ecosystem dominated by Nvidia, AMD's strategy is to capture second-source demand from hyperscalers by highlighting competitive cost-efficiency in large language model (LLM) inference and the open compatibility of its ROCm software.
From a macroeconomic perspective, fluctuations in the 10-year US Treasury yield (US10Y) and the sustainability of Big Tech capital expenditures (CapEx) serve as key variables dictating whether AMD can sustain its valuation multiple.
Current Market Situation
In the global AI data center market, Nvidia's dominant position intersects with growing demand from Big Tech firms seeking to reduce Total Cost of Ownership (TCO) and diversify supply chains.
Based on the CDNA 3 architecture, AMD's Instinct MI325X leverages an ultra-high memory bandwidth of 6.0 TB/s and a 256GB HBM3E capacity to expand its footprint in large model inference.
As major cloud service providers (CSPs) like Microsoft and Meta pursue commercial accelerator vendor diversification alongside their proprietary custom silicon initiatives, the potential for AMD's penetration to rise is being actively evaluated.
| Category | Key Metrics & Details |
|---|---|
| Analyzed Stock | AMD (Advanced Micro Devices, Inc.) |
| Stock Price Status | Intraday quote unconfirmed (based on latest verified data) |
| Core Product Specs | Instinct MI325X (256GB HBM3E, 6.0 TB/s bandwidth, CDNA 3 architecture) |
| Primary Competing Models | Nvidia H200 and Blackwell B200 series |
| Market Benchmarks (2026-10-03) | KOSPI: 7,003.74 / KOSDAQ: 893.29 / NASDAQ: 27,190.86 / USD/KRW: 1,347.00 |
| Daily Stock Fear & Greed Index | NASDAQ: Currently Fear (31.2) [1 week ago: 36.9, 1 month ago: 46.1] |
[이미지: /stdaily/uploads/202610/gen_6ac045af2fb702.37430738.png]
Financial Analysis
AMD's Data Center segment has established itself as the primary engine of overall corporate performance, driven by steady market share gains in EPYC server CPUs and rising shipments of Instinct GPUs.
Alongside a recovery in the Client PC segment, data center revenue now accounts for more than half of total company revenue, driving an overall improvement in gross margin.
However, packaging costs for high-bandwidth memory (HBM3E) and expenses related to leading-edge foundry nodes could act as headwind factors on early mass-production margins.
With R&D expenditures simultaneously climbing to strengthen next-generation rack-scale platforms and system packaging capabilities, the resilience of operating cash flow remains a key focal point across quarterly earnings releases.
Valuation
With the NASDAQ Fear & Greed Index lingering in the "Fear" zone at 31.2, the semiconductor and AI hardware value chain remains exposed to elevated volatility.
Compared to the Philadelphia Semiconductor Index (SOX) and the NASDAQ-100, AMD's forward price-to-earnings (Forward P/E) multiple is being sensitively repriced according to the execution speed of its data center GPU guidance.
As the US 10-year Treasury yield (US10Y) continues to fluctuate, discount rate pressure on high-multiple growth stocks persists.
For the valuation gap with Nvidia to narrow, actual cloud infrastructure utilization rates and the scale of recurring orders must be proven beyond mere product rollouts.
Expert & Institutional Analysis
Major Wall Street institutional investors note that the launch of the MI325X aligns with hyperscalers' desire to counterbalance Nvidia's monopolistic pricing power.
Some institutions assess that the maturity of AMD's ROCm software ecosystem has significantly improved compared to the past, lowering switching costs across key frameworks such as PyTorch.
Conversely, other analysts urge caution, arguing that gaining market share will not be easy as Nvidia ramps up full-scale supply of its next-generation architecture and full-stack networking anchored by the CUDA ecosystem in the second half.
Ultimately, the degree to which budget allocations for AMD tangibly increase within hyperscaler CapEx execution plans will likely determine institutional flow directions.
[이미지: /stdaily/uploads/202610/gen_6ac045b79416d7.69556805.png]
Risk Factors
The primary risk is the potential reduction in Big Tech CapEx if AI infrastructure investments experience delays in monetization.
Should the conversion of AI services into actual revenue lag, hyperscalers may prioritize postponing deployment schedules for secondary accelerator vendors.
Additionally, potential bottlenecks in advanced foundry packaging (CoWoS) and HBM3E supply chains could disrupt timely fulfillment.
Macroeconomic shocks, including heightened volatility in the US Dollar Index (DXY) and spikes in the Cboe Volatility Index (VIX), also serve as factors that could limit valuation rerating.
Investment Takeaway
The scenario for AMD expanding its data center market share rests on the competitive advantages of the high-memory MI325X and customer diversification trends pursuing cost efficiencies.
Amid a constrained market environment where the NASDAQ Fear & Greed Index reads 31.2, quarterly data center revenue growth rates and upward revisions to GPU guidance must be tracked closely.
Rather than chasing short-term price momentum, a patient approach is required—one that monitors the expanding share of inference workloads within medium- to long-term AI deployments and the maturation of open software ecosystems.
It is sensible to establish allocation adjustment strategies across various scenarios, keeping them closely aligned with interest rate paths and Big Tech CapEx spending trajectories.
Frequently Asked Questions
Q1. What is the core hardware strength of the AMD Instinct MI325X?
A1. Its flagship advantage lies in supporting 256GB of HBM3E memory and 6.0 TB/s of bandwidth, allowing a single accelerator to efficiently process massive parameter sets when running large language models (LLMs).
Q2. What is the largest barrier to entry in competing with Nvidia?
A2. The strong lock-in effect of Nvidia's CUDA software ecosystem and its rack-scale full-stack solutions remains the most formidable barrier to entry.
Q3. Why are hyperscalers looking to adopt AMD accelerators?
A3. The primary motivation is supply chain diversification, aiming to lower reliance on a single vendor and reduce the Total Cost of Ownership (TCO) of building data center infrastructure.
Q4. Which macroeconomic indicators require the closest attention?
A4. Key metrics include the trajectory of the 10-year US Treasury yield (US10Y), the US Dollar Index (DXY), and quarterly revisions to Big Tech CapEx guidance.
Q5. How is current market sentiment affecting AMD's stock price?
A5. With the Daily Stock Fear & Greed Index indicating a "Fear" level of 31.2 for the NASDAQ, investors need to remain mindful of short-term volatility until clear earnings visibility is established.