Hello, this is the KOSPI Market Analyst at Daily Stock.
[이미지: /stdaily/uploads/202609/gen_6ab3791c04f4f1.15829897.png]
Executive Summary
Hanwha Aerospace is solidifying its position as a core defense supplier along NATO's Eastern European flank, driven by a landmark contract with Romania valued at approximately KRW 1.3828 trillion for K9 self-propelled howitzers and K10 ammunition resupply vehicles.
As of the Korean market close on September 23, 2026, the KOSPI closed at 7,080.92, while the KOSDAQ stood at 844.48, with the USD/KRW exchange rate recorded at 1,359.60 won.
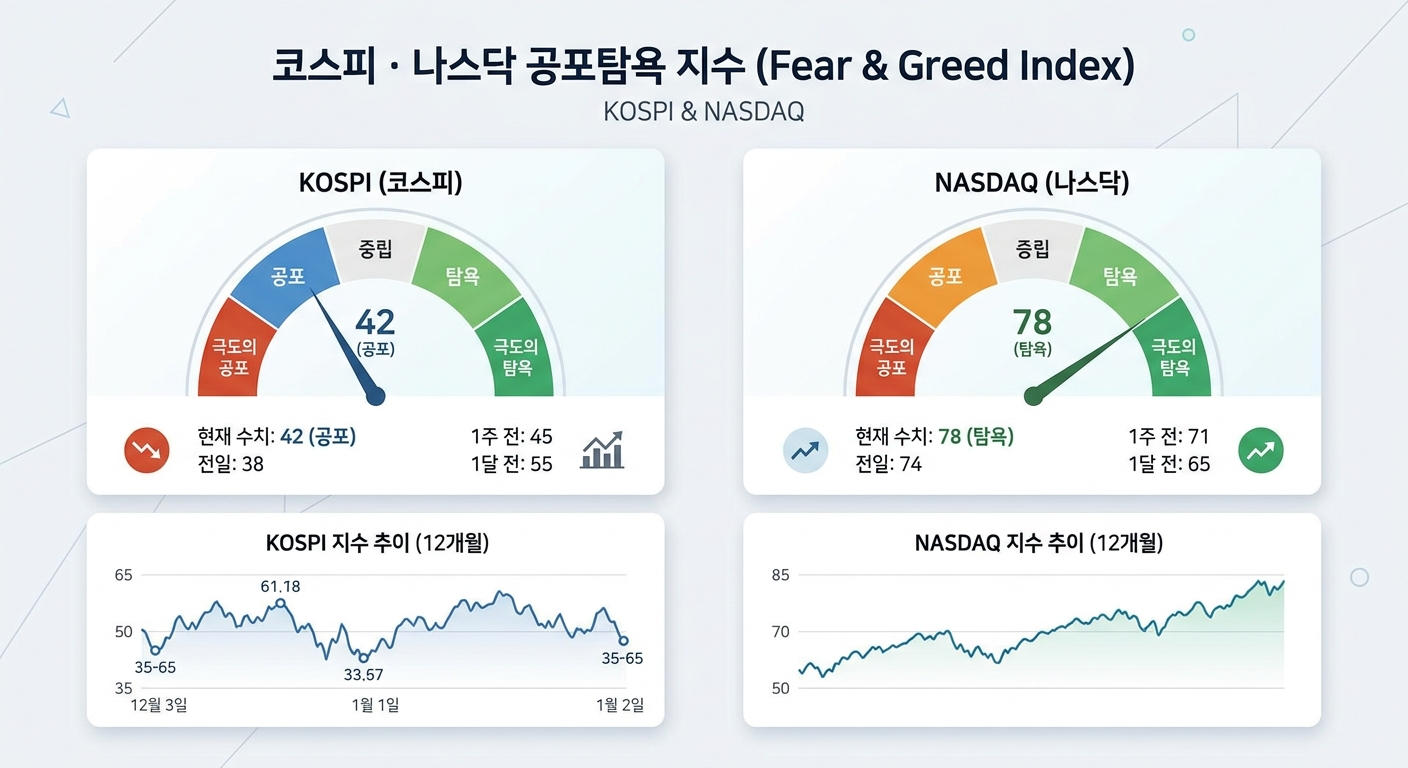
According to our proprietary Fear & Greed Index, the KOSPI has recovered to the Neutral zone (55.3) from Fear (29.2) a week ago, whereas the Nasdaq remains in the Fear zone (35.2), signaling persistent external volatility.
Coupled with strong export delivery volumes in the land systems division and structural improvements at key subsidiaries like Hanwha Ocean, scenarios point to robust top-line performance and strong earnings generation into the third quarter.
Current Market Situation
The contract signed with the Romanian Ministry of National Defence encompasses 54 units of the K9 self-propelled howitzer, 36 units of the K10 ammunition resupply vehicle, and related ammunition packages, marking Romania's largest arms procurement project in the last seven years.
With this deal, the K9 cements its status as a global bestseller operated by 10 nations worldwide, including Romania, while talks regarding local co-production hubs are gathering momentum.
Across the broader KOSPI market, amid cyclical swings in large-cap semiconductor and automotive shares, the defense sector serves as a defensive cornerstone, retaining foreign capital inflows on the back of distinct earnings visibility.
While Hanwha Aerospace's price for the day remained listed as "unconfirmed for the session (based on latest verified data)" at the close, market confidence in its fundamentals backed by massive order backlogs remains exceptionally firm.
[이미지: /stdaily/uploads/202609/gen_6ab37927409439.82527778.png]
Financial Analysis
Hanwha Aerospace continues to generate robust cash flows each quarter, powered by rising land defense export deliveries and normalized operational profits across consolidated subsidiaries.
Alongside deliveries for Poland's first and second contracts, sequential executions in Egypt and Australia (Redback IFV) are contributing to simultaneous cost-ratio improvements and operating margin defense.
| Key Financial Metrics (Consolidated) | Preceding Comparable Trend | Q3 Trajectory & Key Forecast Points | Remarks & Variables |
|---|---|---|---|
| **Consolidated Revenue** | High-growth pace sustained | Potential stabilization in mid-KRW 6T | Tied to Poland delivery schedules |
| **Consolidated Operating Profit** | Led by land systems | Securing earnings base around KRW 850B | Impact of expanding high-margin exports |
| **Land Systems Operating Margin** | Mid-to-high 20% range | Solidly sustained around 26–27% | Delivery contributions from K9 and Chunmoo |
| **Order Backlog** | Over KRW 31T | Mid-to-long term backlog sustained in KRW 30T range | Pending follow-on contracts in Romania and the Middle East |
The USD/KRW exchange rate remaining elevated around the 1,359 won mark serves as a favorable financial tailwind, enhancing the KRW-converted profitability of overseas land defense shipments.
Valuation
Hanwha Aerospace has broken away from traditional heavy machinery and industrial multiples, trading instead at premium valuations aligned with global defense peers.
While core KOSPI 200 blue chips fluctuate around a P/E of roughly 10x amid concerns over global economic and trade slowdowns, the defense sector commands a relative valuation premium underpinned by multiple years of confirmed order backlogs.
Compared to global peers such as Lockheed Martin in the U.S. and Rheinmetall in Germany, Hanwha Aerospace maintains clear competitive edges in rapid delivery timelines, cost-competitiveness, and comprehensive localization packages.
However, as its post-spinoff transition into a pure defense and aerospace company has widened share price volatility, investors should periodically assess the reasonableness of PSR and EV/EBITDA multiples against realized earnings.
Institutional & Expert Perspectives
Brokerage analysts view the final Romanian K9 deal not merely as a one-off win, but as a gateway toward competing in Romania’s upcoming Infantry Fighting Vehicle (IFV) procurement program, estimated at around KRW 4 trillion.
Foreign institutional investors are using large-cap defense shares with proven cash-generation capabilities as core defensive holdings in their portfolios, despite the Bank of Korea’s benchmark interest rate freeze and ongoing won weakness.
Institutional research notes that while quarterly delivery schedules in land systems may cause temporary top-line fluctuations in Q3, the full-year trajectory of profit growth remains fully intact.
Product diversification, including the contract to supply 155mm modular artillery charges to Sweden and Cheongung-II launcher exports to Iraq, is also cited as justification for multi-year multiple expansion.
[이미지: /stdaily/uploads/202609/gen_6ab37933d308c1.23105882.png]
Risk Factors
Abrupt shifts in global geopolitical conditions or rapid developments in ceasefire negotiations could temporarily cool investor sentiment across the broader global defense sector.
Should macroeconomic shocks trigger sharp swings in the USD/KRW exchange rate, foreign exchange derivative valuations and settlement currency margins may experience short-term volatility.
Furthermore, growing demands for local overseas assembly facilities and technology transfers could require upfront capital expenditures (CAPEX) and increase fixed-cost burdens.
Beyond domestic export financing ceiling adjustments, long-term risks such as fiscal health and defense policy changes in procuring nations require close monitoring.
Investment Strategy
Hanwha Aerospace stands as a key bellwether that directly demonstrates South Korea's defense supply-chain capabilities amid global security shifts.
As the KOSPI tests stabilization around the 7,000 level, the company offers superior downside resistance compared to cyclical peers alongside backlog-driven growth visibility.
While staggered accumulation may be prudent during periods of valuation strain caused by short-term rallies, investors should evaluate the overseas revenue mix and operating cash flows detailed in the upcoming Q3 report.
Over the medium to long term, potential follow-on contracts in Romania and expanding project pipelines in the U.S. and Middle Eastern markets will serve as primary catalysts for further equity re-rating.
Investor Checkpoint Q&A
Q1. When will deliveries begin for the Romanian K9 export contract?
A1. According to the contract with the Romanian Ministry of National Defence, sequential deliveries and rollouts are scheduled to commence in 2027 through local industrial partnerships.
Q2. What is the key segment to monitor in the Q3 earnings results?
A2. The volume of K9 and Chunmoo deliveries destined for Poland within the land systems division, alongside sustained profitability and operational stabilization at subsidiary Hanwha Ocean, are the key metrics to track.
Q3. Is the current USD/KRW exchange rate (1,359.60 won) favorable for defense earnings?
A3. Yes. Because most overseas defense export contracts are settled in U.S. dollars, an elevated exchange rate boosts both KRW-converted revenues and operating margins.
Q4. What is the outlook for winning the Romanian IFV (Infantry Fighting Vehicle) program?
A4. The Redback benefits from component commonality with the K9 and K10, as well as proven credibility from its Australian contract; however, close attention must be paid to competition against European contenders like Germany's Rheinmetall.
Q5. What does the Daily Stock Fear & Greed Index showing KOSPI at 'Neutral (55.3)' and Nasdaq at 'Fear (35.2)' indicate?
A5. Domestic market sentiment is emerging from extreme fear, but persistent volatility in U.S. tech stocks suggests that a diversified strategy centered on large-cap backlog-driven shares with strong earnings visibility remains optimal.