Hello. This is Daily Stock, delivering precise insights into market trends and core corporate value.
[이미지: /stdaily/uploads/202609/gen_6ab2279ca7ad27.00225429.png]
Executive Summary
Kakao recently decided to officially shut down its standalone AI mate app 'Kanana' on October 15, just one year and five months after its launch.
This decision marks a strategic pivot rather than a failure—transitioning toward an "everyday AI centered on KakaoTalk" by embedding AI agents directly into South Korea’s national messenger app with 50 million users.
At the upcoming annual developer conference "if(kakao)2026," scheduled for October 13–14, Kakao is expected to showcase its enterprise-wide agentic AI roadmap alongside on-device AI features.
A key turning point for a stock rebound will be whether fundamental stability—strengthened through internal management discipline and affiliate restructuring during the first half—can translate into operational leverage across KakaoTalk's core advertising and commerce businesses in the second half.
Amid KOSPI supply-demand flows skewed toward traditional heavyweights such as semiconductors, automotive, and financial holding companies, investors should closely examine the potential for a valuation rerating in neglected large-cap platform stocks.
Market Context
On September 22, 2026, domestic markets closed with the KOSPI at 7,017.91 and KOSDAQ at 834.38, while the KRW/USD exchange rate stood at 1,360.50 won.
According to the Daily Stock proprietary Fear & Greed Index, the KOSPI is currently Neutral (52), recovering from Fear (25) a week ago. However, the Nasdaq remains in Fear (33.7), indicating that global risk appetite is still cautious.
Kakao (035720) shares have been consolidating near their bottom in the low-to-mid 30,000 won range (pre-market reference price around 33,200 won), remaining trapped in a box range near 52-week lows.
Market participants are focused on "if(kakao)26," to be held October 13–14 at the Kakao AI Campus in Yongin.
[이미지: /stdaily/uploads/202609/gen_6ab227a77bc1c9.92931257.png]
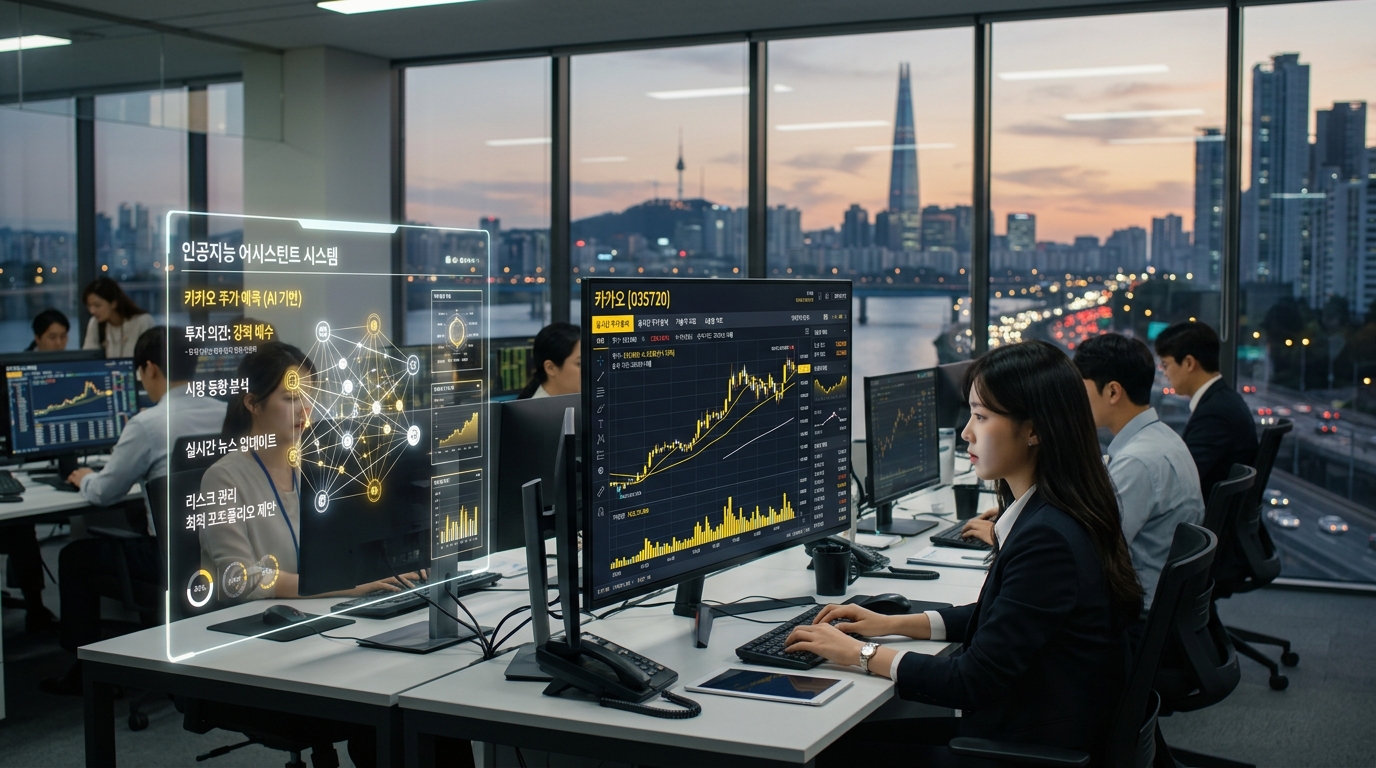
The event will unveil blueprints for "Kanana in KakaoTalk" and agentic AI, acknowledging the limitations of the standalone app and deeply integrating the technology directly into KakaoTalk.
Amid macroeconomic pressure from a 1,360 won exchange rate and foreign institutional buying concentrating on KOSPI semiconductor and financial names, attention is turning to whether Kakao's concrete AI deployment strategy can act as a catalyst for new capital inflows following its prolonged correction.
Financial Analysis
Kakao is steadily improving its operational structure through disciplined management centered on divestitures of non-core affiliates and stringent cost controls.
Even during the historically slow advertising season in the first half, resilient performance in Talk Biz (messaging, Bizboard) and commerce enabled the company to sustain double-digit operating profit growth.
| Metric | FY2024 (Reported) | FY2025 (Reported) | FY2026 (Consensus Estimate) | Key Drivers |
|---|---|---|---|---|
| **Consolidated Revenue** | KRW 7.557 trillion | KRW 8.151 trillion | KRW 8.600T – 8.800 trillion | Talk Biz recovery & AI-integrated commerce growth |
| **Consolidated Operating Profit** | Low KRW 400B range | Mid KRW 700B range (KRW ~704B) | KRW 780B – 820 billion | Infrastructure cost optimization & expansion of high-margin ad inventory |
| **Operating Margin (OPM)** | 6.1% | 8.6% | 9.0% – 9.5% | Affiliate portfolio rebalancing & marketing efficiency |
| **Net Cash & Liquidity** | Healthy | Improving trend | Stable free cash flow generation | Cash recovery phase following CapEx deployment |
Large early-stage research and development expenses incurred following the absorption of Kakao Brain are steadily coming under control.
While marketing expenses increased year-over-year in the second quarter amid AI feature upgrades and service transitions, the core Talk Biz division reliably served as a steady cash cow.
However, a time lag remains before AI agent services translate into tangible cash-generating mechanisms, such as paid subscription models or transaction commissions.
Valuation
Kakao's 12-month forward price-to-earnings (P/E) ratio currently sits at approximately 20–22x, meaning the valuation premium of over 40–50x seen during its past platform expansion era has fully cleared out.
Compared to KOSPI 200 large-caps in semiconductors or autos trading at low multiples of 6–10x, some market participants argue that the valuation multiple still carries a premium.
However, it is worth noting that global big-tech platforms justify multiples of 25–30x or higher through on-device AI and search agents.
If Kanana AI demonstrates effective monetization on KakaoTalk’s high-traffic surface—evidenced by higher effective cost per mille (eCPM) and increased dwell time—room for valuation expansion could open up.
Much like domestic peer NAVER secured earnings stability via AI Briefing, Kakao is likely to experience multiple rerating once clear operational milestones from its AI agent are confirmed.
Expert & Institutional Analysis
Domestic brokerages view the termination of the standalone Kanana app and the refocusing of AI into KakaoTalk as a "realistic and rational choice."
[이미지: /stdaily/uploads/202609/gen_6ab227b2b1e587.58061300.png]
A standalone app faced difficulties establishing user lock-in against established global frontier models such as OpenAI's ChatGPT.
Conversely, an agentic AI operating directly inside KakaoTalk—capable of parsing conversational context to schedule appointments, recommend locations, and process shopping checkouts—represents a unique competitive moat exclusive to Kakao.
Major domestic securities firms maintain "Buy" ratings on Kakao, with target prices ranging from the low 40,000 won range to around 55,000 won.
Global investment banks (including JPMorgan and Nomura) also view the shift positively, commending Kakao for pivoting away from developing capital-intensive proprietary frontier models toward small language model (SLM) on-device optimization and external collaborations (such as partnerships with ChatGPT).
Risk Factors
The primary risk to monitor is a potential delay in the monetization of AI services.
If increases in user dwell time fail to generate higher Bizboard ad pricing or expand Kakao Gift gross merchandise volume (GMV), the initiative could result in an added cost burden.
A second factor is macro volatility and exchange rate pressure.
If the KRW/USD exchange rate rises significantly beyond 1,360 won or interest rate cuts by the US Federal Reserve and Bank of Korea are delayed, platform growth stocks could face broader valuation headwinds.
A third consideration includes lingering governance and legal risks, alongside internal labor friction.
Persistent friction surrounding job security and compensation allocation within restructured subsidiaries could weaken talent recruitment in AI and impede aggressive execution in new business segments.
Investment Takeaway
Having moved past the peak of its structural growing pains, Kakao has clearly shifted its strategic focus toward pragmatic AI deployment.
The upcoming "if(kakao)26" on October 13–14 will serve as a pivotal milestone to evaluate the technological maturity and monetization clarity of Kakao's AI ecosystem.
Rather than aggressively chasing short-term price momentum, an accumulation strategy keyed to verifying Talk Biz core earnings stability and integration metrics of the Kanana agent within KakaoTalk appears prudent.
With foreign futures trading having the potential to drive broader KOSPI volatility around the 1,360 won FX level, disciplined positioning should remain anchored strictly to valuation floors and verified financial metrics.
Investment Checklist
- [ ] **Review Key Announcements at 'if(kakao)26' (October)**: Official features for Kanana in KakaoTalk and the agent ecosystem roadmap
- [ ] **Monitor KakaoTalk Daily Average Dwell Time**: Growth rates across Friends and Chat tabs post on-device AI integration
- [ ] **Track Q3 Talk Biz Revenue Growth**: Sustainability of double-digit expansion across messaging ads and Gift GMV
- [ ] **Analyze FX and Liquidity Dynamics**: Stabilization around 1,360 KRW/USD and foreign/institutional net buying trends in KOSPI platform stocks
- [ ] **Assess Non-Core Asset Streamlining**: Progress in subsidiary portfolio rebalancing to help establish consolidated margins in the 10% range