Hello, this is Daily Stock, closely tracking the global tech value chain and macroeconomic trends.
[이미지: /stdaily/uploads/202609/gen_6ab073a036b220.51867110.png]
Key Takeaways
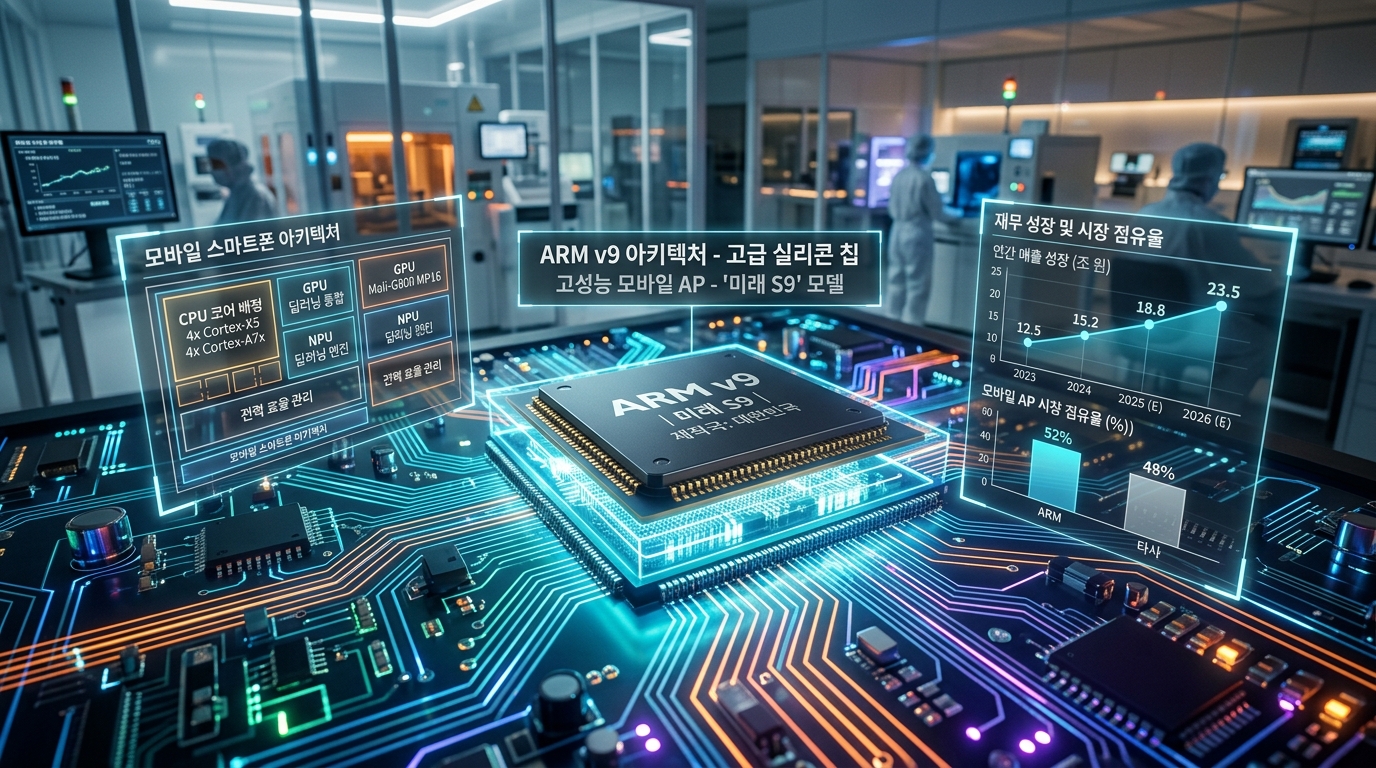
Arm Holdings' (ARM) core earnings engine is rapidly pivoting from the legacy v8 architecture to the higher-margin v9 architecture.
The v9 architecture commands roughly double the royalty rate of the previous generation, serving as a pivotal driver expanding revenue per chip (ASP) even amidst stagnant mobile chipset shipment growth.
As global smartphone manufacturers accelerate the adoption of on-device AI chipsets, v9 penetration in the premium smartphone market is well exceeding 50%.
However, heavy valuation multiples in the Nasdaq market and sensitivity to US 10-year Treasury yield (US10Y) volatility remain key factors driving share price fluctuations.
Market Overview
As of intraday trading on September 21, 2026 (tentative), the Nasdaq Composite stands at 26,522.55. In the domestic South Korean market, the KOSPI is trading at 6,894.23, the KOSDAQ at 827.12, and the USD/KRW exchange rate is at 1,387.50 KRW.
According to Daily Stock's proprietary Fear & Greed Index, the Nasdaq is currently in the Fear territory (29.1), down from Fear (32.7) a week ago, reflecting notably dampened investor sentiment compared to Neutral (54.6) a month ago and Greed (66.5) three months ago.
The KOSPI Fear & Greed Index is currently Neutral (40.9), rebounding from Fear (28.2) a week ago, yet cautious sentiment remains pervasive.
Arm Holdings' share price remains unconfirmed for the session (based on the latest verified figures), but its royalty resilience is being tested amid recent semiconductor index corrections and market scrutiny over Big Tech CAPEX efficiency.
With on-device AI demand entering full swing, major fabless customers such as MediaTek, Qualcomm, and Apple are uniformly adopting v9-based designs as standard.
This generational shift underpins ARM's ability to sustain double-digit royalty revenue growth even while global smartphone shipment growth lingers in the low single digits.
[이미지: /stdaily/uploads/202609/gen_6ab073ac8a4940.64460589.png]
Financial Analysis
ARM's revenue model consists of two pillars: License revenue, which acts as a leading indicator, and Royalty revenue, which scales in proportion to chip mass production.
Recent quarterly earnings show that the proportion of v9 architecture within total royalty revenue has surpassed 30% and is climbing steeply toward the 40% mark.
| Category | Armv8 Architecture | Armv9 Architecture | Compute Sub-Systems (CSS) |
|---|---|---|---|
| Average Royalty Rate (% of Chip ASP) | Approx. 1.5% – 2.5% | Approx. 4.0% – 5.0% | Up to 8.0% – 10.0% |
| Mobile Flagship Penetration | Gradually declining (legacy chips) | Over 70% (premium segment) | Early adoption expanding |
| Data Center Adoption Status | General-purpose cloud CPU instances | Next-generation Neoverse focus | Hyperscaler custom silicon |
| Primary Revenue Contribution | Stable cash cow (volume-based) | Royalty growth acceleration engine | Premium for reducing client time-to-market |
As v9 adoption surges in the mobile application processor (AP) market, the dollar amount ARM collects per smartphone shipment is seeing a step-function increase.
In addition, expanding shipments of Compute Sub-Systems (CSS)—turnkey IP design packages—are driving qualitative improvements in average take rates.
Valuation
ARM operates as a pure-play intellectual property (IP) provider rather than a traditional semiconductor fabricator, commanding gross margins exceeding 90%.
Consequently, the market has historically awarded the company price-to-earnings (P/E) and EV/Sales multiples far superior to those of conventional hardware chipmakers.
However, characteristic of growth stocks with high forward P/E ratios, ARM is exceedingly sensitive to the trajectory of the US 10-year Treasury yield (US10Y) and the US Dollar Index (DXY).
During periods of correction in the Philadelphia Semiconductor Index (SOX) and the Nasdaq 100, the risk of multiple contraction for richly valued growth stocks frequently surfaces.
Whether unit price increases from expanding v9 penetration can secure high growth over the next 2 to 3 years remains central to justifying this premium.
The market is rigorously reassessing ARM's free cash flow (FCF) generation capabilities for the fiscal years when v9 royalty share is projected to exceed half of the total.
Wall Street & Institutional Analysis
Major Wall Street investment banks are highlighting ARM's monopolistic IP ecosystem dominance despite the decelerating smartphone hardware cycle.
Firms such as Bernstein and TD Cowen view ARM positively as it expands beyond mobile chip designs into data center Neoverse lineups and next-generation AI accelerator processors.
Conversely, some institutions, including Morgan Stanley and Bank of America, maintain a neutral stance, citing near-term mobile shipment slowdowns and limited upside from current elevated valuations.
In particular, the potential market encroachment by the open-source RISC-V camp in low-to-mid segments and Big Tech's efforts to circumvent proprietary architectures are cited as long-term risks.
Institutional consensus ultimately hinges on whether ASP expansion driven by v9 adoption can sufficiently offset sluggish end-device shipments.
Most analysts agree that ARM's design share remains robust at the intersection where Big Tech AI infrastructure CAPEX flows into server CPUs and edge AI devices.
[이미지: /stdaily/uploads/202609/gen_6ab073b66fcaa3.29172053.png]
Risk Factors
The most immediate near-term risk is declining mobile device shipments caused by lengthening global smartphone replacement cycles.
Even if per-chip royalty rates double through v9 adoption, a sharp contraction in end-product unit sales will inevitably constrain overall royalty revenue growth.
A second risk is the macroeconomic environment and concerns over diminishing return on investment (ROI) from Big Tech CAPEX.
With the market's Fear & Greed Index lingering in the Fear zone (29.1), any sudden spike in the Volatility Index (VIX) could intensify passive capital outflows from high-multiple tech names.
A third factor is the long-term rise of the open-source RISC-V alliance and customers' attempts to diversify licensing leverage.
The trajectory of licensing disputes and contract renegotiations with major partners, including Qualcomm, also remains a variable capable of impacting mid-to-long-term margin structures.
Investment Outlook
Evaluating ARM requires looking beyond simple smartphone unit volumes to focus fundamentally on the 'royalty rate mix improvement' generated per chip.
With v9-based complex neural processing unit (NPU) integration becoming essential for on-device AI functionality, ARM's pricing power has grown even firmer.
In the near term, investors should closely monitor multiple adjustments amid the macro rate environment and subdued sentiment in the Nasdaq.
Over the mid-to-long term, the key compass will be whether ARM can leverage its mobile v9 dominance to accelerate CSS penetration into data center and automotive markets.
Frequently Asked Questions
Q1. How does ARM's v9 architecture differ specifically from v8 in terms of royalties?
A1. The v9 architecture substantially bolsters on-device AI computing and security features. It commands royalty rates around 4% to 5% of chip average selling price (ASP)—approximately double the 1.5% to 2.5% rate seen with the legacy v8 architecture.
Q2. Why is v9 penetration rising so rapidly in premium smartphones?
A2. Running generative AI models locally on smartphones requires advanced vector processing (SVE2) and NPU efficiency. Because v9 natively standardizes these capabilities, the latest flagship chipsets inevitably adopt the v9 architecture.
Q3. Can ARM's financial results grow even if smartphone shipments stagnate?
A3. Yes. Even if total smartphone unit shipments remain flat, the transition from legacy architectures to higher-rate v9 chips increases royalty revenue per device, enabling overall royalty top-line growth.
Q4. How do Compute Sub-Systems (CSS) contribute to ARM's performance?
A4. Instead of providing individual core schematics, CSS offers pre-integrated, pre-verified subsystem packages encompassing memory interfaces and caches. This shortens customer development timelines while enabling ARM to capture significantly higher royalty rates of up to 8% to 10% of chip ASP.
Q5. What is the primary impact of the current macroeconomic environment on ARM's stock price?
A5. As a high-multiple tech stock trading on a high-growth premium, ARM faces direct valuation discount pressure when US 10-year Treasury yields (US10Y) rise or broader market risk aversion escalates (rising VIX).