Hello, this is the Daily Stock professional writing team, providing precise insights into macroeconomic trends and corporate earnings fundamentals.
[Image: /stdaily/uploads/202609/gen_6aaa3eb474c841.24339805.png]
Executive Summary
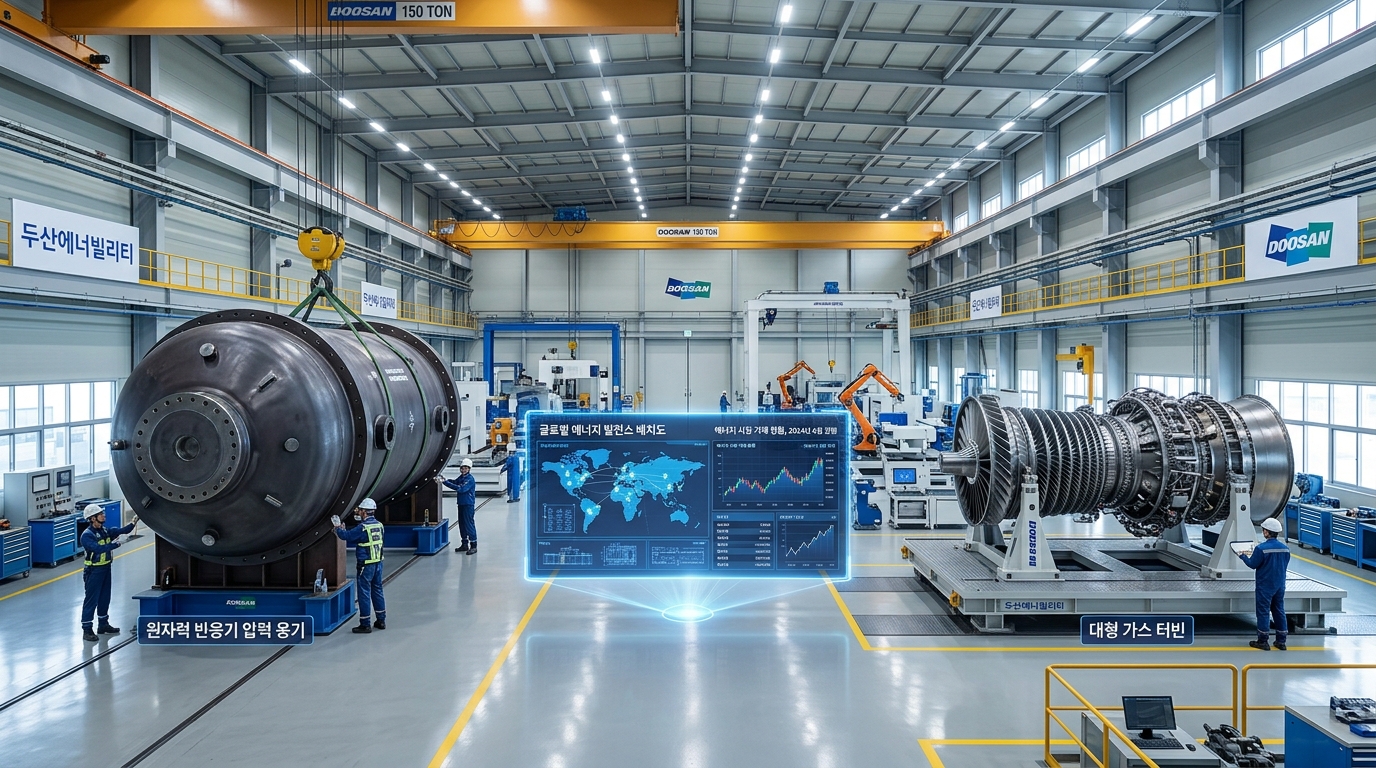
Doosan Enerbility is establishing a solid bridgehead for European market expansion as the final contract execution track for the Czech Dukovany Units 5 and 6 new nuclear power plant project settles into place.
Its independently developed 380MW-class extra-large gas turbine has secured consecutive orders to supply power for North American artificial intelligence (AI) data centers, rounding out a balanced portfolio spanning baseload and peak load power.
Amid a high exchange rate environment of 1,368.20 KRW/USD and a defensive market backdrop reflected by the KOSPI Fear & Greed Index at 29.2 (Fear) as of September 16, 2026, the valuation differentiation potential of high-value-added plant exporters stands out.
Current Situation Summary
On September 16, 2026, the domestic stock market closed with the KOSPI index at 6,717.97 and the KOSDAQ index at 815.98.
Looking at the proprietary Daily Stock Fear & Greed Index, the KOSPI is currently hovering in the Fear (29.2) zone.
This marks a sharp cooldown from Neutral (50.2) a week earlier and demonstrates deepening risk-aversion sentiment compared to Fear (38.3) one month ago and Neutral (52.4) three months ago.
The Nasdaq Fear & Greed Index has likewise dropped into Fear (28.5), indicating that volatility wariness is simultaneously affecting global asset markets.
The KRW/USD exchange rate stood at 1,368.20 KRW, maintaining upward pressure on the dollar and sensitively steering the spot and futures trading flows of foreign investors.
In the Korean large-cap market, semiconductors, automobiles, and financials are defending the downside, while liquidity is visibly concentrating into energy infrastructure and power plant sectors.
While intraday prices for Doosan Enerbility remained unconfirmed on the day (the most recently verified value placed the prior day's close in the mid-70,000 KRW range), momentum surrounding the finalization of the Czech nuclear contract and alignment with U.S. investment plays a central supporting role for investor flows.
Visibility for the Czech Dukovany Units 5 and 6 project improved significantly following Team Korea's selection as preferred bidder, marked by sequential contract negotiations and supply agreements for turbines and generators (valued at roughly KRW 320 billion) via local subsidiary Doosan Skoda Power.
Concurrently, as U.S. investment plans (LNG combined-cycle power and large-scale nuclear plants) materialize through platforms like the Korea-U.S. diplomatic talks in Washington, the potential for additional gas turbine deliveries across the United States has surfaced as a strong catalyst.
[Image: /stdaily/uploads/202609/gen_6aaa3ec0f19a21.41343352.png]
Financial Analysis
Doosan Enerbility's earnings structure has transitioned from its historical reliance on coal-fired generation and generic EPC into high-margin equipment manufacturing centered on high-value nuclear primary equipment and proprietary gas turbines.
For the first half of 2026, consolidated operating profit reached KRW 547.8 billion, representing year-on-year growth of more than 32%.
Preliminary consolidated results for Q2 posted revenue of KRW 4.7248 trillion and operating profit around KRW 314.2 billion, maintaining a stable trajectory of profitability.
Excluding subsidiaries, Enerbility's standalone core operations also achieved Q2 operating profit of around KRW 154.4 billion, verifying an improvement in core fundamentals.
The Enerbility division's order backlog exceeded KRW 26 trillion; if main-stage construction recognition for the Czech nuclear project and additional North American gas turbine orders are factored in for the second half, the company has room to exceed its full-year order target.
| Division | 1H 2026 Cumulative (Consolidated) | Q2 2026 Preliminary (Consolidated) | Enerbility Standalone (Q2) |
|---|---|---|---|
| Revenue | Approx. KRW 9.3900 trillion | KRW 4.7248 trillion | Exceeding approx. KRW 2 trillion |
| Operating Profit | KRW 547.8 billion | KRW 314.2 billion | KRW 154.4 billion |
| Order Backlog | KRW 26.3509 trillion | Maintained in the KRW 26 trillion range | Realignment toward key equipment |
| Key Order Sources | Nuclear primary equipment & North American gas turbines | Combined-cycle gas & steam turbines | Cumulative 23 large gas turbine units |
The heart of profitability lies in the combination of rising gas turbine ASPs and Long-Term Service Agreements (LTSA).
Gas turbines do not merely stop at unit sales; they secure high-margin parts replacement revenue for the ensuing 10 to 20 years, structurally driving up the quality of operating margins.
Valuation
In global markets, the valuations of power generation equipment and turbine specialists are undergoing explosive rerating.
Representative peer GE Vernova is commanding an EV/EBITDA multiple above 20x for gas turbines due to deepening power shortages.
In contrast, despite being one of the world's top five companies possessing proprietary large-scale gas turbine (380MW) technology, Doosan Enerbility remains relatively undervalued amid broader market fear.
Against the average of heavy industrial machinery and plant sectors in the KOSPI 200, this is a juncture where a premium combining its domestic nuclear primary equipment monopoly and gas turbine supply capabilities can be justified.
The elevated exchange rate of 1,368.20 KRW/USD serves as a factor maximizing KRW-denominated margins during overseas equipment exports, which feature a high share of dollar settlement.
The securities community projects that full-scale valuation reassessment will gain traction when the expansion of annual gas turbine manufacturing capacity coincides with ground-breaking on Dukovany Units 5 and 6.
Expert & Institutional Analysis
Domestic brokerage research centers look favorably on Doosan Enerbility's energy twin-track (large-scale nuclear + gas turbine) strategy.
IBK Securities adjusted its target price down to KRW 140,000 to reflect broad market valuation compressions, but maintained a 'Buy' rating citing persistent order momentum.
Major institutions including NH Investment & Securities (KRW 111,000), KB Securities (KRW 116,000), and Shinhan Securities (KRW 125,000) also maintained target prices above KRW 100,000, signaling medium- to long-term upside potential.
On foreign institutional flows, while some spot selling has surfaced around the 1,368.20 KRW/USD mark, selective accumulation by long-term funds focused on nuclear and power generation equipment remains evident.
From a macroeconomic perspective, Bank of Korea benchmark interest rate trends exert a neutral impact on capital expenditure (CAPEX) financing costs, whereas resilient trade surpluses in Korean plant and machinery exports provide positive reinforcement.
Experts expect that besides the Czech project, collaborative undertakings with Westinghouse and SMR orders centered around the U.S. Tennessee Valley Authority (TVA) will serve as additional catalysts in the second half.
Risk Factors
The global geopolitical climate and policy shifts among client nations ordering large-scale nuclear plants remain primary variables that could defer momentum.
Potential extensions of administrative review periods during the formal contract signing process and subsequent permitting stages for the Czech nuclear project could widen short-term share price volatility.
Furthermore, abrupt fluctuations in the KRW/USD exchange rate or concerns over a global economic slowdown could prompt project owners to delay Final Investment Decisions (FID).
Ongoing facility capital expenditures and the management of working capital burdens to build dedicated factories for large gas turbines and SMRs also warrant financial monitoring.
Investors must also account for possible pacing adjustments in clean energy transitions depending on policy fine-tuning before and after the U.S. presidential election.
Investment Perspective Summary
Doosan Enerbility is a rare global hybrid infrastructure player capturing both short-term peak load (gas turbine) and medium- to long-term baseload (nuclear and SMR) demand accelerated by the expansion of AI data centers.
When the KOSPI Fear & Greed Index lingers in the Fear zone at 29.2, a phased accumulation strategy focusing on order backlog quality improvements and cash flow turnarounds rather than short-term price elasticity is rational.
The official signing timeline for the Czech nuclear project and whether relay orders for gas and steam turbines dedicated to North American data centers continue will be the decisive benchmarks for an earnings level-up.
Investor Checkpoint Q&A
Q1. What is Doosan Enerbility's actual scope of supply in the Czech Dukovany Units 5 and 6 project?
A. Alongside key primary system equipment like reactors and steam generators, the company will deliver secondary system equipment—including steam turbines, generators, and turbine control systems—via its local subsidiary, Doosan Skoda Power.
Q2. What is the fundamental driver behind surging orders for gas and steam turbines in North America?
A. The rapid construction of AI data centers by Big Tech firms has heightened the need for dedicated, on-site power generation. Consequently, demand is surging for packages combining fast-to-deploy LNG combined-cycle gas turbines and waste-heat-recovery steam turbines.
Q3. Is the current exchange rate of 1,368.20 KRW/USD positive for corporate earnings?
A. Yes. Most of Doosan Enerbility's overseas equipment export contracts are settled in foreign currencies like USD, creating a favorable climate for top-line revenue and operating margins when converted into KRW.
Q4. What differentiates Doosan Enerbility from competitors like GE Vernova?
A. While GE Vernova is concentrated in gas turbines and wind power, Doosan Enerbility possesses a proprietary large gas turbine lineup while simultaneously maintaining manufacturing capacity as a large commercial nuclear primary component provider and SMR foundry.
Q5. What is the most critical second-half event for investors to watch?
A. Investors should closely monitor the official timeline for the final execution of the Dukovany contract with the Czech government and CEZ, alongside order disclosures for North American combined-cycle plants tied to bilateral investment discussions in Washington.