Hello, this is Daily Stock, delivering precise insights into daily market context and corporate fundamentals.
[Image: /stdaily/uploads/202610/gen_6ac891316e5735.26022764.png]
Executive Summary
HD Hyundai Heavy Industries is fully entering a delivery phase centered on high-value, eco-friendly vessels after having worked off most of its past low-priced order backlog.
In particular, construction progress on high-price gas carriers, including Very Large Ammonia Carriers (VLACs), is accelerating, fueling expectations of expanding operating profit margins in the fourth quarter.
Amid favorable foreign exchange conditions with the KRW/USD exchange rate around 1,342.30, the strengthening earnings power of major shipbuilding stocks is standing out as a key differentiator within the KOSPI market.
Current Market Situation
The domestic stock market showed mixed momentum, with the KOSPI closing at 6,625.93 and the KOSDAQ finishing at 892.27.
The KRW/USD exchange rate stood at 1,342.30 KRW, providing a favorable currency backdrop for export-driven heavy manufacturing industries in South Korea.
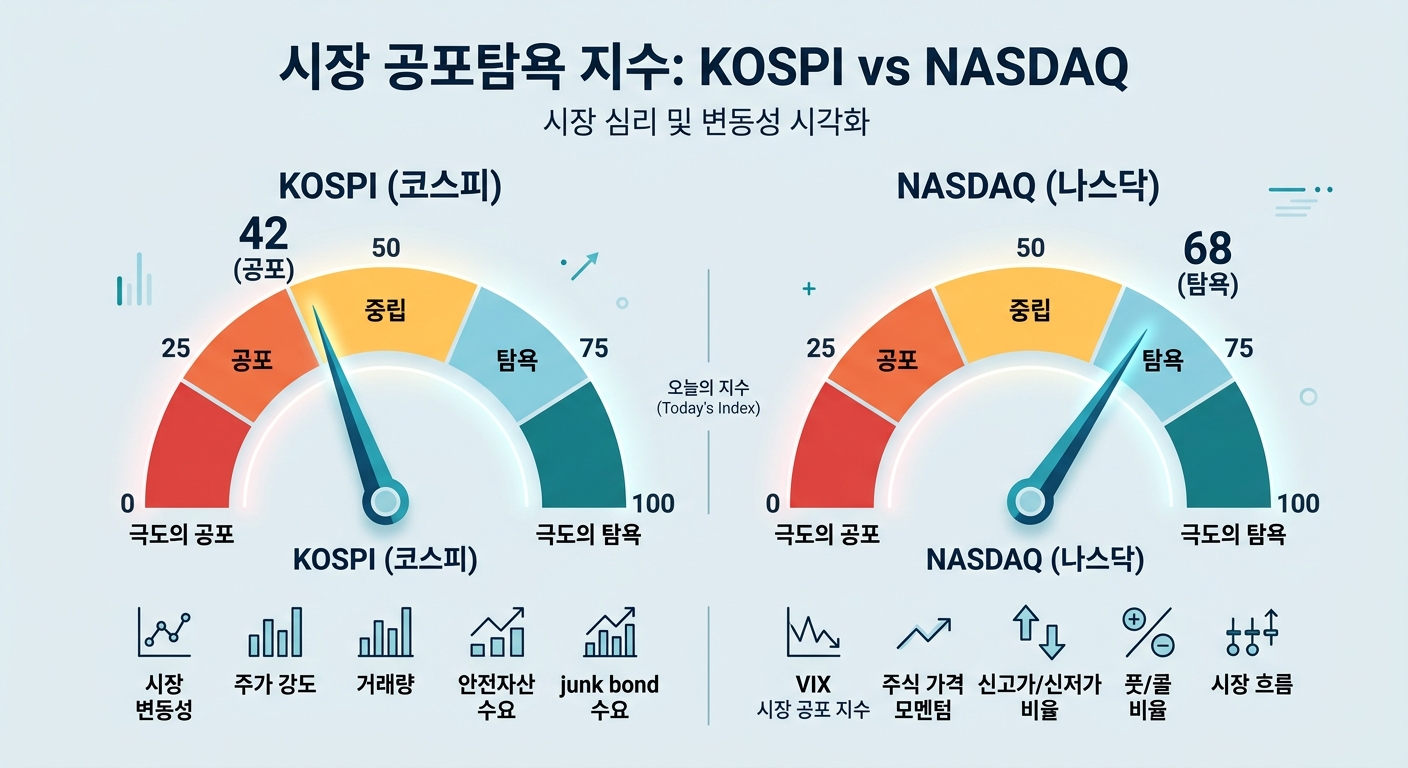
The Daily Stock Fear & Greed Index currently shows Fear (24.4) for the KOSPI—contracted compared to Neutral (40.1) a week ago and Neutral (50.9) a month ago—while the Nasdaq Fear & Greed Index also stands at Fear (37.9), reflecting muted global risk appetite.
Despite this overarching sentiment weakness across broader indices, KOSPI 200 large-cap shipbuilder HD Hyundai Heavy Industries maintains robust fundamentals.
This resilience stems from high-price 88,000 cbm VLAC orders secured since 2024 sequentially entering dry docks, initiating a full-fledged revenue and earnings recognition cycle.
With an expanding revenue share from gas carriers contracted during periods of sharp newbuilding price increases, alongside the normalization of seasonal working days, visibility into a Q4 profitability rebound is strengthening.
Financial Analysis
HD Hyundai Heavy Industries' annual performance trajectory displays a step-by-step upward trend, driven by a declining share of low-margin containership construction coupled with expanding revenue recognition from high-priced LNG carriers and VLACs.
Below is the trend of recent annual performance and key financial metrics:
| Metric | 2024 (Consolidated) | 2025 (Consolidated) | 2026 (Consensus Est.) |
|---|---|---|---|
| Revenue (KRW Trillion) | 14.48 | 17.58 | 23.26 |
| Operating Profit (KRW Billion) | 7,052 | 20,375 | 33,392 |
| Operating Margin (%) | 4.9% | 11.6% | 14.4% |
| Net Profit (Controlling) (KRW Billion) | 6,215 | 14,155 | 25,036 |
| ROE (%) | 11.4% | 18.8% | 24.5% |
| Order Backlog (Years) | Approx. 3.2 yrs | Approx. 3.4 yrs | Approx. 3.5+ yrs |
(Source: Company quarterly reports and FnGuide consensus compilation)
As shipbuilding prices rise steeply, the company's trajectory toward sustaining double-digit operating margins is solidifying.
In particular, the strong performance of the Engine & Machinery Division's proprietary "HiMSEN" engines and expanding volumes of ammonia- and LPG-fueled propulsion systems are contributing to margin defense.
[Image: /stdaily/uploads/202610/gen_6ac8913c298550.95199564.png]
Valuation
While the current stock price of HD Hyundai Heavy Industries is unconfirmed for the trading session (based on the latest confirmed data), its 12-month forward P/E is forming around 16x to 19x.
This reflects a premium over the KOSPI 200 large manufacturing average, but it mirrors its oligopolistic market power in global eco-friendly gas carriers and the value of its remaining 3+ years of dock slots.
Compared to rival shipyards such as China's Hudong-Zhonghua or Jiangnan Shipyard, its robust in-house engine manufacturing capabilities and VLAC delivery track record serve as key multiple anchors.
However, as order momentum transitions into selective contracting after achieving initial targets, expanding consecutive quarterly profits remains essential to justify valuations above 4x P/B.
Expert & Institutional Analysis
Domestic securities research centers are focusing on the profit leverage effect in the commercial vessel division during Q4.
This period marks a structural inflection point where contracts secured in 2023–2024 at elevated newbuilding prices begin accounting for more than 80% of sales, leading to a meaningful reduction in the cost-of-goods-sold (COGS) ratio.
Furthermore, as shipowners compete to secure VLAC slots amid growing demand for maritime ammonia transportation, analysts note a strong likelihood of an earnings surprise, provided delivery schedules face no operational bottlenecks.
From an institutional flows perspective, selective capital inflows are observed entering benchmark shipbuilding stocks with verified earnings turnarounds, even as the broader KOSPI index remains weighed down in fear territory.
Risk Factors
The primary variables include foreign exchange volatility and the potential for a global economic slowdown.
If the KRW/USD exchange rate drops sharply below the mid-1,300 level, it could exert downward pressure on KRW-converted contract margins.
Negotiations over thick steel plate prices for shipbuilding, rising on-site labor costs, and higher outsourcing processing fees could also increase fixed-cost burdens.
Additionally, investors should account for the possibility of temporary pauses in next-generation gas carrier order momentum if global green energy infrastructure projects face delays.
Investment Perspective
From a macroeconomic perspective, the Bank of Korea's benchmark interest rate path and export-import trends remain crucial determinants of exchange rate volatility.
Because foreign institutional flows react sensitively to USD exchange rates and large-cap earnings improvements, it is essential to monitor whether high-priced vessel deliveries proceed according to schedule.
HD Hyundai Heavy Industries has secured the operational stamina to absorb short-term market fluctuations thanks to its abundant order backlog.
Consequently, rather than chasing short-term thematic trades, a disciplined approach focused on quarterly operating margins and the revenue proportion of high-value vessel types is warranted.
Investment Checklist
- [ ] **Monitor VLAC Delivery & Construction Milestones**: Are construction and sea trial schedules for VLACs at the Ulsan shipyard progressing according to plan?
- [ ] **Confirm Ship Price Mix Improvement**: Does the share of high-priced contracts secured post-2023 remain above 70% of total commercial vessel revenue?
- [ ] **Track KRW/USD Exchange Rate Trends**: Is the exchange rate stably supported around the mid-1,300 range through quarterly settlement periods?
- [ ] **Assess Steel Plate & Subcontracting Cost Controls**: Are margin impacts from thick plate price negotiations and one-off expense provisions (such as performance incentives) contained?
- [ ] **Check Market Sentiment Rebound**: Can the KOSPI Fear & Greed Index (currently 24.4) escape the Fear zone to drive improved liquidity into large caps?