[Image: /stdaily/uploads/202609/gen_6abc512c889247.29058085.png]
Hello, this is Daily Stock, delivering precise insights into global tech earnings landscapes and valuation metrics.
Key Summary
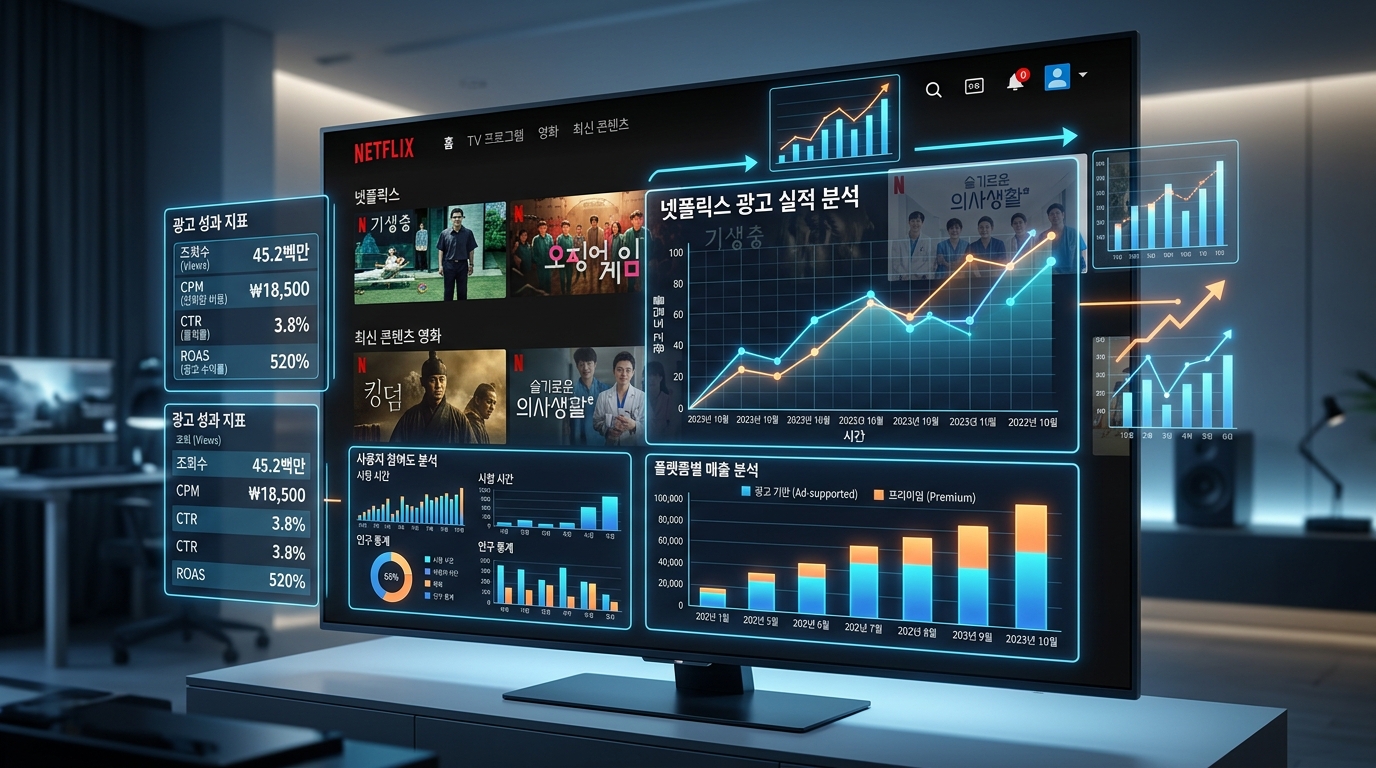
Netflix (NFLX) has entered a full-scale monetization acceleration phase following the rollout of its ad-supported plan (Standard with Ads), standing at a crucial market turning point ahead of its Q3 earnings release.
Driven by a rapid expansion in global monthly active viewers (MAV) and the development of its in-house ad server, the company has transitioned away from a pure subscriber race to a stage where it must prove average revenue per membership (ARM) and margin resilience.
Amid volatility in the 10-year U.S. Treasury yield and concerns over delayed returns on Big Tech's broad AI capital expenditures (CapEx), Netflix stands out as both a defensive play and a growth asset, maintaining robust free cash flow (FCF) with relatively low CapEx requirements.
Current Market Context
As of intraday trading on September 30, 2026 (preliminary), the Nasdaq Composite stands around 26,797.54, while the domestic KOSPI is at 6,870.81, the KOSDAQ is at 849.80, and the USD/KRW exchange rate is at 1,353.00 KRW.
According to Daily Stock's proprietary Fear & Greed Index, Nasdaq market sentiment is currently in the "Fear" (31.6) zone, continuing the subdued sentiment from "Fear" (35) one week ago and retreating sharply from "Neutral" (53.7) one month ago.
The KOSPI Fear & Greed Index is also in "Fear" (36.9), declining from "Neutral" (48.2) one week ago and "Neutral" (48.5) one month ago, synchronizing with the global risk-off environment.
While the current intraday price of Netflix (NFLX) is unconfirmed (based on the latest available data), market attention is focused on the pace of conversion to the ad-supported tier and the sustainability of cost-per-thousand impressions (CPM) ahead of the Q3 earnings print.
Since discontinuing quarterly net subscriber additions—a metric that once fueled streaming wars—Wall Street has justified its valuation multiple through qualitative improvements in platform revenue growth and operating margins.
Financial Analysis
Netflix's full-year 2026 revenue guidance is set between $50.7 billion and $51.7 billion, with annual advertising revenue on track to roughly double year-over-year to around $3.0 billion.
For the Q3 outlook, the core focal point is the improvement in ad inventory fill rates resulting from the global rollout of its proprietary ad-tech platform, "Netflix Ads Suite."
In particular, the ad-supported plan accounts for over 40% to 50% of new sign-ups in key supported countries, structurally increasing the ad tier's penetration across the platform.
| Category | FY 2024 (Confirmed) | FY 2025 (Confirmed) | Q3 2026 (Consensus) | FY 2026 Guidance |
|---|---|---|---|---|
| **Total Annual Revenue (USD)** | Approx. $39.0B | $45.18B | Approx. $11.8B–$12.0B (Quarterly) | $50.7B – $51.7B |
| **Operating Margin (OPM)** | 26.7% | 29.5% | Approx. 30.0% – 31.0% | Target 31.5% |
| **Ad Segment Revenue** | Approx. $710M | Approx. $1.50B | Approx. $750M–$800M (Quarterly) | Approx. $3.0B |
| **Ad-Tier Monthly Active Viewers (MAV)** | 70 Million | 190 Million | Estimated Over 250 Million | Expanding across 15 global markets |
As the ad tier approaches "ARM parity"—where average revenue per member matches that of the Standard ad-free plan—operating leverage is likely to accelerate.
This is underpinned by the structural advantage of overlaying pure, high-margin ad revenue onto existing subscription infrastructure without proportional increases in server or content production costs.
[Image: /stdaily/uploads/202609/gen_6abc513742eb79.85087648.png]
Valuation
Netflix's 12-month forward price-to-earnings (P/E) ratio currently sits between 30x and 33x, positioning it in the middle of its historical band.
In contrast to other Big Tech companies facing scrutiny over potential free cash flow degradation from massive AI CapEx, Netflix maintains a solid annual FCF of $6.0 billion to $7.0 billion or more, securing relative valuation appeal.
While major semiconductor (SOX) and generative AI hardware firms within the Nasdaq 100 face duration risks when the U.S. 10-year Treasury yield (US10Y) rises, Netflix shows relatively resilient defensive properties against rate fluctuations thanks to pricing power and subscription lock-in.
However, to sustain its premium over traditional S&P 500 consumer and media peers (averaging 15x–18x), the company must demonstrate in its Q3 guidance that ad revenue is on a path to surpass 10% of total revenue.
Even in an environment of mild U.S. Dollar Index (DXY) strength, the platform's ability to self-hedge foreign exchange risk through global hits from non-English local content serves as downside support for its multiple.
Expert and Institutional Analysis
Major Wall Street investment banks evaluate that Netflix's ad-supported strategy has transitioned from the "scale building" phase to the "yield optimization and programmatic ad ecosystem integration" phase.
Firms such as Morgan Stanley and Wedbush highlight that securing live sports rights (e.g., NFL, WWE) has boosted ad inventory valuation.
Analysts note that while live events represent a smaller fraction of total viewing hours, they serve as premium slots with the highest CPMs, lifting overall ARM.
Conversely, some cautious voices point out that aggressive ad-tier pushes by rivals such as Amazon Prime Video and Disney+ could introduce downward CPM pressure across the digital video advertising market.
Consequently, institutional investors are placing more weight on advertiser retention rates and margin expansion driven by internal ad-tech adoption than on headline subscriber additions in this Q3 earnings report.
Risk Factors
The most immediate risk is the potential pullback in corporate marketing budgets due to a global macroeconomic slowdown.
If a spending slowdown in digital advertising materializes, fill rates could decline, leaving unsold inventory even if ad-tier user numbers expand.
A second macro factor is upside volatility in the U.S. 10-year Treasury yield and sudden spikes in the CBOE Volatility Index (VIX).
If broader discount rates in the Nasdaq rise again, profit-taking could concentrate in high-multiple tech equities trading above 30x forward P/E.
A third factor is cash burn driven by content cost inflation and competition for intellectual property (IP).
If the costs of acquiring live streaming rights and producing blockbusters exceed estimates, it could temporarily impede progress toward achieving operating margin targets above 30%.
[Image: /stdaily/uploads/202609/gen_6abc5141f18842.83856770.png]
Investment Perspective
Netflix is establishing itself as a tangible cash-generating platform, differentiating itself from the massive AI hardware infrastructure race among Big Tech peers.
In the near term, the contribution of ad revenue presented in the Q3 report and guidance reflecting the Q4 holiday content slate will likely serve as pivotal catalysts for the stock.
Given the potential for sustained valuation pressures on Nasdaq growth equities depending on the trajectory of the 10-year yield and the VIX, a flexible strategy involving staged accumulation as qualitative earnings growth is confirmed remains appropriate.
When the inflection point where ad-tier ARM overtakes the standard plan becomes visible, Netflix is expected to attempt a structural rerating from a traditional OTT platform into a global digital media advertising powerhouse.
Q&A with Daily Stock
Q1. Why does Netflix no longer report quarterly net subscriber additions?
While subscriber additions were critical during the early growth phase, qualitative profitability metrics—such as total revenue, operating margin, free cash flow (FCF), and engagement hours—better reflect enterprise value as the platform matures.
Q2. Is average revenue per membership (ARM) on the ad tier always lower than the ad-free plan?
In the initial phase, lower fill rates resulted in lower ARM than ad-free tiers. However, as ad rates and inventory fill rates rise, the combination of subscription fees and ad revenue can reach parity or generate a "golden cross" where it exceeds standard tier revenue.
Q3. Why is the proprietary ad platform (Netflix Ads Suite) a key financial milestone?
It eliminates intermediary fees previously paid to third-party ad-tech partners to protect margins, and it allows direct control over CPMs via precision targeting based on proprietary viewership data, enabling structural margin expansion.
Q4. How does Big Tech's aggressive AI CapEx cycle impact Netflix?
Unlike hyperscalers, Netflix does not bear the heavy CapEx burden of building proprietary AI data centers, keeping FCF intact while selectively leveraging AI to optimize recommendation algorithms and production workflows.
Q5. How should investors approach Netflix's earnings release given that Nasdaq sentiment is in the "Fear" (31.6) zone?
With broad market multiple compression pressures present, simply meeting headline consensus may not suffice; upward revisions in Q4 margin guidance and ad revenue growth trajectories will likely be the primary criteria for share price defense.