Hello, this is the Daily Stock expert editorial team.
[Image: /stdaily/uploads/202609/gen_6abcb39ad177a3.19001485.png]
Executive Summary
Samsung Biologics (207940) is solidifying its unrivaled dominance in the global contract development and manufacturing organization (CDMO) market, backed by the stable operation of Plant 5 in Songdo and secured manufacturing capacity in Rockville, Maryland.
As the global supply chain realigns under the momentum of the U.S. Biosecure Act, the company has established a definitive competitive edge as an alternative supplier to Chinese competitors.
Thanks to a favorable high foreign exchange rate environment and sustained full operation across Plants 1 through 4, cumulative operating profit for the first half surpassed 1 trillion KRW.
An overwhelming "economy of scale" boasting 784,000 liters of capacity, alongside a solid order backlog, is expected to provide strong downside support for future earnings.
Current Status Overview
Plant 5 (180,000 liters), the initial cornerstone of the Songdo Bio Campus II, has entered commercial operations in earnest.
With this, Samsung Biologics has established a total production capacity of 784,000 liters—the largest in the world for a single company.
Simultaneously, it completed the acquisition of a biopharmaceutical facility in Rockville, Maryland, securing a localized manufacturing base in North America.
Amid legislative pushes for the Biosecure Act in the U.S. Congress, the company has successfully constructed a "two-track" supply chain fulfilling both localized U.S. demand and massive domestic manufacturing capacity.
From a foreign investor supply-demand perspective, inflows are returning to the stock as both a top-market-cap defensive play and a structural growth stock on the KOSPI.
With the KRW/USD exchange rate trading near 1,354.10 KRW, the company is seeing distinct foreign exchange gains and margin defense benefits, characteristic of a CDMO business heavily settled in U.S. dollars.
[Image: /stdaily/uploads/202609/gen_6abcb3a5b9eed1.40058126.png]
Financial Analysis
On a consolidated basis for the first half of 2026, revenue stood at 2.5780 trillion KRW and operating profit reached 1.1672 trillion KRW, delivering record-breaking half-year results.
Second-quarter standalone results also demonstrated resilience, posting revenue of 1.3209 trillion KRW and an operating profit of 586.4 billion KRW, maintaining a high operating profit margin close to the mid-40% range.
Even as initial operational expenses for Plant 5 and fixed overhead for the Rockville facility were recognized early, Plants 1 through 4 sustained an effective full-utilization rate above 80%, driving robust earnings.
Qualitative earnings improvement continues to be supported by securing long-term contracts from global big pharma and achieving a cumulative order total of $21.7 billion since inception.
| Classification | FY 2024 (Annual) | FY 2025 (Annual) | H1 2026 (Cumulative) | FY 2026 (E) |
|---|---|---|---|---|
| **Revenue (100M KRW)** | 36,946 | 45,210 | 25,780 | 53,000–55,000 |
| **Operating Profit (100M KRW)** | 11,137 | 14,280 | 11,672 | 22,000–24,000 |
| **Operating Profit Margin (OPM)** | 30.1% | 31.6% | 45.3% | 41.5%–43.0% |
| **Production Capacity (L)** | 604,000 | 784,000 | 844,000 (inc. U.S.) | 844,000 (inc. U.S.) |
Note: Share price and market metrics as of the trading day (2026-09-30) reflect the latest confirmed closing references, and earnings estimates are based on securities industry consensus aggregation.
Valuation
While Swiss rival Lonza trades at a 12-month forward P/E of 30x to 35x, Samsung Biologics continues to post a compound annual revenue growth rate of 15% to 20%.
Given its superior capacity expansion rate and elevated operating profit margins, the company sits in a justifiable premium range relative to global peers.
Unlike large-cap semiconductor and automotive sectors on the broader KOSPI (6,838.04), which remain vulnerable to global macroeconomic slowdowns and tariff risks, the bio CMO sector exhibits defensive characteristics bolstered by long-term contracts.
Within the large-cap-heavy KOSPI 200 index, Samsung Biologics is recognized for possessing among the clearest earnings visibility, catalyzing a steady valuation re-rating.
Expert & Institutional Perspectives
Daishin Securities and major research institutions identify Samsung Biologics as a primary beneficiary of the U.S. Biosecure Act.
With Chinese CDMO firms such as WuXi Biologics facing potential exclusion from U.S. federal agency procurement and new contracts, analysts note that the reallocation of global big pharma orders is gaining genuine traction.
Institutional investors are focusing on the pace of securing new contract volumes for Plant 5 and the break-even timeline for the Rockville facility.
Domestic market analysts actively position Samsung Biologics as a reliable hedge in a broader market where large-cap Korean equities fluctuate sensitively to foreign futures trading and FX volatility.
[Image: /stdaily/uploads/202609/gen_6abcb3af470f83.18030154.png]
Risk Factors
In the near term, potential production disruptions during labor negotiations and risks related to collective bargaining actions could weigh on client trust from global partners.
Given the precision required in biological processes, even minor interruptions can lead to substantial financial losses and contractual penalties, highlighting the importance of a swift resolution to labor disputes.
Furthermore, implementation grace periods could be extended as U.S. federal court litigation involving Chinese biotech firms unfolds and detailed implementation guidance is finalized.
A sharp appreciation of the Korean won against the U.S. dollar could also temper USD-denominated operating margins, warranting ongoing scrutiny.
Investment Perspective & Summary
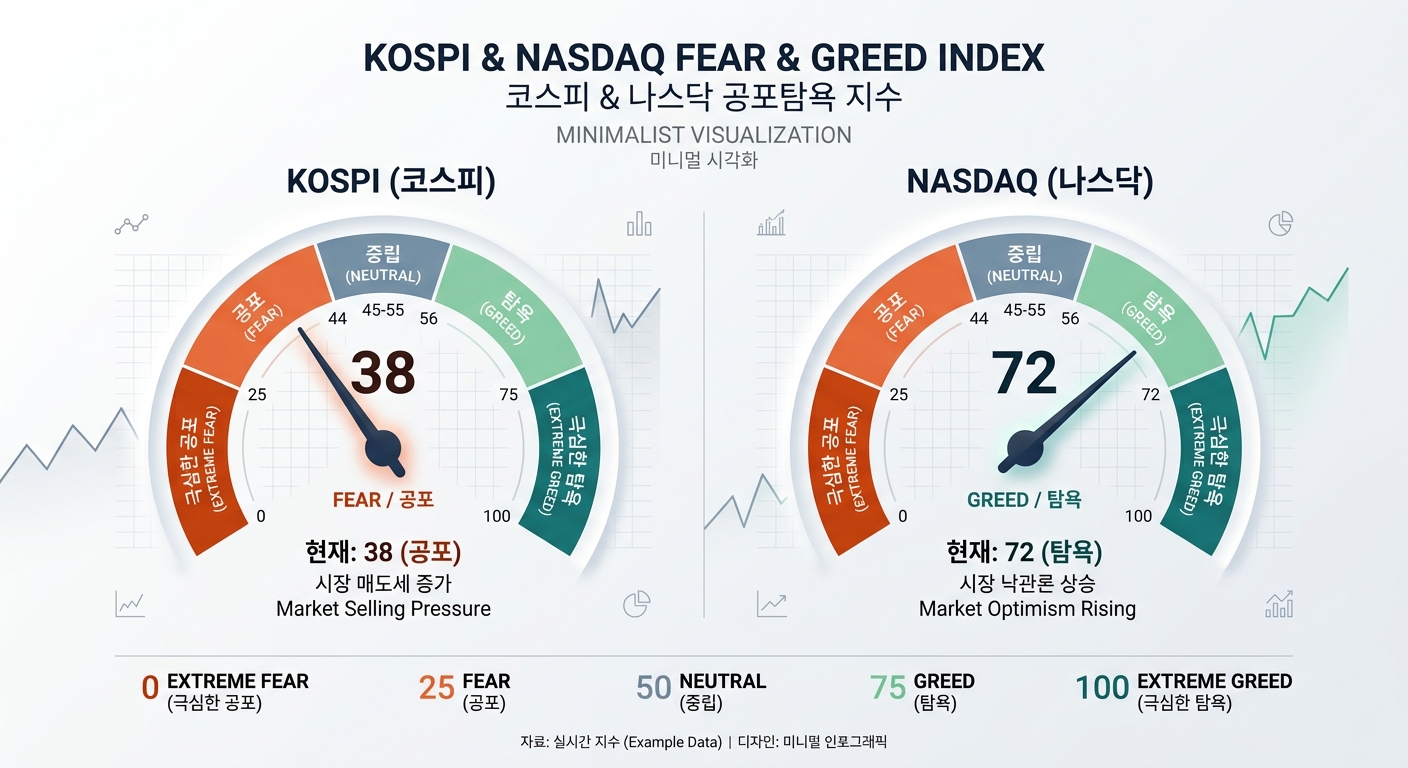
From a macroeconomic perspective, the KRW/USD exchange rate stands at the 1,354.10 level, while the Daily Stock Fear & Greed Index places the KOSPI in the Fear (34.6) zone, indicating a volatile environment.
In such conditions, large-cap biopharmaceutical companies backed by locked-in contract backlogs serve as stronger portfolio buffers than cyclical export sectors.
CDMO contract momentum is likely to persist through the end of the year as the formal enactment of the U.S. Biosecure Act and the designated entity lists become clearer.
Rather than reacting to short-term volatility, a staged accumulation strategy tracking the ramp-up of Plant 5 and utilization trends at the U.S. facility represents a measured approach.
Investor Checklist Q&A
Q1. When will operations from Plant 5 begin to meaningfully reflect in financial earnings?
Biopharmaceutical plants typically require a 1- to 2-year ramp-up period following construction completion and validation. Revenue recognition from new contracts at Plant 5 is expected to expand progressively starting in the second half of 2026.
Q2. The U.S. Biosecure Act is advancing, so why are the benefits not immediate?
Technology transfers to reassign biopharmaceutical production sites typically take 2 to 3 years to clear regulatory validation and approvals. Current activity consists primarily of upstream contract discussions, which translate into long-term backlog expansion over time.
Q3. What is the core strategic significance of the Rockville, Maryland plant acquisition?
Securing drug substance and drug product manufacturing hubs within the U.S. provides a proactive strategic bridgehead against domestic sourcing mandates and U.S. policy initiatives such as the Bio Inflation Reduction Act (IRA).
Q4. To what extent has recent labor tension affected share performance and earnings?
Although temporary collective actions in the first half caused minor batch production adjustments, full-year revenue guidance remains intact through existing inventory utilization and operational optimization. However, the risk of protracted labor actions requires continued observation.
Q5. How are foreign investors viewing large-cap bio equities amid the current KOSPI Fear (34.6) environment?
While cyclical large caps are seeing selling pressure due to broader economic concerns, foreign capital views Samsung Biologics as a defensive alternative anchored by reliable cash generation and substantial committed order backlogs.