Hello, this is Daily Stock.
[Image: /stdaily/uploads/202609/gen_6ab8bf6b223e28.30983870.png]
Executive Summary
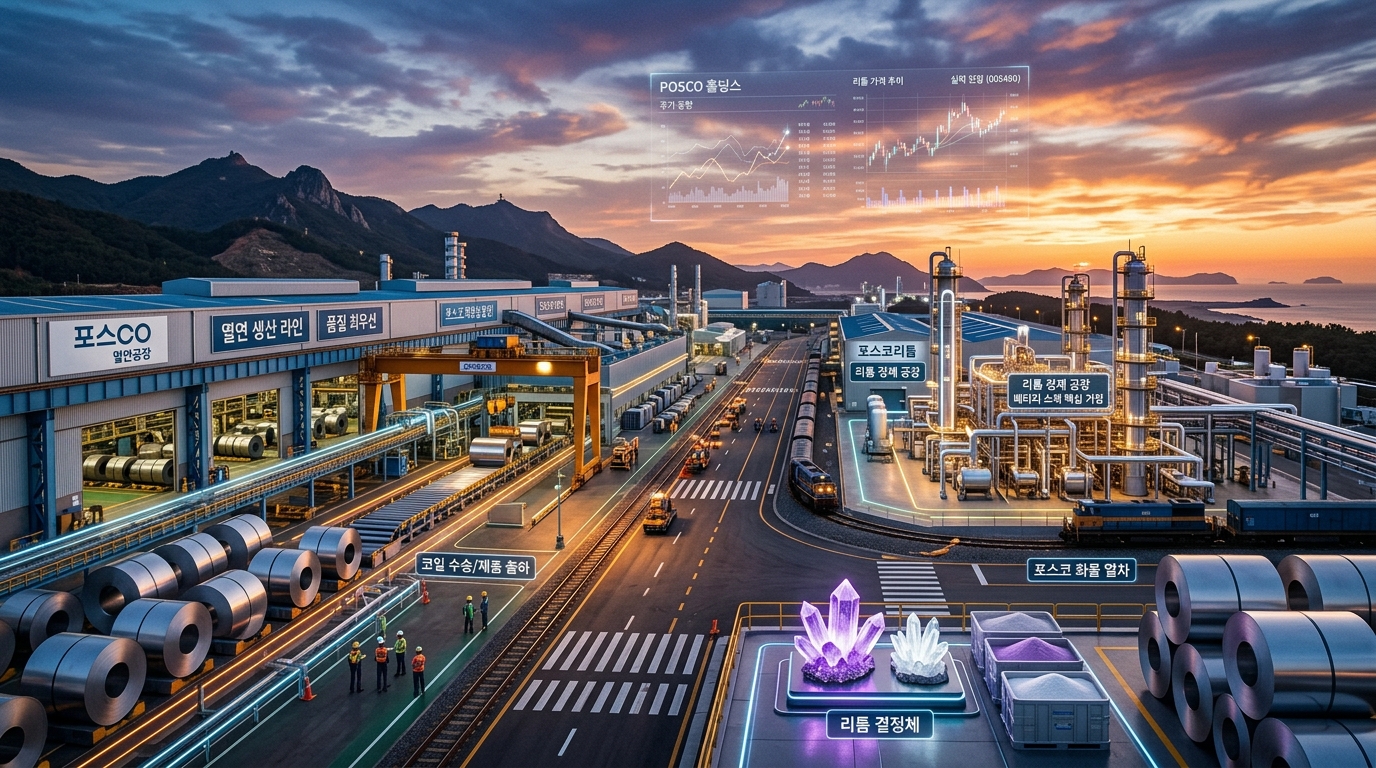
POSCO Holdings (005490) is approaching a structural turning point marked by bottoming-out signals in the traditional steel market alongside the commencement of full-scale commercial lithium production from its brine lake assets in Argentina.
As its core subsidiary, POSCO Argentina, posted its first quarterly operating profit and the Yulchon lithium hydroxide plant ramped up operations, the long-delayed fruits of the secondary battery materials value chain are finally becoming visible.
Simultaneously, China's steel restructuring efforts and burgeoning demand for premium steel products tailored for AI data centers are gradually brightening the prospects for a recovery in primary steel roll margins (spreads).
Market Overview
The domestic stock market currently sees the KOSPI at 7,080.92 and the KOSDAQ at 844.48, while the Nasdaq stands at 27,068.72, reflecting a selective risk-on stance across global asset classes.
The KRW/USD exchange rate fluctuates around 1,359.00, continuing to act as a primary variable for foreign capital flows.
According to Daily Stock's proprietary Fear & Greed Index, the KOSPI sits in Neutral territory at 53.8, showing stabilizing sentiment compared to the Fear stage (30.6) a week ago.
In contrast, the Nasdaq Fear & Greed Index remains in the Fear zone at 37, indicating continued prevailing caution following 30.4 last week.
Within the KOSPI, large-cap steel and materials stocks are forming a consensus around a cycle bottom, while semiconductors, automobiles, and Value-up financials support the broader index floor.
POSCO Holdings closed around 311,500 KRW as of the latest weekend close following the trading session, continuing to trade sideways near the lower boundary of its protracted trading range.
However, significant fundamental transformations are unfolding internally.
Backed by the successful ramp-up of Phase 1 facilities at the Hombre Muerto salt lake in Argentina, POSCO Argentina swung into the black, while recently securing a 1 trillion KRW ($700 million) credit facility for working capital from the Inter-American Development Bank (IDB), substantially mitigating financing risks.
Furthermore, as the integrated ore-and-brine supply chain coupled with the lithium hydroxide production hub in the Yulchon Industrial Complex in South Jeolla Province enters full operations, the company has begun redefining itself from a pure-play steelmaker into an eco-friendly future materials holding company.
Financial Analysis
POSCO Holdings' consolidated earnings are tracing a gradual recovery trajectory after bottoming out in 2025.
Even amid continued input cost pressures from coking coal and iron ore, the company has defended core margins by shifting its product mix toward high-value automotive steel sheets and heavy plates for shipbuilding.
| Classification (Consolidated) | 2024 (Actual) | 2025 (Actual) | 2026 1H Cumulative | 2026 Full-Year Guidance (E) |
|---|---|---|---|---|
| **Revenue (KRW Trillion)** | 77.1 | 69.1 | 37.1 | 75.0 ~ 77.5 |
| **Operating Profit (KRW Trillion)** | 3.5 | 1.8 | 1.5 | 3.2 ~ 3.5 |
| **Net Profit to Owners (KRW Trillion)** | 1.8 | 0.5 | 1.1 | 2.1 ~ 2.4 |
| **Operating Margin (%)** | 4.5% | 2.6% | 4.1% | 4.3% ~ 4.6% |
| **Lithium/Battery Materials Losses** | -441.0 billion KRW | -180.0 billion KRW | Around -30.0 billion KRW | Approaching BEP |
In Q2 2026, consolidated revenue reached 19.2590 trillion KRW and operating profit recorded 819.0 billion KRW, posting robust year-on-year increases of 9.7% and 34.9%, respectively.
In particular, quarterly losses in the secondary battery materials division narrowed drastically, while POSCO International's LNG power generation and energy operations provided a stable profit buffer.
In the second half, the completion of blast furnace overhauls and normalized capacity utilization, paired with the sequential completion of the second Argentine brine lithium plant, are projected to feed into earnings.
[Image: /stdaily/uploads/202609/gen_6ab8bf75d4dce7.18864705.png]
Valuation
POSCO Holdings' current valuation remains trapped in historically low territory.
Based on the latest closing price of 311,500 KRW, POSCO Holdings trades at a 12-month forward price-to-book ratio (PBR) of approximately 0.43x and a price-to-earnings ratio (PER) of roughly 36x.
This reflects a deep discount relative to the average PBR of major large-cap manufacturing peers in the KOSPI 200 (0.9–1.1x), failing to fully mirror even its net asset value.
Even when measured against global peers such as Nippon Steel (PBR 0.5–0.6x) or Baoshan Iron & Steel, the multiple corresponds merely to a standalone steelmaker.
In effect, the market values trillions of won invested in the Argentine salt lakes and the Yulchon complex well below book net asset values.
Consequently, once the lithium unit confirms a breakeven point (BEP) and further steel spread expansion materializes, mean reversion toward a 0.6x PBR (around 440,000 to 460,000 KRW per share) remains a credible scenario.
Expert & Institutional Analysis
Major research centers maintain a 'BUY' rating on POSCO Holdings, providing target prices ranging between 460,000 KRW and 740,000 KRW.
Institutional investors are focusing heavily on macroeconomic conditions and supply-demand alignment.
While a KRW/USD exchange rate lingering in the upper 1,350 range inflates raw material import costs (iron ore, coking coal), it exerts a offsetting positive impact by protecting foreign-currency conversion margins for global export channels.
Foreign investors are monitoring index rollover trends in the KOSPI futures market while selectively initiating passive and bottom-fishing purchases in POSCO Holdings, which stands out as an undervalued cyclical heavyweight.
Analysts assess that if Chinese production cuts and the retirement of aging mills gain traction, regional Asian flat steel price floors will strengthen.
Furthermore, expanding power infrastructure driven by AI data center buildouts is driving up demand for high-efficiency non-oriented electrical steel (Hyper NO) and corrosion-resistant steel (PosMAC), reinforcing expectations for structural margin recovery in the core steel business.
Risk Factors
The primary downside risk is a delay in the recovery of end-user steel demand caused by a global economic slowdown.
In particular, prolonged weakness in China's property market could trigger low-cost export dumping of surplus Chinese steel products, squeezing domestic and overseas pricing power.
Second is the prolonged EV adoption chasm and heightened spot price volatility across lithium carbonate and hydroxide.
Should lithium prices decline further, depreciation and amortization burdens from newly commissioned assets could pressure short-term margins.
Third is sudden volatility in foreign exchange rates.
A sharp appreciation of the dollar pushing the exchange rate toward 1,400 KRW would escalate won-denominated raw material expenditures, temporarily dampening blast furnace margins.
Investment Perspective
At present, POSCO Holdings sits squarely in a typical cyclical rebound window driven by the convergence of a steel spread turnaround and commercial returns from its lithium segment.
Over the short term, a dollar-cost averaging strategy that monitors foreign exchange volatility alongside weekly Chinese steel distribution prices appears pragmatic.
From a medium- to long-term horizon, capital goods multiples could experience sharp upward re-rating as the Bank of Korea's policy easing path coincides with a broader global infrastructure capex cycle.
Given that extreme undervaluation near 0.4x PBR provides strong downside support, investors should adjust positioning while tracking lithium ramp-up velocity and quarterly operating margin gains in the core business.
Investor Checkpoint Q&A
Q1. What is the status of commercial production and profitability at the Argentine brine lithium plant?
POSCO Argentina posted its first quarterly operating profit in Q2 2026 via commercial operations at its 25,000-ton Phase 1 plant. Following the completion of the Phase 2 facility in the second half, supplies of cost-competitive brine-based lithium will expand significantly, driving a structural earnings rebound across the secondary battery materials division.
Q2. What is POSCO's core business strategy against Chinese steel oversupply?
POSCO is curbing commodity grade volume while expanding the share of premium lines, including ultra-high-strength automotive steel (GIGA STEEL), high-manganese steel for maritime applications, and specialized steel for AI data centers (PosMAC). As China also pivots industrial policy from simple volume reductions toward higher-end products, low-priced export dumping pressures are expected to moderate over time.
Q3. How do the 1,359.00 KRW/USD exchange rate and Bank of Korea monetary policy affect performance?
A elevated exchange rate strains roll margins by increasing iron ore and coking coal import costs, but it conversely lifts converted consolidated won earnings from overseas subsidiaries and exports. Looking ahead, an easing policy cycle by the Bank of Korea could stimulate domestic construction and manufacturing demand, benefiting domestic shipment volumes.
Q4. Does the company possess sufficient shareholder return capacity under a 0.43x PBR valuation?
Through non-core asset sales and portfolio restructuring, the company intends to generate over 1 trillion KRW in additional cash by 2028. Supported by robust cash flows and sustained shareholder return commitments, treasury share cancellations and steady dividend payouts are expected to serve as a reliable floor for the share price.
Q5. Can AI infrastructure expansion provide tangible contributions to steel demand?
Large-scale AI data centers favor steel frame architecture over traditional concrete structures, requiring high volumes of premium steel pipes and non-oriented electrical steel for power grids and cooling systems. While this may not fully displace traditional construction volumes immediately, it is steadily lifting the proportion of high-margin specialty offerings.