Hello, this is Daily Stock, analyzing global stock markets and Nasdaq growth stock trends through objective indicators.
Key Summary
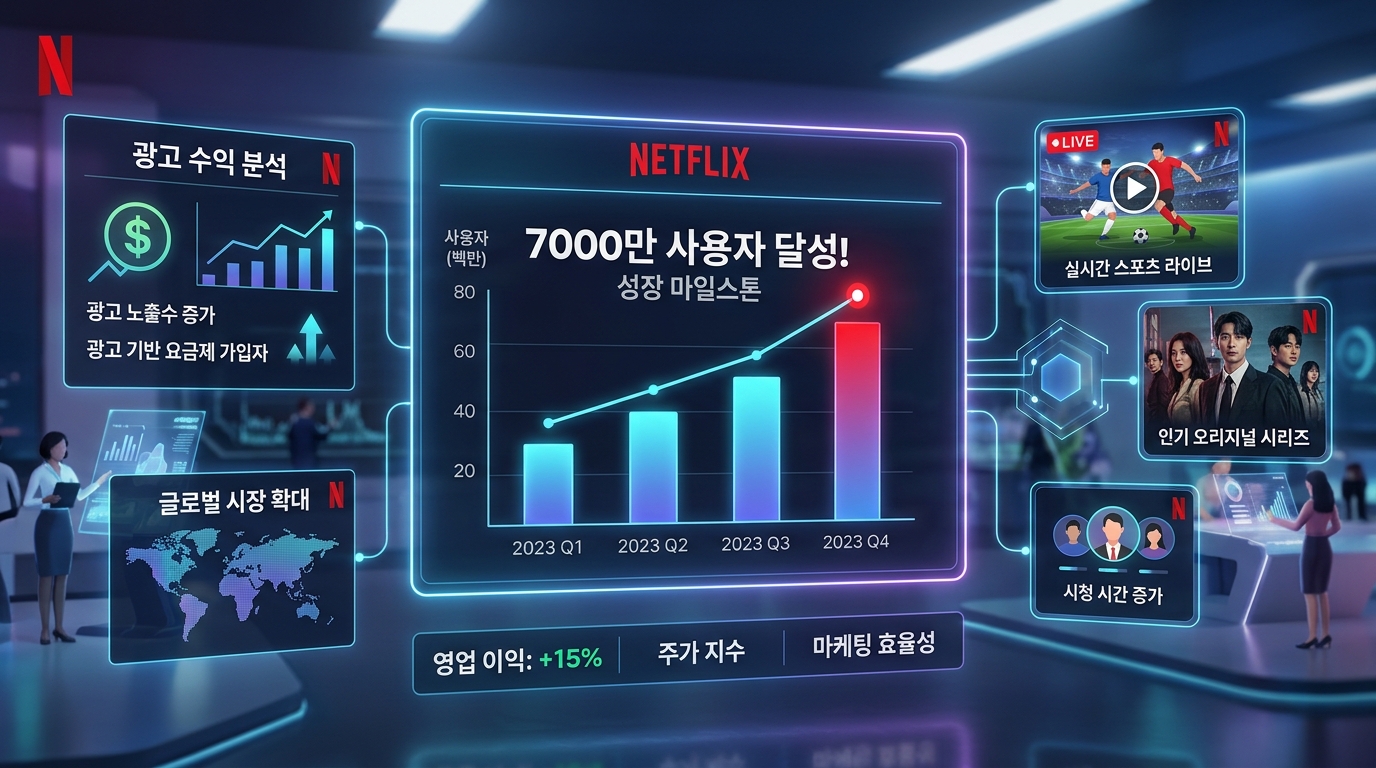
Netflix (NFLX) has demonstrated tangible results in revenue diversification, surpassing 70 million global monthly active users (MAU) on its ad-supported tier just two years after its launch.
In countries where the ad tier is available, more than 50% of new sign-ups are choosing the ad-supported plan. This indicates a smooth transition from a growth structure reliant purely on price hikes to a multifaceted revenue model.
However, from a macroeconomic perspective, elevated 10-year U.S. Treasury yields (US10Y) and heightened volatility could exert valuation multiple compression pressure across high-multiple tech companies.
Current Situation Overview
Since launching its lower-priced ad tier in November 2022, Netflix has rapidly expanded its ad-tier MAU from approximately 40 million in May 2024 to 70 million in just six months.
For its marquee year-end lineup, in-game ad inventory for the live NFL Christmas games has completely sold out early. The company is also accelerating advertiser inflows, including securing exclusive title sponsorships for the globally anticipated Squid Game Season 2.
As of November 21, 2026, the global market environment shows fluctuations across key metrics, with the Nasdaq Composite at 22,617.73 and the USD/KRW exchange rate at 1,346.50.
According to Daily Stock's proprietary Fear & Greed Index, the Nasdaq reading currently stands in Extreme Fear (9.7), shifting from Fear (37.4) one week ago, Fear (28.7) one month ago, and Extreme Fear (5.2) three months ago.
Independent of index price levels, sentiment indicators combining volatility (VIX), momentum, and RSI suggest that market participants maintain an extreme wait-and-see and risk-averse stance.
Domestic South Korean markets also reflect chilled investor sentiment; while the KOSPI sits at 4,869.96 and the KOSDAQ at 645.68, the KOSPI Fear & Greed index is currently at Extreme Fear (11.7), compared to 15.4 a week ago, 6.9 a month ago, and Neutral (51.5) three months ago.
Financial Analysis
Netflix's financial health maintains unrivaled stability among major streaming platforms, driven by consistent free cash flow (FCF) generation and operating margin expansion.
Breaking away from a single revenue stream centered around subscription fees, the addition of advertising revenues and live event broadcasting rights is fostering qualitative growth in average revenue per member (ARM).
| Key Metric | Recent Performance & Company Guidance Trends | Notes & Assessment |
|---|---|---|
| **Global Ad-Tier MAU** | Surpassed 70 million (>50% of new sign-ups) | Achieved massive economies of scale in 2 years |
| **Year-End Major Sports Events** | Sold out ads for 2 NFL Christmas games | Locked in major advertisers like Verizon and FanDuel |
| **Proprietary Ad-Tech** | Launching first in Canada, followed by global rollout | Moving away from Microsoft partnership; expanding margins |
| **Internal Cash Generation** | Maintaining annual FCF around $6 billion | Foundation for share buybacks and live content investments |
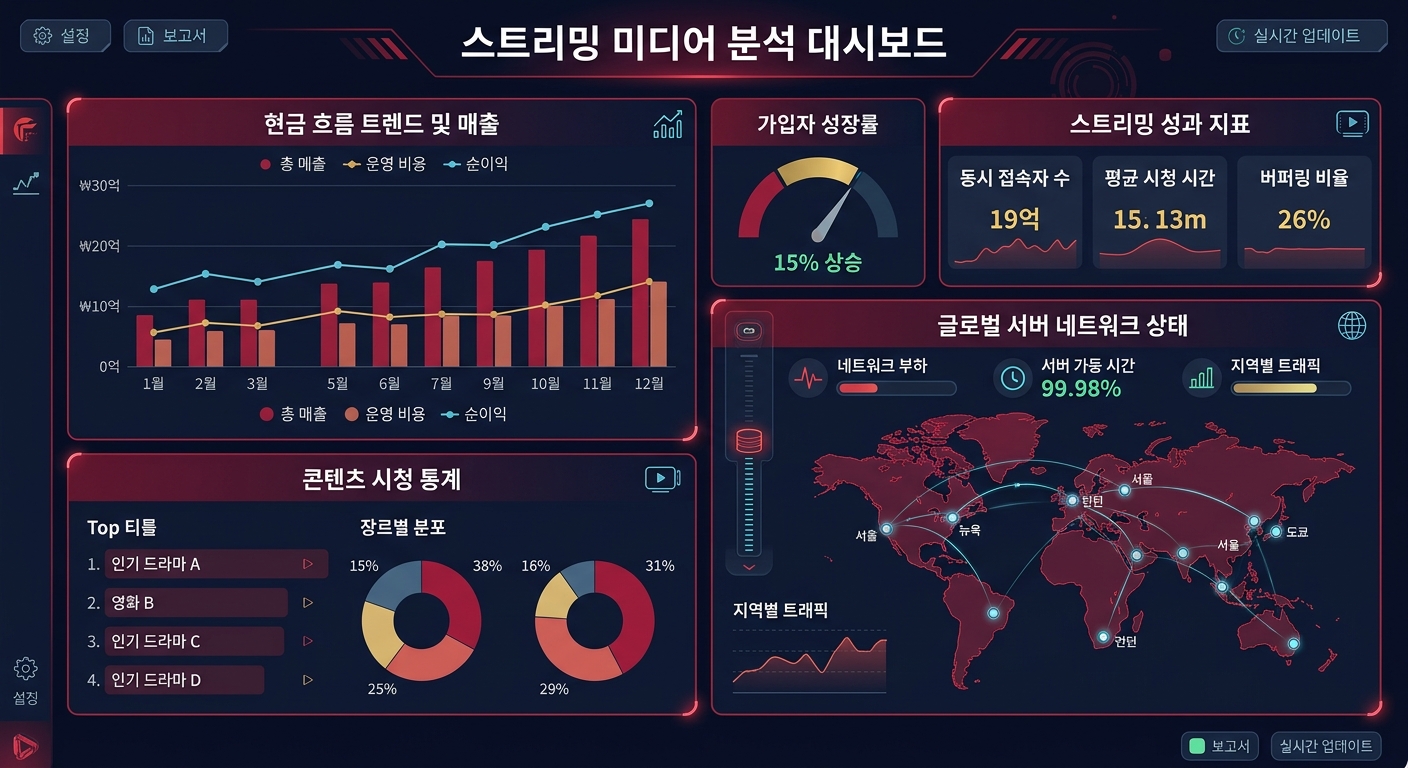
The phased rollout of its proprietary ad-tech infrastructure is viewed as a turning point to reduce reliance on third-party platforms and fully internalize margins from programmatic ad execution.
Efficient execution of content expenditures (Content CAPEX) demonstrates superior margin defense capabilities relative to traditional legacy media.
Valuation
Netflix's valuation sits halfway between big-tech digital advertising platforms (Alphabet, Meta) and traditional entertainment platforms, rather than resembling standard legacy media groups.
While Netflix's share price for the day is unconfirmed as of 2026-11-21 (based on latest confirmed values), its 12-month forward P/E ratio has historically commanded a premium in the mid-to-high 30s to 40x range, significantly higher than traditional media (10–15x).
This premium is justified by its lower churn rate and consistent cash generation compared to typical Nasdaq 100 and S&P 500 growth stocks.
However, if the 10-year U.S. Treasury yield (US10Y) demonstrates downward rigidity, discount rates across high-P/E growth stocks will rise, inevitably exerting contractionary pressure on valuation multiples.
The trajectory of the U.S. Dollar Index (DXY) also acts as an indirect variable for Netflix's converted top line, as international revenue accounts for over 70% of the total.
Expert & Institutional Analysis
Major Wall Street investment institutions maintain a favorable outlook regarding Netflix's ad-tier expansion and push into live streaming (NFL, WWE, etc.).
Firms like Morgan Stanley and Goldman Sachs highlight the potential of in-house ad technology to drive higher ad pricing (CPMs) and improved sell-through rates across 2025 and 2026.
Conversely, some cautious analysts note that despite notable MAU growth in the ad tier, more time is required before advertising represents a meaningful absolute share of quarterly revenue.
They also point out that viewing time share may be nearing saturation, alongside potential downward pressure on CPMs caused by competing streaming services launching their own ad tiers.
Risk Factors
The primary risk is that the pace of ad monetization may fall short of elevated market expectations.
Even as ad-tier subscribers increase, if the spread of lower-priced plans leads existing premium subscribers to downgrade, a net ARM dilution risk emerges.
Substantial fixed commitments for live sports broadcasting rights and increased server traffic and infrastructure costs also place pressure on operating margins.
From a macroeconomic angle, sudden spikes in the Volatility Index (VIX) and a prolonged higher-for-longer interest rate environment could act as headwinds capping valuation multiples.
Investment Perspective Summary
Following its paid-sharing rollout, Netflix is forging a new growth cycle centered on its ad-supported tier and live sports broadcasts.
In the short term, viewership for the NFL Christmas games, incoming traffic from the release of Squid Game Season 2, and Q4 financial results will serve as key inflection points.
Over the medium to long term, close attention should be paid to the successful stabilization of its global proprietary ad platform and the ad revenue conversion rate once WWE broadcasts commence in the first half of 2025.
With Nasdaq sentiment metrics lingering in Extreme Fear, a conservative approach—confirming quarterly cash flows and actual advertising revenue contributions rather than banking on near-term multiple expansion—remains prudent.
Q&A with Daily Stock
Q1. How immediately does surpassing 70M MAU on the ad tier contribute to earnings?
While reaching 70 million monthly active users is encouraging, company guidance suggests that advertising revenue will become a primary top-line driver only once the proprietary ad infrastructure is fully established. It is currently best viewed as an early expansion phase aimed at building an ad inventory pool to attract major brand advertisers.
Q2. Why are live sports broadcasts, such as the NFL Christmas games, so critical?
Live sports bring audiences together simultaneously at specific time slots, serving as a primary vehicle to bring high-CPM traditional TV advertising structures into streaming. As evidenced by the sold-out NFL in-game inventory, live events provide leverage to attract top-tier brand advertisers and increase overall platform value.
Q3. How does the 10-year U.S. Treasury yield (US10Y) affect Netflix's stock price?
Because Netflix's valuation multiple (P/E) reflects high future growth expectations, a rise in the risk-free long-term benchmark rate increases the discount rate applied to future cash flows, putting downward pressure on its valuation.
Q4. What is the tangible impact of introducing proprietary ad-tech on profit margins?
It eliminates third-party platform fees paid under prior partnerships (such as with Microsoft) and optimizes targeted advertising algorithms, allowing the company to fully capture programmatic ad inventory margins internally.
Q5. How should investors navigate when Daily Stock's Fear & Greed Index indicates 'Extreme Fear'?
Regardless of absolute index levels, a score of 9.7 indicating Extreme Fear reflects broad market momentum weakness and elevated volatility. Prudent risk management—prioritizing macroeconomic trends and Q4 guidance over aggressive position increases—is recommended.