Hello, this is Daily Stock, delivering precise corporate value through market context and numbers.
Key Summary
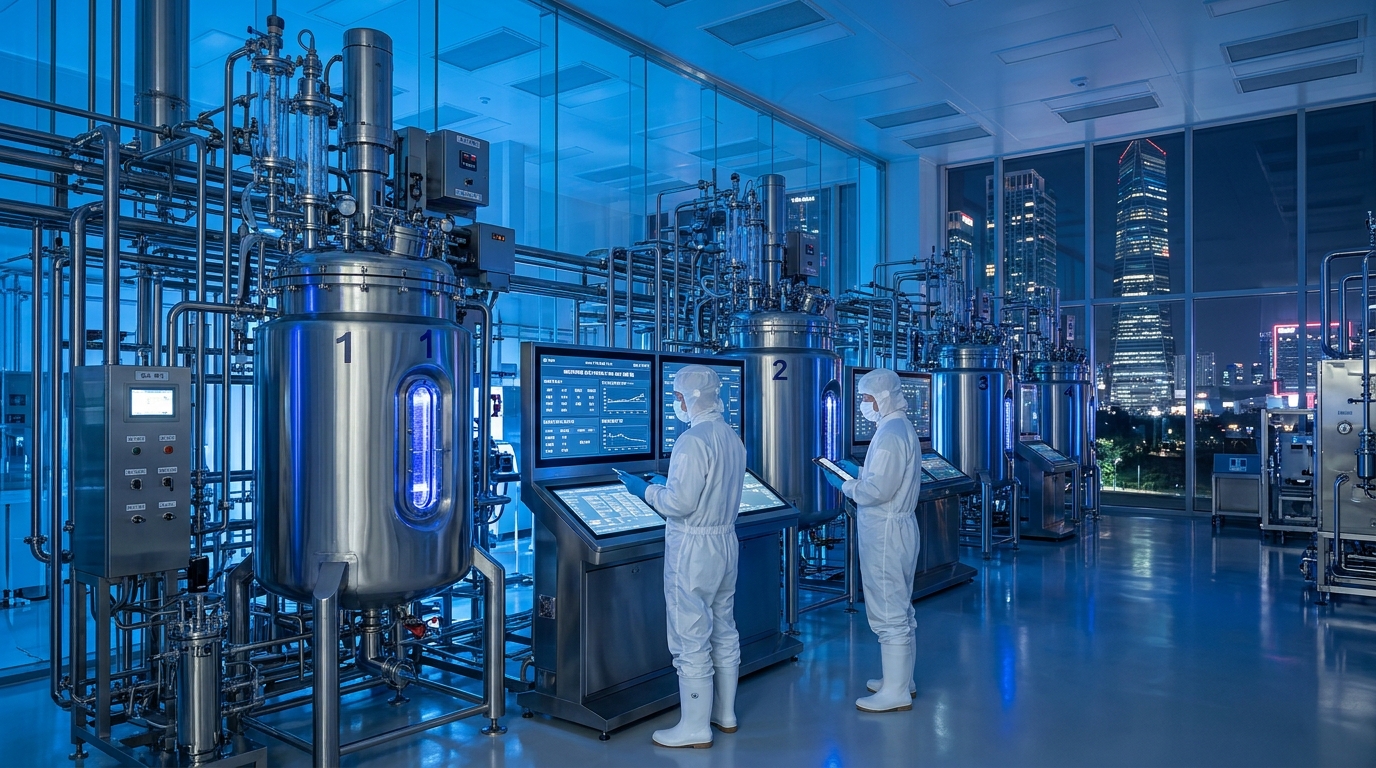
Starting with the operation of its 180,000-liter Plant 5 in Songdo and bolstered by the consolidation of its Rockville plant in the U.S., Samsung Biologics has formalized its position as the global No. 1 in CDMO production capacity (totaling 845,000 liters).
With cumulative orders since inception surpassing $21.7 billion and the order backlog exceeding $15 billion (approximately KRW 20 trillion), the company has secured robust visibility backed by long-term supply contracts with major global pharmaceutical companies.
Against a macroeconomic backdrop of the KOSPI at 5,342.73 and the USD/KRW exchange rate at 1,333.10, the benefit of dollar-denominated revenue translation under a strong dollar, alongside regulatory tailwinds from the U.S. Biosecure Act, serves as the core pillar of mid- to long-term earnings growth.
Current Market Overview
Looking at the market after the close on November 12, 2026, the KOSPI index stands at 5,342.73, the KOSDAQ at 696.53, and the NASDAQ at 25,466.19.
In the foreign exchange market, the USD/KRW exchange rate is at 1,333.10, creating favorable FX conditions for biopharmaceutical contract manufacturing companies whose settlements are overwhelmingly dollar-denominated.
Samsung Biologics' stock price recently underwent a short-term correction due to capital increase and transition-phase issues, as well as the reflection of initial ramp-up costs for Plant 5. However, it is forming a bottom around the latest confirmed price range of KRW 1.30M to 1.31M (with intraday price unconfirmed for the day).
According to Daily Stock's proprietary Fear & Greed Index, which reflects market sentiment, the KOSPI is currently in the "Fear" (22) zone.
While this represents a gradual rebound from "Extreme Fear" a week ago (17.9) and a month ago (4.9), it remains subdued compared to "Neutral" (50.5) three months ago. The NASDAQ Fear & Greed Index is also in "Fear" (36.9), having climbed out of "Extreme Fear" (20) a week ago, yet cautious buying persists amid slowing economic growth and interest rate path uncertainties.
Across KOSPI large caps, where foreign spot and futures flows are sensitively linked to exchange rate volatility, Samsung Biologics—unlike semiconductors or automotive sectors—is serving as a defensive safe haven for foreign passive funds, supported by its peerless order backlog and the benefits of global de-risking away from China.
Financial Analysis
Samsung Biologics' financial structure continues to maintain robust cash flow and a stable debt-to-equity ratio even during large-scale CAPEX deployment.
With existing Plants 1 through 4 (totaling 604,000 liters) continuing to operate virtually at full capacity, Process Performance Qualification (PPQ) batch production at Plant 5 and revenue consolidation from the Rockville plant are gaining full momentum.
| Metric | 2024 (Confirmed) | 2025 (Confirmed) | 2026 (Estimate/Guidance) | Remarks |
|---|---|---|---|---|
| **Consolidated Revenue** | KRW 3.4971T | KRW 4.5570T | KRW 5.3000T–5.5000T | Impact of Plant 5 and Rockville consolidation |
| **Operating Profit** | KRW 1.3214T | KRW 2.0692T | KRW 2.3500T–2.4500T | Sustaining mid-40% OPM |
| **Operating Margin (OPM)** | 37.8% | 45.4% | 44.0%–45.5% | Industry-leading profitability |
| **Cumulative Orders** | Approx. $16.3B | $21.2B | Over $22.0B | 17 global Big Pharma clients secured |
| **Debt-to-Equity Ratio** | Low 50% range | 48.4% | Stable control around ~50% | Borrowings ratio at 11–12% level |
Consolidated revenue for 2026 is projected to grow 15% to 20% year-over-year. The combination of fixed-cost dilution from the Plant 5 ramp-up and favorable high exchange rates is expected to defend an operating margin exceeding 44%.
The debt-to-equity ratio is well-controlled around 50%, with borrowings at the 11% level, demonstrating exceptional balance sheet strength following its transition into a pure-play CDMO structure.
Valuation
Compared to global CDMO peers such as Lonza of Switzerland and WuXi Biologics of China, Samsung Biologics commands a clear premium in terms of capacity expansion speed and batch success rate (99%).
In contrast to the broader KOSPI 200 large-cap healthcare and mid-to-small biotech sectors, which are experiencing multiple compressions due to interest rate uncertainties, Samsung Biologics' solid $15 billion order backlog establishes a strong valuation floor.
However, with the short-term P/E multiple lingering in the 50x–60x range due to the new rights offering and increased initial depreciation costs for Plant 5, further multiple expansion will require confirming the timeline for Plant 6 construction and securing major contract wins in new modalities (such as ADCs and mRNA).
Expert & Institutional Analysis
Securities firms and major credit rating agencies assign high visibility to Samsung Biologics' mid- to long-term order pipeline.
Major domestic research centers analyze that the ramp-up of the Rockville facility and Plant 5 will drive earnings in the second half of 2026, maintaining target prices around KRW 2,000,000 after accounting for per-share value dilution.
Experts consider the supply chain realignment by global Big Pharma—prompted by the Biosecure Act included in the U.S. National Defense Authorization Act (NDAA)—to be the most potent catalyst directing demand toward Songdo.
While temporary friction, such as union strike concerns, previously emerged, the court's approval of an injunction has brought labor dispute uncertainties under control, accelerating the pace of conversions into major definitive contracts.
Risk Factors
The most immediate risk factor is global exchange rate volatility.
Because exports account for the vast majority of business, a sharp decline in the USD/KRW exchange rate below the low-1,300 level could reduce KRW-denominated revenue and FX translation gains.
In addition, initial fixed costs and test production batch expenses from the commercial launch of Plant 5 could put short-term pressure on operating margins, and delays in board approval for additional investments such as Plant 6 could raise concerns over narrowing the capacity lead against competitors.
From a global macroeconomic perspective, any contraction in biotech venture R&D spending linked to the pace of Bank of Korea rate cuts and the U.S. Federal Reserve's policy path remains a structural variable that could limit growth in early-stage contract development (CDO) orders.
Investment Perspective Summary
Samsung Biologics is a premier pure-play CDMO that combines the world's largest capacity with a long-term order backlog capable of transcending economic cycle volatility.
In the near term, investors need to monitor the pace of the Plant 5 ramp-up and the consolidated earnings contribution of the Rockville plant; in a subdued market environment where the KOSPI Fear & Greed Index sits at 22, an accumulation strategy via staggered entries may be reasonable.
Sustained exchange rates in the 1,330 range and announcements of major new contracts from Big Pharma driven by the U.S. Biosecure Act are expected to serve as key catalysts for mid- to long-term share price recovery.
Investment Checklist
- [ ] **Monitor Plant 5 Ramp-up Pace**: Track full-scale commercial batch production at the 180,000-liter facility and the revenue recognition ratio
- [ ] **Cumulative Order Backlog Trends**: Confirm whether annual new orders continue to outpace previous annual levels (KRW 5T–6T)
- [ ] **Tangible Benefits from the U.S. Biosecure Act**: Track execution of definitive contracts with U.S. and European Big Pharma replacing Chinese CDMOs
- [ ] **USD/KRW Exchange Rate Sensitivity**: Assess defense of the 1,300 level and analyze quarterly FX gain/loss impacts
- [ ] **Timing of Plant 6 Investment Resolution**: Check board approval for ground-breaking on Songdo Bio Campus II Plant 6 and associated CAPEX financing plans