Welcome. I am a specialized writer at Daily Stock, delivering in-depth insights into global semiconductor and technology trends.
Key Takeaways
Qualcomm (QCOM) is leading a paradigm shift in the on-device AI market powered by its proprietary Oryon architecture.
Key growth drivers include the expansion of the Windows on Arm (WoA) ecosystem via Snapdragon X Elite and the solidified market presence of Snapdragon 8 Elite in flagship mobile devices.
While the initial pace of market share gains in the PC sector has been gradual, Qualcomm is defending robust profitability in the smartphone application processor (AP) segment through higher average selling prices (ASPs).
However, 10-year US Treasury yield volatility, licensing litigation with Arm, and counteroffensives from the x86 camp remain key variables impacting valuation multiple expansion.
Current Market Context
As of intraday trading on October 29, 2026, in the Korean market (provisional), macro indicators show the Nasdaq Composite at 26,549.85 and the USD/KRW exchange rate at 1,341.00.
Domestic markets are tracking at 6,033.43 for the KOSPI and 769.49 for the KOSDAQ on an intraday (provisional) basis.
According to Daily Stock's proprietary Fear & Greed Index reflecting investor sentiment, the Nasdaq is currently at 35.9 (Fear), maintaining a cautious tone following 30.3 (Fear) one week ago, 32.4 (Fear) one month ago, and 39.3 (Fear) three months ago.
The KOSPI is also at 27.4 (Fear), rebounding slightly from 8.9 (Extreme Fear) a week ago, yet macroeconomic tensions persist.
In the smartphone chipset market, MediaTek retains the top spot by shipment volume driven by entry-to-mid-range devices, while Qualcomm dominates the flagship segment.
According to market research firms such as Counterpoint, Qualcomm commands a shipment volume share of around 28% but maintains leadership in revenue share due to its near-monopoly on high-end premium segments.
Conversely, in the PC market following the launch of Copilot+ PCs, laptops powered by Snapdragon X Elite logged initial quarterly shipments of approximately 720,000 units, representing about 0.8% of the total PC market.
With Intel (Lunar Lake) and AMD (Strix Point) aggressively defending their ground with high-efficiency x86 chipsets, Qualcomm's expansion into mainstream X Plus tiers and the upcoming next-gen X2 Elite faces a critical test.
Financial Analysis
Qualcomm operates through two primary divisions: QCT, which covers mobile, IoT, and automotive chips, and QTL, which manages patent licensing.
Recent performance highlighted notable revenue growth in the handset division, driven by the rollout of Snapdragon 8 Elite for flagship smartphones.
Equipped with Neural Processing Units (NPUs) capable of handling on-device generative AI workloads, chipset ASPs surged by over 20%, reinforcing high-margin profitability.
While the IoT segment—which includes PC chipsets—still contributes only a high single-digit percentage of overall revenue, research and development (R&D) investments are heavily directed there as a mid-to-long-term growth engine.
| Category | Snapdragon 8 Elite (Mobile) | Snapdragon X Elite / Plus (PC) |
|---|---|---|
| **Target Segment** | Flagship AI Smartphones | On-Device AI Laptops (Copilot+ PC) |
| **Core CPU Architecture** | 2nd/3rd Gen Custom Oryon | 1st/2nd Gen Custom Oryon |
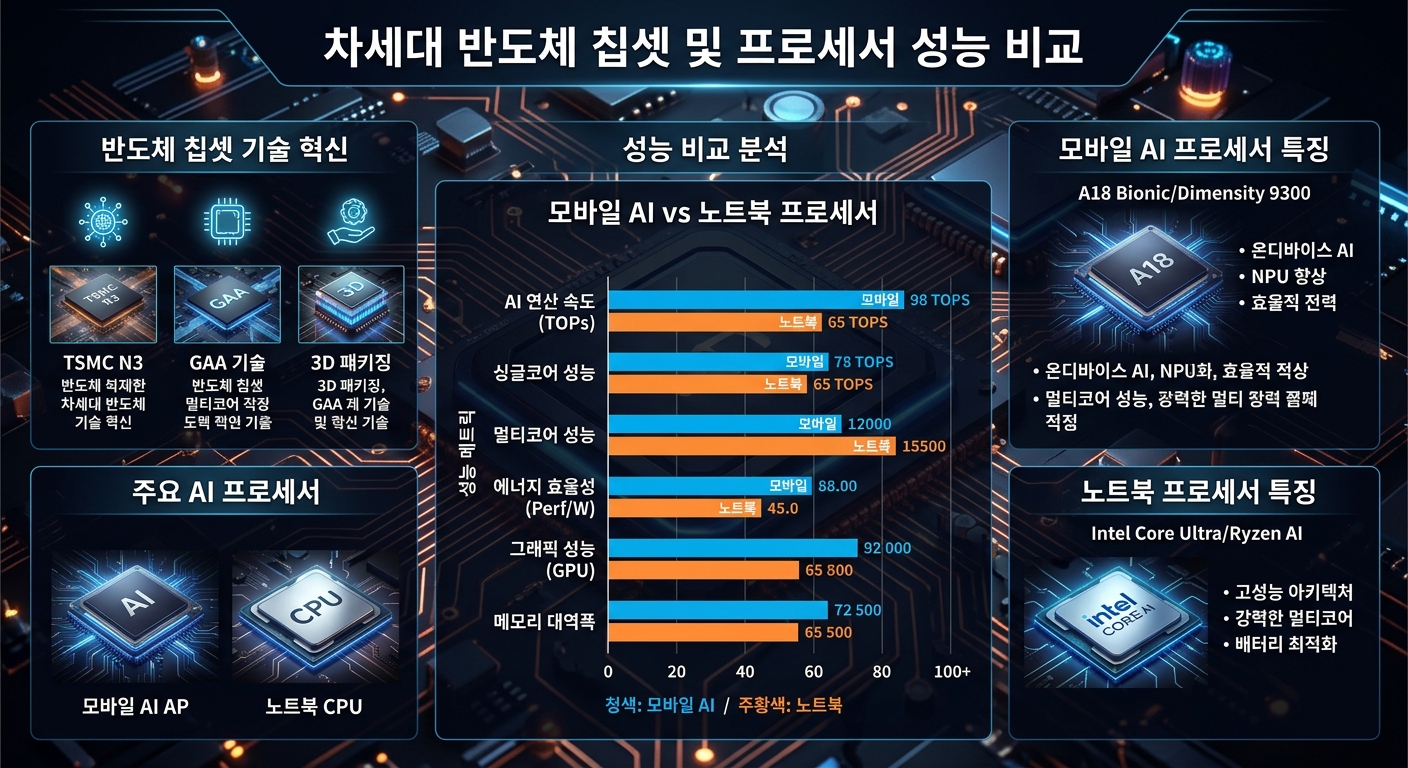
| **NPU AI Performance** | 45+ TOPS On-Device Agent | 45 TOPS Integrated NPU |
| **Market Position & Share** | Dominant #1 in Premium Android | Initial 1–2% share in Total PC Market |
| **Key Customers** | Samsung Electronics, Xiaomi, Oppo, Vivo | Microsoft, Lenovo, Dell, HP, Asus |
Operating cash flow (OCF) remains solid at an annualized range of $11 billion to $13 billion, supporting continued share buybacks and dividend growth.
Amid Big Tech's astronomical capital expenditures (CAPEX) on AI infrastructure, Qualcomm maintains financial flexibility through its fabless outsourcing model, keeping capital intensity low.
Valuation
Qualcomm trades at a forward price-to-earnings (Forward P/E) multiple of approximately 15x to 17x, representing a significant discount relative to the Nasdaq 100 average and AI infrastructure leaders such as Nvidia and Broadcom.
While the broader Philadelphia Semiconductor Index (SOX) has rerated around AI server beneficiaries, on-device AI plays continue to reflect uncertainty regarding monetization timelines.
With the 10-year US Treasury yield (US10Y) hovering near 4%, valuation multiple expansion remains constrained.
The relative strength of the US Dollar Index (DXY) and fluctuations in the Cboe Volatility Index (VIX) also maintain market caution regarding the pace of smartphone replacement cycle recoveries.
If the Snapdragon X series manages to secure a double-digit PC market share by 2027, significant multiple expansion is anticipated.
In the near term, however, the timing of the smartphone upgrade cycle and sustained ASP increases will serve as the primary support floor for valuation.
Expert & Institutional Analysis
Major Wall Street investment banks agree on Qualcomm's dominance in mobile, yet maintain divergent views regarding its penetration speed in the PC market.
Morgan Stanley and Counterpoint Research positively highlighted Snapdragon 8 Elite's virtual monopoly across the Galaxy S series and major Chinese flagship models.
On the other hand, PC market research firms such as Canalys noted that initial feedback from enterprise PC channel partners remains cautious.
With Intel and AMD launching low-power processors leveraging their x86 software compatibility advantage, enterprise adoption of ARM architectures is proceeding gradually.
Nevertheless, prominent global tech analysts emphasize Microsoft's strengthened Windows optimization and Qualcomm's battery life advantage as key structural positives.
Market consensus suggests that once the Snapdragon X series expands into mainstream tiers priced around $700–$800, mass-market adoption could accelerate sharply.
Risk Factors
The most direct legal uncertainty stems from the Architecture License Agreement (ALA) dispute with UK-based chip design firm Arm.
Depending on the outcome of litigation regarding the licensing rights of custom cores acquired through the Nuvia transaction, Qualcomm faces potential risks of royalty rate hikes or business restructuring.
A second risk involves software compatibility and resistance from the entrenched legacy x86 ecosystem in the PC market.
Emulation performance issues with select enterprise security software and legacy programs continue to delay large-scale enterprise upgrade cycles.
Lastly, prolonged consumer IT hardware upgrade cycles amid global macroeconomic deceleration present an ongoing challenge.
If on-device AI features fail to establish themselves as killer applications, consumers may defer purchases of premium smartphones and Copilot+ PCs.
Investment Perspective Summary
Qualcomm stands at a pivotal juncture, expanding from an undisputed mobile AP leader into a diversified PC and automotive chip platform.
In an optimistic scenario, expanding shipments of the next-generation X2 Elite alongside ARM PC market share surpassing 5% could trigger a valuation multiple rerating toward 20x.
In a neutral scenario, even if PC market expansion proceeds at a moderate pace, high mobile margins anchored by Snapdragon 8 Elite will provide downside price support.
In a pessimistic scenario, prolonged litigation with Arm and aggressive price competition from x86 incumbents could escalate customer acquisition and R&D costs.
Investors should closely track tangible utility milestones for on-device AI software and the rollout speed of Copilot+ PC portfolios across major OEMs.
Furthermore, a comprehensive approach is required, factoring in US Treasury yields and inventory cycle adjustments across the global semiconductor value chain.
Frequently Asked Questions
Q1. What were the initial sales figures for Snapdragon X Elite laptops?
In its debut quarter, shipments reached approximately 720,000 units, accounting for roughly 0.8% of the global PC market.
While initial volumes were modest, gradual expansion is expected through Microsoft Surface models and new OEM launches.
Q2. What are the key advantages of Snapdragon PCs over traditional x86 processors from Intel and AMD?
The primary benefits are superior power efficiency inherent to ARM architecture and all-day battery life.
Additionally, the 45 TOPS NPU ensures seamless native execution of Windows Copilot+ AI capabilities.
Q3. How does Qualcomm's market share compare to MediaTek's in mobile APs?
In unit shipment terms, MediaTek leads with a mid-30% market share, while Qualcomm holds around 28%.
However, because Qualcomm commands the high-end flagship space, it retains a definitive lead in revenue and operating profit share.
Q4. What is the potential impact of the Arm licensing litigation on Qualcomm?
The legal dispute over proprietary Oryon CPU core licensing rights continues to weigh on near-term investor sentiment.
While higher royalty fees remain a possibility in a settlement scenario, mutual compromise is widely anticipated over a breakdown in relations, given the interdependence of the tech supply chain.
Q5. Can Qualcomm sustain its competitive moat in on-device AI smartphone chips?
The Snapdragon 8 Elite continues to exclusively power tier-one flagship devices, underpinned by industry-leading CPU and NPU performance.
With the integration of custom-designed CPU cores, Qualcomm has significantly improved its performance-per-watt efficiency, reinforcing its technical moat.