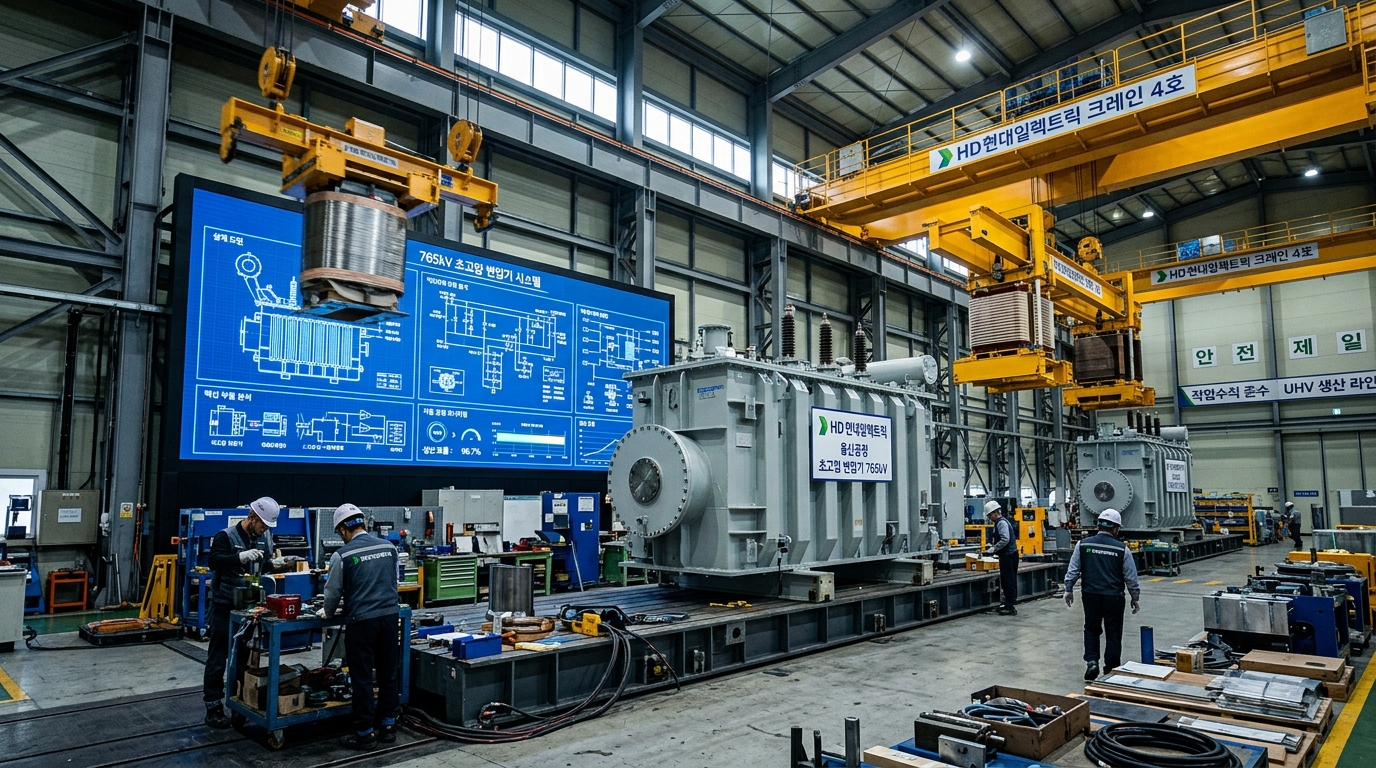
Amid the sweeping transformation of domestic and global power infrastructure, we closely examine the mid- to long-term growth momentum of this leading KOSPI power equipment company.
Key Summary
Driven by the expansion of artificial intelligence (AI) data centers and replacement demand for aging power transmission grids in North America, HD Hyundai Electric is sustaining a historic order rally, filling delivery slots through 2029.
Its total order backlog has surpassed KRW 10 trillion, with North America—the most profitable region—accounting for approximately 70%, firmly securing medium- to long-term earnings visibility.
With the finalization of its ultra-high voltage (UHV) transformer plant expansion in Ulsan and the groundbreaking of its second plant in Alabama, production bottlenecks are easing, bringing an annual top-line expansion in the trillions of won well into view.
Current Status Overview
The global power infrastructure supercycle is transcending short-term thematic trends, evolving into a structural supply shortage expected to persist until 2030.
HD Hyundai Electric has secured continuous orders for 765-kilovolt (kV) ultra-high voltage transformers and shunt reactors from major utility companies in Texas and across the MISO and SPP regions.
A 765kV transformer is a state-of-the-art, high-end power asset that minimizes transmission loss over ultra-long distances with heavy capacities; only a very limited number of manufacturers worldwide can mass-produce it.
To address this surge in orders, HD Hyundai Electric has wrapped up the expansion of its Ulsan UHV transformer facility and is entering full commercial operation stages.
Concurrently, the company broke ground on its second manufacturing plant in Montgomery, Alabama—a project backed by an investment of approximately $200 million—targeting completion by April 2027.
Once the second Alabama plant is operational, its local UHV transformer production capacity will increase by 50%, expected to generate an additional KRW 200 billion in local annual revenue.
Financial Analysis
On a consolidated basis for the full year 2025, HD Hyundai Electric recorded revenue of KRW 4.0795 trillion and an operating profit of KRW 995.3 billion, achieving an operating margin of 24.4%—among the highest profitability levels in the manufacturing sector.
Bolstered by an expanding share of high-margin North American deliveries and rising average selling prices (ASP), annual operating cash flow reached KRW 959.6 billion.
The debt-to-equity ratio, which once exceeded 170%, stabilized to 134.6%, and net debt dropped to -KRW 782.7 billion, solidifying a virtually debt-free balance sheet.
With cash and cash equivalents reaching approximately KRW 968.0 billion, capital expenditures for expanding the Ulsan and Alabama plants are fully financed with internal surplus cash flow rather than external borrowings.
| Key Metric | 2023 | 2024 | 2025 (FY) | 1H 2026 Trend |
|---|---|---|---|---|
| **Consolidated Revenue** | KRW 2.7028T | KRW 3.3223T | KRW 4.0795T | Sustained quarterly growth |
| **Operating Profit (Margin)** | KRW 315.2B (11.7%) | KRW 669.0B (20.1%) | KRW 995.3B (24.4%) | Sustained mid-20% margins |
| **Order Backlog** | $4.3B | $5.5B | Surpassed ~KRW 10T | North America exceeds 69% |
| **Net Debt Ratio** | 48.7% | -20.6% | -38.5% (Net Cash) | Cash equivalents at KRW 968.0B |
Valuation
Daily stock price and market capitalization are as of the close on 2026-10-17: "Unconfirmed daily market price (based on latest confirmed value)."
The 12-month forward price-to-earnings (P/E) ratio trades in the range of 15 to 18 times, underpinned by upward revisions in earnings estimates.
Given that global peers such as Eaton, Schneider Electric, and Quanta Services trade above 25 to 30 times, HD Hyundai Electric retains relative valuation appeal.
Even among large-cap KOSPI 200 stocks, the company is breaking away from the traditional industrial manufacturing valuation trap, steadily rerating as a high-tech infrastructure growth play.
A return on equity (ROE) hovering in the 30% range and an operating margin exceeding 20%—unrivaled among peer heavy manufacturers in the KOSPI 200—justify this valuation premium.
Expert & Institutional Analysis
Securities analysts collectively view concerns over an "earnings peak-out" raised by some market participants as unfounded.
UHV transformers typically require 3 to 4 years from order placement to final delivery, and delivery contracts for 2028–2029 are already being executed, suggesting the order cycle will extend at least until 2030.
Institutions and global infrastructure funds are also focusing on portfolio diversification into distribution equipment, supported by the late-2026 completion of the Ulsan plant expansion and the stabilization of the smart factory for medium- and low-voltage circuit breakers in Cheongju, North Chungcheong Province.
However, as of October 17, 2026, while macro equity benchmark levels remain elevated—with KOSPI at 5,668.05 and NASDAQ at 26,140.03—volatility indicators reflect extreme caution.
Daily Stock's proprietary Fear & Greed Index places KOSPI in "Extreme Fear (5.3)," following "Extreme Fear (15.5)" one week prior and "Fear (25)" one month ago, highlighting severely dampened sentiment.
The NASDAQ Fear & Greed Index similarly indicates "Extreme Fear (17.9)," cooling sharply from "Neutral (46.5)" a week ago.
This subdued investor sentiment running beneath broad index levels acts as a short-term variable, amplifying flow volatility from institutional and foreign investors in large-cap names.
Risk Factors
The first risk factor is macro foreign exchange volatility.
As of October 17, 2026, the USD/KRW exchange rate stands at 1,337.80. A strong US dollar serves as a solid earnings buffer for a company with such a dominant export exposure to North America.
However, should the Bank of Korea's rate-cutting stance converge with a monetary policy pivot from the U.S. Federal Reserve, precipitating a sharp downward stabilization of the exchange rate (KRW appreciation), margins translated into KRW could experience modest compression.
The second risk involves raw material prices and supply chain management (SCM).
Price swings in grain-oriented electrical steel (GOES) and copper (rectangular winding wire)—core raw materials for UHV transformers—as well as potential bottlenecks in securing skilled technicians locally, could weigh on early ramp-up yields at expanded facilities.
The third risk centers on North American grid policy shifts.
Adapting to potential changes in U.S. trade policies or higher tariff barriers following U.S. presidential election cycles underscores the importance of promptly establishing and scaling local production capabilities at the Alabama facility.
Investment Perspective Summary
HD Hyundai Electric stands out as a core KOSPI stock capturing the direct, structural upside of the AI data-center-driven power supercycle within its order backlog.
The expansion of the Ulsan plant serves as a pivotal inflection point, dismantling the "capacity ceiling" narrative that previously constrained equity upside.
With the broader sentiment index currently lingering in "Extreme Fear (5.3)," short-term market flow disruptions may occur; thus, emotional impulse trading should be avoided.
Taking advantage of pullbacks via phased accumulation—supported by long-term cash flow horizons through 2027 when expanded facilities begin driving top-line revenue, alongside a debt-free balance sheet—represents a prudent approach.
Frequently Asked Questions
Q1. What is the completion schedule for HD Hyundai Electric's Ulsan plant expansion?
The expansion of new production lines at the Ulsan facility to handle rising UHV transformer orders has progressed toward completion in the second half of 2026, transitioning into test runs and commercial production preparation.
Q2. When will the second plant in Alabama, USA, begin operations?
Following an investment of approximately $200 million and a groundbreaking ceremony at the Montgomery, Alabama facility in the first half of 2026, completion is scheduled for April 2027, with full commercial revenue expected to commence in the second half of that year.
Q3. What is the current order backlog level and its North American share?
The total order backlog has exceeded KRW 10 trillion, with the North American market comprising roughly 69% to 70%, providing a firm baseline for profitability.
Q4. How long is the transformer order rally expected to last?
Transformer cycles generally reflect long-term infrastructure investment. Compounded by U.S. grid replacement needs and big tech AI data center power demand, delivery contracts are already locked in through 2029–2030.
Q5. Will a lower USD/KRW exchange rate significantly harm earnings?
Given the high concentration of North American contracts, KRW appreciation may slightly trim translated revenue in the short term. However, the company is gradually curbing foreign exchange sensitivity by securing contracts at higher unit prices and scaling local production at the Alabama facility.