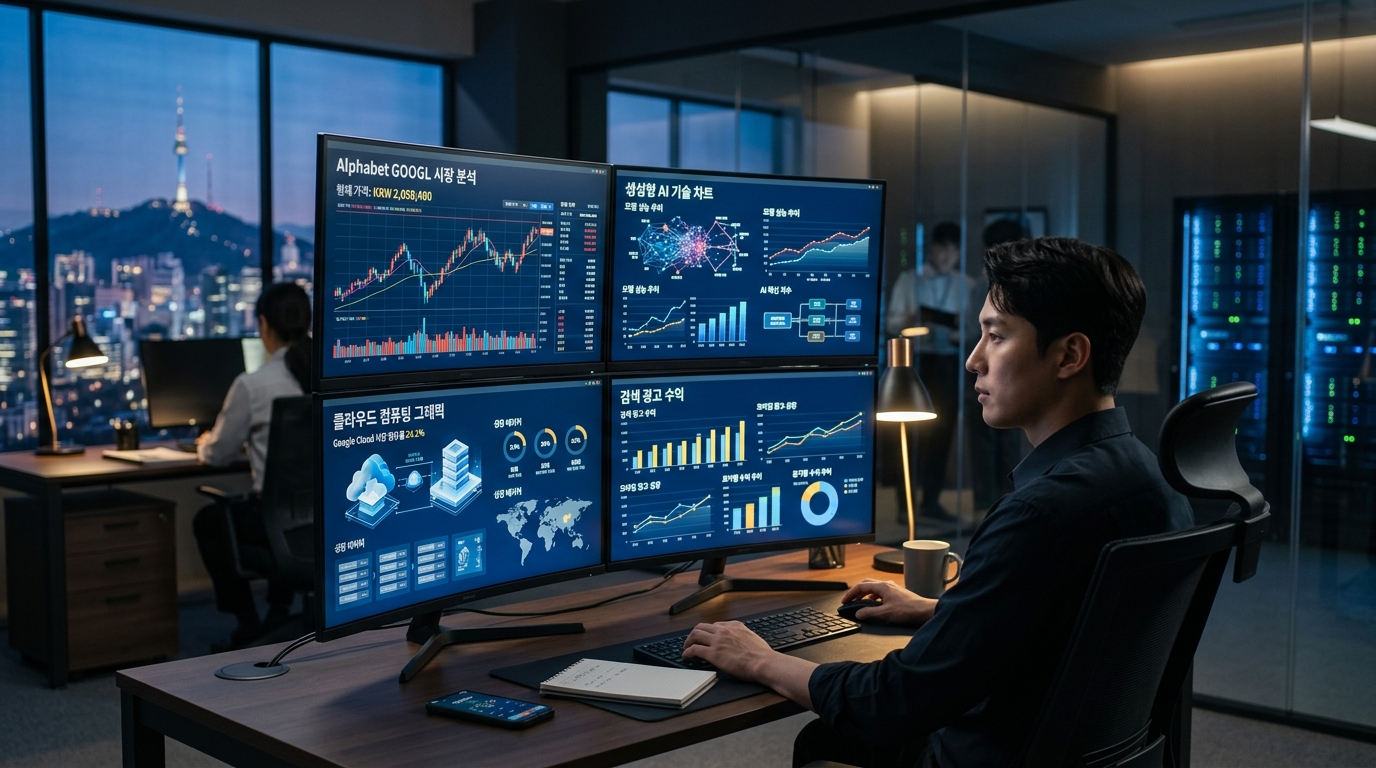
Hello, this is Daily Stock, delivering context across global technology and financial markets.
Executive Summary
Alphabet (GOOGL) continues to demonstrate robust resilience in its core business, overcoming initial concerns over ad revenue cannibalization following the rollout of generative AI features like 'AI Overviews' in its search engine.
Simultaneously, enterprise adoption of Gemini Enterprise across Google Cloud is expanding, marking a full-scale entry into monetization across B2B software and proprietary TPU-based infrastructure.
However, massive capital expenditures (CAPEX) exceeding $90 billion annually, multiple sensitivity linked to U.S. 10-year Treasury yield (US10Y) volatility, and ongoing antitrust litigation risks remain critical headwinds testing the upside of the stock price.
Current Market Overview
As of intraday trading on October 12, 2026 (preliminary), the Nasdaq index hovered around 27,366.17, navigating an earnings verification phase across broad tech equities.
Across domestic and international financial market indicators on the same day, the KOSPI stood at 6,625.93, the KOSDAQ at 892.27, and the USD/KRW exchange rate recorded 1,342.00 KRW.
According to Daily Stock's proprietary Fear & Greed Index, the Nasdaq is currently measured at Neutral (45).
This reflects a mild rebound in sentiment compared to Fear (40) one week ago and Fear (38.2) one month ago, yet maintains cautious undertones relative to Neutral (48.6) three months ago.
Meanwhile, the KOSPI Fear & Greed Index sits at Fear (24.4), contracting sharply from Neutral (40.1) one week ago and Neutral (50.9) one month ago.
Alphabet's (GOOGL) price action for the session is listed as 'Unconfirmed for the day (based on latest verified value)', but shares have recently traded in the mid-to-high $340 range on Wall Street as market participants await forward earnings guidance.
Financial Analysis
Alphabet's quarterly revenue surpassed the historic $100 billion milestone for the first time, propelled by steady growth in traditional search advertising alongside robust cloud momentum.
Google Search and other advertising revenue maintained double-digit growth (around 15% year-over-year) despite the deployment of generative search summaries, supported by resilient commercial queries and cost-per-click levels.
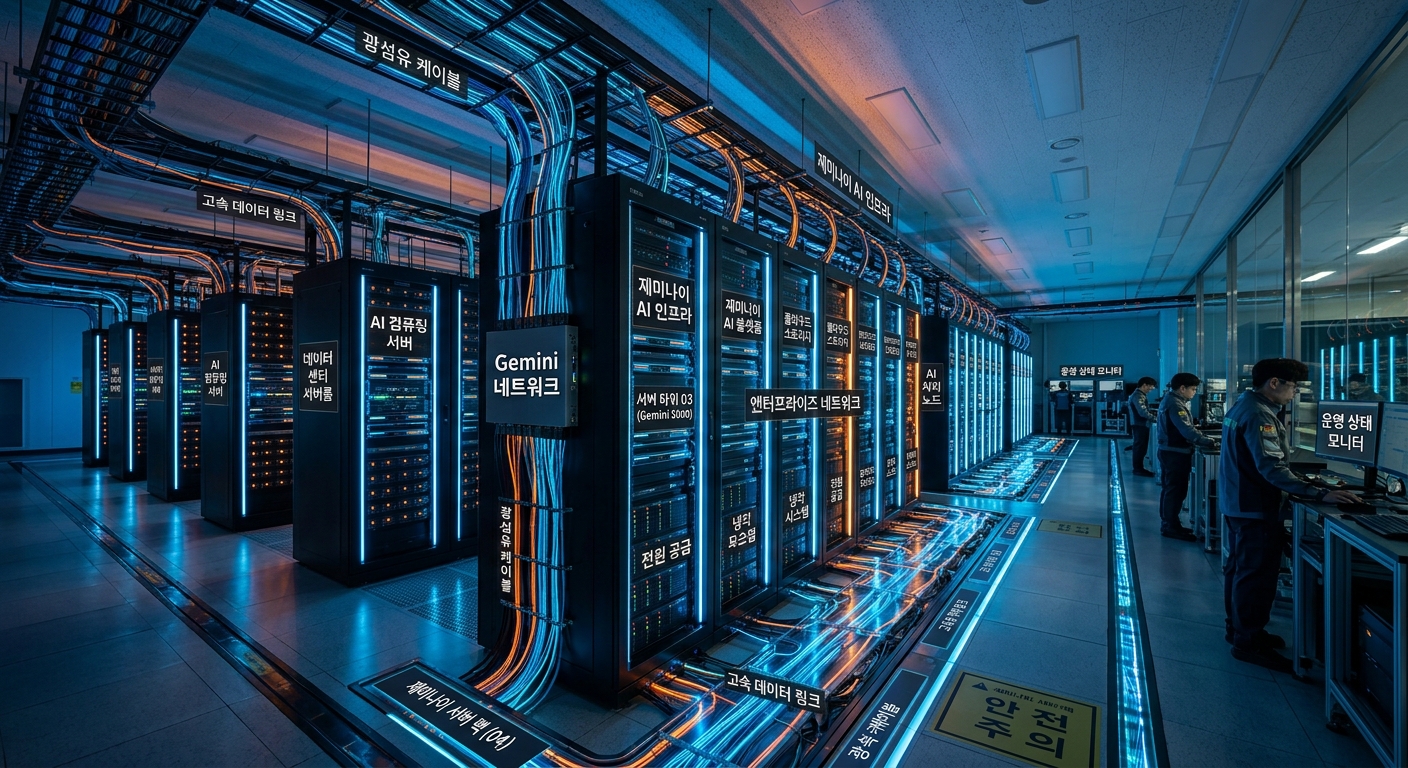
Google Cloud delivered rapid top-line growth exceeding 30% year-over-year, contributing significantly to consolidated operating margin expansion.
Notably, with a majority of Fortune 100 companies adopting Gemini Enterprise solutions and cumulative order backlog topping $150 billion, Alphabet has established a virtuous cycle where AI infrastructure outlays convert into tangible revenue.
| Key Financial & Operational Metrics | Recent Performance & Verified Value | Business Significance & Impact |
|---|---|---|
| Quarterly Consolidated Revenue | Approx. $102.3B | First-ever quarterly revenue above $100B; dual growth across Ads and Cloud |
| Google Cloud Growth Rate | Approx. +34% YoY | Driven by Gemini Enterprise adoption and proprietary TPU infrastructure demand |
| Cloud Backlog | Approx. $155.0B | Secures medium-to-long-term cloud revenue visibility |
| Annual Capital Expenditure (CAPEX) | Est. $91.0B – $93.0B | Focused allocation into AI data centers and custom accelerator hardware |
| Gemini API Token Throughput | 7B – 22B tokens/min | Deepening integration across external B2B developers and enterprise systems |
Valuation
Alphabet has traditionally maintained an attractive valuation discount based on Forward P/E multiples relative to its Big Tech peers.
However, with annual capital expenditure surpassing $90 billion and projected to expand further past 2026, near-term free cash flow (FCF) generation faces temporary pressure.
From a macroeconomic perspective, elevated U.S. 10-year Treasury yields (US10Y) and relative strength in the U.S. Dollar Index (DXY) continue to constrain multiple expansion across high-multiple tech assets.
Compared to major software peers in the Nasdaq-100, Alphabet's full-stack vertical integration across custom hardware, foundation models, and cloud infrastructure affords stronger margin defense.
Conversely, compared to pure-play infrastructure beneficiaries in the Philadelphia Semiconductor Index (SOX), valuation re-rating for platform companies remains more tightly tethered to the actual pace of commercial AI monetization.
Institutional & Analyst Insights
Major Wall Street investment firms hold favorable views on Gemini's enterprise scalability and Google's expansion into external TPU commercialization.
Investment banks including Wells Fargo highlighted that custom TPU revenue contributions within Google Cloud are scaling to billions of dollars per quarter.
Institutional research notes that Alphabet is successfully pivoting away from a legacy model of simply surfacing text ads in search boxes toward contextual ads and autonomous agent billing embedded inside conversational search interfaces.
Nonetheless, a cautious counter-narrative persists alongside intermittent spikes in market volatility (VIX), pointing out that aggressive power purchase agreements and data center capital outlays could transform into heavier depreciation burdens over the coming quarters.
Risk Factors
Alphabet's primary operational risk is the time lag between monumental AI capital outlays and their subsequent cash flow monetization.
Because compute costs for Large Language Models (LLMs) exceed traditional search queries, failure to structurally drive down unit query processing costs could dilute operating margins.
Second, antitrust regulatory actions led by the U.S. Department of Justice (DOJ) and the European Union (EU) pose structural headwinds.
Restrictions on default search distribution agreements (such as partnerships with Apple) or structural remedies targeting the AdTech division represent direct threats to Alphabet's wide moat.
Third, macro uncertainty—including delayed benchmark interest rate cuts or pullbacks in corporate marketing budgets—could slow top-line growth in core search advertising.
Investment Takeaway
Alphabet has navigated past initial market skepticism regarding generative AI's threat to search, entering a phase where technological leadership is validated through financial results.
Resilience in core search advertising alongside market share gains in Cloud via Gemini Enterprise form the core pillars strengthening medium-to-long-term fundamentals.
However, amid macro interest rate path uncertainty and lingering Capex burdens, investors should closely track quarterly guidance to verify whether AI feature rollouts translate directly into free cash flow recovery.
Frequently Asked Questions
Q1. Won't the expansion of generative AI search erode Google's traditional search ad revenue?
A1. Contrary to initial concerns, the rollout of top-level AI overviews has spurred more granular, high-intent commercial queries, allowing ad click efficiency and core search revenue to maintain double-digit growth.
Q2. What role does Gemini Enterprise play in the corporate software market?
A2. Adopted by a majority of Fortune 100 enterprises for workflow automation, internal data analytics, and customer support, it acts as a primary catalyst expanding Google Cloud's long-term contract backlog.
Q3. How do Alphabet's custom TPU chips compete against Nvidia GPUs?
A3. In addition to delivering custom TPU accelerators through cloud infrastructure, Google has increasingly broadened external sales and strategic partnerships, carving out an efficient alternative in the accelerator market.
Q4. How significantly could the DOJ's antitrust case impact Alphabet's stock?
A4. Potential mandates requiring changes to default search engine distribution contracts across mobile and browser platforms, or structural adjustments to ad networks, represent critical monitoring points that could influence Traffic Acquisition Costs (TAC) and market share.
Q5. Why is annual CAPEX exceeding $90 billion viewed as a potential risk?
A5. Massive capital commitments across AI data centers and specialized power infrastructure pressure free cash flow (FCF) and raise future depreciation expenses, making rapid monetization and revenue return the defining metric for forward valuation multiples.